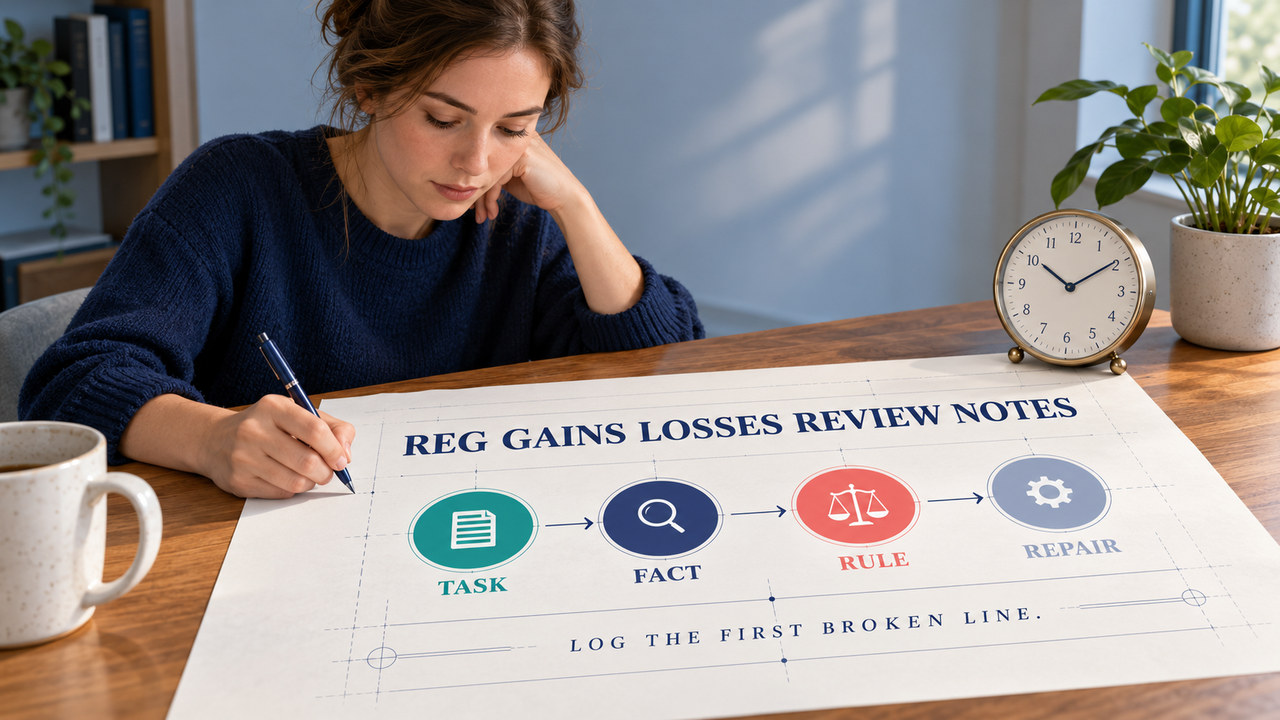

Direct answer: Use reg gains losses review notes as a miss-to-rule log. Write the task, the controlling fact, the rule boundary, the distractor shortcut, and one changed-fact repair before you attempt another mixed set. That record keeps a familiar word such as gain, loss, or state from replacing the actual reasoning. The original cases below are editorial practice, not official, recalled, leaked, or score-predictive questions.
Scope and freshness: Confirm task statements and skill levels in the AICPA CPA Exam Blueprints. Reopen the current AICPA resource page before carrying a simplified threshold, allocation rule, or recognition limit into a new study cycle. Use NASBA administration guidance for eligibility, scheduling, jurisdiction, and score questions.
For orientation, open the REG review hub. Then use the CPA study-plan overview for pacing, the Blueprint format guide for task boundaries, and the topic MCQ index or simulation practice guide when you need a different retrieval mode.
For a broader preparation path, continue with our related CPA study resources.
reg gains losses review: start with the task
First, the review note starts with the verb in the question. Next, “Calculate” calls for a numerical path. Then, “Assign” calls for place or source evidence. Therefore, “Apply” calls for a rule boundary. Finally, “Explain” calls for a fact-to-result bridge. Write that verb in the first line before reading the answer choices. Next, write the output the question can actually grade.
- Task: copy the decision verb and the requested output.
- Fact: circle the one number, place, date, relationship, or status that can move that output.
- Rule: write the supplied formula, allocation instruction, or recognition limitation.
- Repair: change one fact and predict which line of the answer will move.
Keep the review note narrow
A review note is useful when it explains one miss. It is not a transcript of every thought or a new textbook chapter. Use one sentence for the task, one line for the controlling fact, one line for the rule boundary, and one sentence for the next retry. If the case has several jurisdictions or related-party facts, keep the note attached to the exact output the prompt requested.
Set the reg gains losses review note template
Use the same four-field template for every original item. The template separates evidence from the conclusion, so a wrong answer leaves a repairable trail.
- Task
- What must the response produce: an amount, an assignment, a limitation result, or an explanation?
- Fact
- Which proceeds, adjusted basis, service location, payroll, property, relationship, or holding status can move that result?
- Rule
- Which current source, supplied formula, sourcing instruction, or recognition boundary decides whether the fact counts?
- Repair
- What single changed detail will force you to re-run the reasoning?
Do not write “I chose B” as the note. Write why the controlling fact supports the answer and why the nearest distractor drops or changes that fact. For a gross-proceeds error, the amount line is the first miss. A residence shortcut is a location-line miss. When a related-party loss is fully recognized, the limitation line is the first miss.

Apply original review-note cases
Next, attempt each case before opening its rationale. Mark the task, fact, rule, and repair line. Every case below is independently written study material and should remain separate from a live tax conclusion.
Open the first broken line
Attempt one original case first.
Reveal the answer
Answer: Review the worked explanation in the article.
Compare your process with the reasoning shown above.
Case 1: preserve the net-proceeds line
Original case file: A simplified exercise gives a sale price of $246,000, selling costs of $7,000, and adjusted basis of $177,000. It asks for recognized gain using net proceeds after selling costs minus adjusted basis.
Question: Which note belongs in the controlling-fact line?
- Gross proceeds are the answer because the sale price is the largest number.
- Net proceeds of $239,000 less adjusted basis of $177,000 produce a $62,000 result under the supplied exercise rule.
- The distractor ignores adjusted basis because cash alone cannot answer.
- The result is a loss because selling costs are present.
Open the rationale
Supported line: 2. The rule supplied by the stem controls the arithmetic. The distractors either drop selling costs, drop basis, or reverse the sign. Save the formula and write the changed-fact repair: what line moves if a buyer reimburses the selling costs?
Case 2: preserve location evidence
Original case file: A consulting firm receives $144,000. The firm performed 60% of services in State A and 40% in State B. It also supplies payroll of $72,000 split $45,000 to State A and $27,000 to State B, plus property of $38,000 split $30,000 to State A and $8,000 to State B. The exercise supplies a three-factor formula.
Question: What must the review note save before you calculate any percentage?
- Assign every receipt to the owner’s residence because that is the easiest location.
- Attach service, payroll, and property facts to their stated states, then apply the supplied formula.
- Choose State A because its payroll and property totals are larger.
- Compute a federal result and defer the state assignment.
Open the rationale
Supported line: 2. The location instruction is the boundary. The distractors substitute convenience, magnitude, or a different tax question for the supplied sourcing evidence. Change one service percentage and state which allocation line changes.
Case 3: preserve the recognition trigger
Original case file: An individual transfers an investment to a related party for $64,000 while adjusted basis is $91,000. The related party still holds the investment at year-end, and the exercise supplies a limitation on current recognition.
Question: What belongs in the rule line?
- Recognize the entire loss now because cash is below basis.
- Ignore the relationship because the file documents the transfer price.
- Record the relationship and holding status, apply the supplied limitation, and separate the current result from the delayed amount.
- Reverse the loss into a gain because the related-party relationship changes the rule.
Open the rationale
Supported line: 3. The relationship and holding status activate the supplied limitation. The other choices delete the trigger or change direction without evidence. Change only the holding status and write which recognition line you must revisit.
Audit the reg gains losses review note
Use three passes after the rationale. First, match the selected answer to the requested output. Second, point to the one fact that moved the result. Third, state the changed detail that would force a new path. If the note cannot name all three, the next action is a short repair, not a larger question set.
- Output pass: underline amount, place, limitation, or explanation.
- Evidence pass: cite proceeds, basis, location, relationship, date, or status.
- Transfer pass: change one detail and state the direction of the new answer.
Use the distractor as a diagnostic label. “Ignored selling cost” means repair the amount line. “Owner’s residence” means repair the source-location line. “Documented price” means repair the recognition-trigger line. This vocabulary turns a wrong answer into a next review action that you can check.
Separate source checks from simplified facts
These cases use simplified facts so the reasoning path stays visible. A current threshold, state formula, or related-party rule may change or require jurisdiction-specific detail. Mark a source-check flag in the note and reopen the authoritative AICPA or NASBA route before using a simplified statement outside study.
Choose the next reg gains losses review repair
Choose one repair only. Reopen the relevant source or supplied exhibit, rewrite the missing boundary in your own words, and complete one new case with one changed fact. The repair is complete when the new note shows task, fact, rule, distractor, and transfer without a guess.

For the next session, use the second visual as a miss-to-rule check. Classify the first delay as task, fact, rule, evidence, arithmetic, or transfer. The first marked cause becomes the next session’s target; do not add more volume until that line is stable.
Turn reg gains losses review notes into a loop
Keep a repeatable 12-minute block: two minutes to write the task and output, four minutes for one original case, three minutes to explain the nearest distractor, and three minutes for the changed-fact retry. End with a source flag. If the note still lacks a boundary, keep the next block on the same skill.
Meanwhile, keep editorial practice separate from a live tax conclusion. The linked AICPA and NASBA pages define the authority route; the cases, numbers, answer paths, and visual workpapers here are original study material. That separation lets you learn the reasoning without presenting a simplified prompt as current professional advice.
reg gains losses review checklist
- Did I copy the decision verb and requested output?
- Did I name the one fact that can move the answer?
- Did I compare proceeds with adjusted basis instead of using gross cash?
- Did I attach service, payroll, and property facts to the stated jurisdiction?
- Did I record relationship and holding status before applying a limitation?
- Did I mark a current source check when the simplified fact may not travel?
- Did I explain the strongest distractor’s shortcut?
- Did I change one fact and state the direction of the new result?
- Did I choose one bounded repair before adding more cases?
Finally, a durable reg gains losses review note contains the task, controlling fact, rule boundary, rejected shortcut, and transfer result. That evidence trail tells you what to review next more clearly than a raw score.
reg gains losses review questions
Are these official exam questions?
No. They are independently written teaching cases. Use current AICPA material for authoritative scope and terminology.
What should I save after a miss?
Save the task, controlling fact, rule boundary, distractor shortcut, and one changed-fact retry.
What if the jurisdiction rule is current-sensitive?
Mark a source-check flag, reopen an authoritative page, and keep the simplified case separate from any live conclusion.
Should I add more cases immediately?
Repair the first missing line before increasing volume. More items can preserve the same gap.