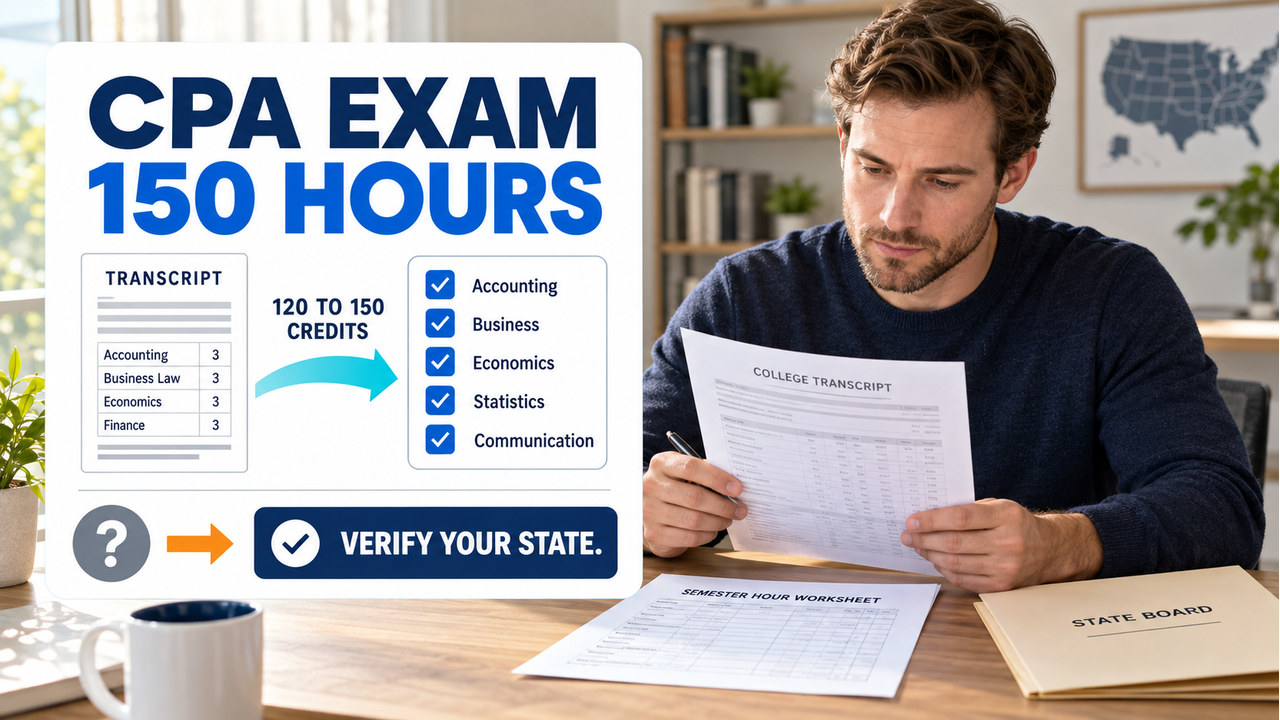

Quick answer: If you are searching for cpa exam 150 hours, do not read the number as a universal yes-or-no test. In the United States, the selected jurisdiction decides whether 150 semester hours are needed to sit for the CPA Exam, to apply for a CPA license, or to follow one of several pathways. Some jurisdictions use a lower exam-stage threshold; others attach 150 hours to licensure or a specific education-and-experience route. Start by naming the stage, then map your transcript before you enroll or pay.
For a broader preparation path, continue with our CPA Exam Study Guide.
CPA Exam 150 Hours: The Short Answer
The 150-hour figure usually means 150 semester hours of postsecondary education, or the accepted quarter-hour equivalent. It is commonly discussed as a bachelor’s degree plus roughly 30 additional semester hours. That arithmetic is a useful starting frame, but it is not an approval formula. A board may also inspect the degree, institution, accounting and business content, course level, official transcript, experience path, ethics requirement, and the effective date of the rule.
Keep two questions separate: May I apply to sit for the exam? and Have I completed the education and other requirements for licensure? NASBA says exam education requirements differ by state, while AICPA describes education, examination, and experience as separate parts of becoming licensed. A 150-hour answer without a jurisdiction and a stage is incomplete.
This guide gives you a working method rather than a generic state ranking. Use it to create a provisional gap map, identify the field that needs confirmation, and save the official board’s dated answer. For a broader overview of the exam path, see our CPA exam requirements guide.
What Does 150 Hours Mean for the CPA Exam?
A semester hour is an academic credit unit. It is not the same thing as a study hour, a work-experience hour, or a review-course hour. A college transcript may report semester hours or quarter hours, and the board may specify how the conversion is handled. Begin with the unit printed on the official record and use the board’s own conversion rule when one is provided.
The familiar 120-plus-30 picture helps a reader visualize the gap after a bachelor’s degree, but it leaves out the most important question: what must those credits contain? A person can have 150 total hours and still need a particular accounting, business, ethics, upper-level, or institution requirement. Another person may be allowed to sit at 120 hours but need a separate plan before applying for a license.
Think of the number as one column in a larger record. The following map keeps the decision owners separate:
| Checkpoint | What the hours can describe | Who confirms it |
|---|---|---|
| Exam eligibility | Education and named coursework required to apply for one or more exam sections | The selected jurisdiction or its authorized application service |
| Course-gap planning | Credits still needed after comparing your official record with the rule | You and the board’s current wording |
| Licensure education | Total hours plus the content and degree pathway required for a license | The selected state or territory board |
| Experience and ethics | Non-education requirements that do not disappear when the credit total is met | The licensing jurisdiction |

Exam Eligibility and CPA Licensure Are Different Checkpoints
The cpa exam 150 hours question often feels confusing because people use the word requirement for two different checkpoints. Exam eligibility means a jurisdiction has determined that you may apply for the Uniform CPA Examination. Licensure means you have completed the broader pathway after the exam, including any required education, experience, ethics, documents, and license application.
For example, Pennsylvania’s current official snapshot states that a candidate needs at least 120 semester credits to sit for the examination, then lists three license pathways with different education and experience combinations. That is a concrete illustration of stage separation, not a shortcut for candidates in every state. Texas likewise explains that an exam candidate has additional steps before becoming licensed, including education, experience, and ethics requirements.
New pathways are also being adopted. NASBA’s pathways page maintains a dated jurisdiction list and tells candidates to remain responsible for the board’s current laws and rules. A pathway can change the relationship among degree, credit total, experience, and license application without changing the fact that the board owns the decision.
Use this three-line note whenever you research a state:
- Exam stage: What must be true before I can apply and receive authorization to test?
- License stage: What education, experience, ethics, and application items remain after I pass?
- Freshness: What effective date, transition rule, or pathway update should trigger a recheck?
If your note combines those lines, stop and separate it before you calculate a gap. The most expensive mistake is enrolling in a course because a licensure headline looked like an exam-admission rule.
What Counts Toward the 150-Hour Requirement?
A total is necessary in some pathways, but the total alone is rarely the whole test. Start with five fields from your official transcript: degree or credential, total semester-hour equivalent, named accounting content, business or other required content, and course level plus rule date. Add institution and delivery details when the board or evaluator requests them.
Count the record, then match the content
Do not count credits twice. Mark transfer work, repeated classes, remedial work, post-degree work, and courses taken at more than one institution. Record whether the degree is posted on the transcript. If your record uses quarter hours, preserve the original number and write the converted number in a separate column so the source is auditable.
Then match course titles and descriptions to the board’s categories. A class called Business Analytics may or may not fit a rule that uses a narrower phrase. A course called Financial Accounting may still need the required level or institution. When the wording is unclear, label the row verify rather than converting uncertainty into a confident yes.
| Map field | What to record | Stop condition |
|---|---|---|
| Degree or credential | Degree, institution, country, award date, and recognition details | The credential or degree status is not documented |
| Total credit | Official semester or quarter units, transfer and post-degree notes | The total changes under an unverified conversion |
| Accounting content | Course title, description, credits, level, and institution | A similar title cannot be mapped to the rule’s category |
| Business and other content | Business, ethics, technology, or other named areas | The rule’s category or minimum is unclear |
| Level and date | Upper-level or graduate status, effective rule date, record version | The rule changed or the course level is unstated |
Commercial CPA review courses are not the same as academic credit. A review course may help you prepare, but it should not be counted toward the 150-hour figure unless the responsible board explicitly recognizes the credit in the required way. Treat every paid option as a decision that follows, not precedes, the transcript comparison.
Use a 30-Credit Gap Calculation Without Making a Promise
Suppose Jordan has a completed bachelor’s degree and an official record showing 120 semester hours. The provisional arithmetic is 150 minus 120, or 30 hours. That tells Jordan the size of the possible gap; it does not tell Jordan which 30 hours to buy or whether 150 is required at the exam stage.
Jordan’s next move is to build a course map. The record shows 6 accounting hours, 3 business-law hours, and several general electives. The selected board’s rule names financial accounting, auditing, taxation, and a business-content minimum. Jordan may therefore have both a total-hour gap and a named-course gap. Adding 30 unrelated electives could close the first column while leaving the second unresolved.
Use the following four-step method:
- Classify: label the stage as exam eligibility, license education, or both.
- Count: record the official units and calculate a provisional difference from the applicable total.
- Match: map actual courses to every named category, level, and institution condition.
- Confirm: send the board one narrow question about the first unresolved row and save the dated response.
This method also prevents a common false comparison. A page may say a state allows candidates to sit with 120 hours, while a different section of that page describes 150 hours for a license. Neither statement is wrong; the error is treating them as the same stage.
How State Rules Change the Answer
There is no responsible one-line national list for this query. NASBA’s general licensure guidance says the education requirement to sit varies by state and can include specific accounting or business coursework. The correct comparison is therefore conditional: what does this jurisdiction require at the exam stage, what does it require for a license, and what date controls the rule?
Here are three bounded examples from current official pages:
| Official example | What the page illustrates | How to use it safely |
|---|---|---|
| Pennsylvania | 120 semester credits to sit; three license pathways with different education and experience combinations | Use it to see exam-versus-license separation, not to choose another state |
| Texas | An exam candidate has additional education, experience, ethics, and application steps; the page describes a 150-hour step and an alternative pathway | Open the Texas board page if Texas owns your route |
| New York | Dated 120- and 150-semester-hour pathways with detailed accounting and business content | Read the effective date and transition language before relying on it |
These examples also show why competitor state tables are useful for finding questions but risky as final evidence. A summary can age when a legislature changes a pathway, when a board revises a course category, or when an application service changes its instructions. Use the official page, preserve its access date, and note the event that would force you to check again.

Build a Safe 150-Hour Verification and Course Plan
A good plan answers the board’s question before it commits your tuition budget. Work in this order:
- Choose the licensing target or exam jurisdiction. If you do not know it yet, start with NASBA’s jurisdiction directory and list two or three plausible boards without declaring a winner.
- Retrieve complete official records. Gather every transcript, degree posting, transfer record, and course description that the board may require. Keep original records in a secure channel.
- Label the stage. Write exam eligibility, license education, or both at the top of the worksheet.
- Count units without hiding the source. Keep semester and quarter figures separate and annotate any conversion or transfer treatment.
- Match named content. Mark each accounting, business, ethics, level, and institution condition as met, missing, or verify.
- Ask one narrow board question. Include the exact course title, credit value, level, transcript source, rule URL, and access date. Save the answer before enrolling or applying.
If the board confirms a gap, choose a credit route that fits the confirmed category and delivery rule. A graduate program, post-baccalaureate course, community-college class, or another academic option may be useful in some jurisdictions, but the article cannot tell you which option counts without your board’s rule. The decision is not “How do I buy 30 hours?” It is “Which verified course or pathway closes the first documented requirement?”
Recheck before a payment, application, NTS acceptance, travel plan, or license filing. Put the source date and effective date in the worksheet. That small habit makes a future update visible instead of allowing an old screenshot to control a new decision.

What Changes for International or Transfer Credits?
International and transfer records add an evidence layer. A foreign transcript may need an evaluation, translation, official delivery, course descriptions, or a board-approved service. A transferred class may appear on one institution’s record but be accepted only when the original institution’s transcript is also supplied. The selected jurisdiction controls which route is acceptable.
Do not treat an evaluation report as universal approval. It can help a board understand the credential, but it may not answer whether a particular accounting course, level, or category satisfies the current exam or license rule. Preserve the original units, the evaluator’s conversion, and the board’s written interpretation as separate evidence.
The same principle applies to quarter hours. Use the board’s stated conversion, show the math, and keep the unconverted source beside it. If the evaluator or board requests a different record, stop at that gate rather than filling the difference with an assumed number.
Common 150-Hour Mistakes That Delay Candidates
- Using the license number for the exam stage. A licensure pathway can require more education or experience than the route to sit.
- Counting only the total. Named accounting, business, ethics, level, and institution conditions can remain open.
- Assuming the extra 30 may be any credits. The board may restrict content or delivery.
- Copying a static state table. Pathways and effective dates can change.
- Counting a commercial review course as college credit. Preparation value and academic credit are different questions.
- Ignoring transfer and repeated courses. The official source and the board’s treatment matter.
- Paying before asking. A cheap course is still a bad purchase if it does not close the confirmed gap.
- Assuming the exam completes licensure. Experience, ethics, documents, and a license application may remain.
Choose Your Next CPA Education Check
Use the decision flow below to identify the first unresolved field in your record. It is a routing tool, not a state eligibility decision.
Choose your next CPA education check
Which statement best matches your record right now? Choose one route, then complete the evidence check before enrolling, applying, or paying.
- I have about 120 credits and a completed bachelor's degree.
- I have 150 total credits but do not know whether the named courses count.
- I am short of 150 credits and have not chosen a jurisdiction.
- My credits are international, transferred, or recorded in quarter hours.
Check your reasoning
Answer: Start with the first field you cannot support: stage, total semester-hour equivalent, named course content, course level, institution, or effective date. Then ask the selected jurisdiction's board one narrow question and save the dated response.
The 150-hour figure is a planning frame, not a universal approval. A useful next action is different for a 120-credit exam-stage candidate, a 150-credit licensure candidate with a course gap, and a reader with international or transfer records.
After the flow, take one small action: open the official board page, copy the sentence that controls your stage, and compare it with one transcript row. A narrow question such as whether a named course satisfies the exam-stage accounting category is more useful than asking whether your whole degree is acceptable.
CPA Exam 150 Hours FAQ
Does everyone need 150 hours to sit for the CPA Exam?
No universal answer is safe. NASBA says education requirements to sit differ by state. Some jurisdictions use a 120-hour exam-stage threshold, while others may require 150 or a more specific combination of degree and coursework. Check the current rule for the jurisdiction that will review your application.
Is 150 semester hours the same as a CPA license?
No. Education is one part of licensure. You may also need to pass all four exam sections, meet experience and ethics requirements, and file a license application under the board’s current pathway.
Can the extra 30 credits be any college courses?
Do not assume that. A board may evaluate total hours plus named accounting, business, ethics, level, or institution requirements. The correct course choice depends on the selected jurisdiction and the gap shown by your official transcript.
Can a master’s degree automatically solve the 150-hour gap?
A graduate program can add credits, but the board still decides whether the program and individual courses satisfy its rule. Compare the course list with the board’s wording before you enroll.
Do international or quarter-hour credits count?
They may be reviewable, but the conversion, evaluation, official delivery, and accepted course content are jurisdiction-specific. Follow the selected board’s current instructions and use an approved evaluation route when required.
Key Takeaway
The practical meaning of cpa exam 150 hours is not a national promise that every candidate must collect the same 30 extra credits. It is a prompt to label the stage, count the official record, match named course content, and confirm the first unresolved field with the jurisdiction that owns the decision. Save the source date and recheck trigger before you enroll, apply, or pay.
Sources
- NASBA: How to Get Licensed
- AICPA & CIMA: Road map to the CPA Exam and becoming a CPA
- NASBA CPA Exam Candidate Guide, July 16, 2026
- NASBA: Licensure Pathways
- Pennsylvania Department of State CPA snapshot
- Texas State Board of Public Accountancy: Candidates
- NASBA: New York CPA Exam requirements
CPA exam questions
Does everyone need 150 hours to sit for the CPA Exam?
No universal answer is safe. NASBA says education requirements to sit differ by state. Some jurisdictions use a 120-hour exam-stage threshold, while others may require 150 or a more specific combination of degree and coursework. Check the current rule for the jurisdiction that will review your application.
Is 150 semester hours the same as a CPA license?
No. Education is one part of licensure. You may also need to pass all four exam sections, meet experience and ethics requirements, and file a license application under the board’s current pathway.
Can the extra 30 credits be any college courses?
Do not assume that. A board may evaluate total hours plus named accounting, business, ethics, level, or institution requirements. The correct course choice depends on the selected jurisdiction and the gap shown by your official transcript.