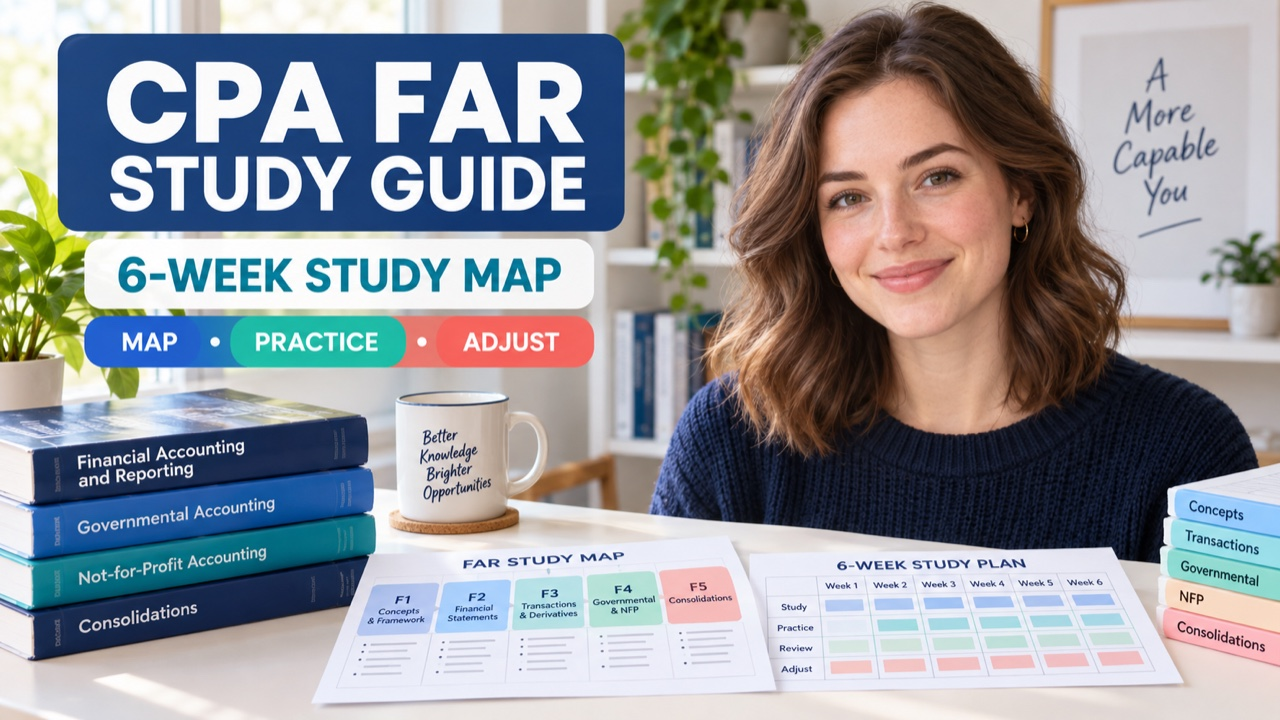

Quick answer: A useful cpa far study guide starts with the current Blueprint, turns each topic into a small proof task, and ends every study block with a next action. Use the six-week route below as a flexible frame. It is not an official weighting table, a score calculator, or a promise that one schedule fits every candidate.
This page is for a candidate who knows FAR is broad but needs a route through it. It gives you a scope check, a topic map, a six-week sequence, and a repair rule. For a broad module list, continue to the site’s FAR review hub. Use this guide when you need to decide what to do next.
How to use this cpa far study guide
Start with the row you are trying to improve, not with a random chapter. Open the current AICPA Blueprint and note the Area, Group, Topic, task statement, skill level, item type, and weighting that apply to your study target. The Blueprint is the scope boundary. Your notes, question bank, and review videos are study tools underneath that boundary.
Next, choose one small proof task. For example, you might need to classify a cash-flow adjustment, explain a measurement rule, trace a consolidation entry, or connect an exhibit to a conclusion. A proof task is easier to review than “study FAR.” It also gives your practice a visible finish line.
Use the guide in three passes. First, map scope. Second, run a focused learn-and-practice block. Third, label the first point where your reasoning failed. That label determines the next resource. Do not restart the whole section every time one question goes wrong.
Map the FAR Blueprint to a study route
First, the current Blueprint organizes exam content by Area, Group, Topic, task statements, skill levels, references, item types, and weighting. In addition, it describes FAR with two MCQ testlets followed by three TBS testlets. Those details help you plan mixed practice, but they do not tell you how many hours your personal week requires.
Next, build your map with four working lanes. Treat these as study labels, not as replacement names for official Blueprint rows:
- Statement mechanics: identify what a statement, adjustment, or disclosure is trying to show.
- Measurement and transactions: connect inputs, assumptions, recognition, and the resulting number.
- Reporting relationships: trace how one fact affects presentation, consolidation, cash flow, or another linked output.
- Research and transfer: handle an unfamiliar fact, locate the controlling evidence, and explain the boundary.
Then attach each lane to the current Blueprint. If a topic does not have a clear row, do not invent an official task code. Write a plain study label and verify the underlying literature when the question depends on an exception or effective date.
Build a three-column cpa far study guide map
For every topic, keep three short columns: question, evidence, and next action. Your question column states what you must be able to do. Evidence names the fact, rule, exhibit, or formula that proves the answer. Next, the action column tells you what to practice after the block.
Here is a simple example. The question might be, “How does this noncash item affect an indirect cash-flow reconciliation?” The evidence column can hold the fact pattern, the starting net income, and the noncash adjustment. The next action can be, “solve one new version, then explain the sign without looking at the notes.” That map is more useful than a vague note that says “review cash flows.”
Use the same structure for a TBS. Record the requested output first. Then name the exhibit that controls it. Next, write the smallest defensible formula or classification. Finally, state what would change if one fact moved. The site’s task-based simulation guide can support this exhibit-to-output practice when your gap is transfer rather than recognition.
Finally, keep the map small enough to update. One row can cover a single topic and one proof task. When you miss, edit the row instead of adding a second copy of the same topic. The goal is a living route, not a larger notebook.
Run the six-week cpa far study guide cycle
First, the six weeks below give each block a different job. Next, adjust the time, topic order, and depth to your exam date and current evidence. The sequence is a study aid, not an official FAR weighting claim.

Use weekly checkpoints
At the end of each week, record the first failed reasoning step and schedule one focused retry. This checkpoint keeps the plan tied to evidence rather than to the calendar alone.
- Week 1 — Scope and baseline. Read the current Blueprint, choose the first topic lanes, and complete a short mixed baseline. Record whether each miss came from scope, rule recall, calculation, reading, or transfer. Do not spend the week polishing a color-coded calendar while the first gap remains unnamed.
- Week 2 — Build the rule. Choose the most important weak lane. For each topic, write one plain-language rule, one boundary, and one worked example. Check technical details against current authoritative literature when needed. End each session by explaining the rule without copying your notes.
- Week 3 — Practice one variable at a time. Use targeted MCQs to test recognition and calculation. Change one input after you solve the original item. If the answer changes in the wrong direction, return to the evidence column and repair the model before adding more volume.
Shift from practice to transfer
- Week 4 — Add exhibits and transfer. Mix in TBS-style tasks. Read the requested output first, assign each exhibit a job, and write the smallest answer path. Review the first wrong step. A correct final number with an unsupported path still needs a review note.
- Week 5 — Mix the lanes. Combine topics in shorter blocks. Move from one topic to another without rereading every chapter. Keep a simple error log with the topic, error type, nearest distractor, and next retry date. Mixed work shows whether the rule survives a change of context.
- Week 6 — Verify and adjust. Run a timed mixed block, then compare your coverage, accuracy, and transfer evidence. Keep the first repair visible. When you are correct only with notes, keep learning. If you are correct untimed but slow, shorten the block and rehearse the response format. When you can explain and transfer, advance to the next lane.
Choose MCQ or TBS practice with evidence
Choose the format that matches the bottleneck. Start with notes or a worked example when you cannot state the rule. Next, use a targeted MCQ block when you know the rule but miss the calculation or recognition cue. Then, use TBS work when you can answer isolated questions but cannot decide which exhibit controls the output. Finally, use a timed mixed block when your untimed reasoning is sound but your process is slow.
However, do not treat the official testlet description as a reason to chase a fixed question count. Instead, treat it as a reason to practice both formats. A current NASBA or AICPA score page may discuss a passing score of 75, but that reported score is not 75 percent correct. Therefore, your practice log should record the reasoning signal, not promise a scaled result.
When a technical conclusion depends on a scope exception, effective date, or detailed US GAAP rule, first research the current FASB Accounting Standards Codification. Keep that research boundary separate from a quick study explanation. For original practice, you can also use the site’s FAR practice questions page, then return here to choose the next repair.
Review readiness with a FAR study guide checklist
Readiness is not one feeling. After each block, review three signals:
- Coverage: Can you name the current Blueprint row and the rule boundary?
- Accuracy: Can you solve a clean version without notes and reject the closest distractor?
- Transfer: Can you handle a changed fact, a new exhibit, or a different response format?
Then, use the checklist below as a handoff. The first unchecked item is your next action.
FAQ and next action for cpa far study guide
How many weeks should a CPA FAR study guide use?
In practice, six weeks is a planning frame, not a rule. Stretch or compress it after checking your exam date, available hours, prior coursework, and the first evidence gap. A shorter plan still needs scope, practice, verification, and a next action.
Should I begin with MCQs or TBSs?
Instead, begin with the format that exposes the first bottleneck. MCQs can reveal recognition and calculation gaps. TBS work can reveal evidence mapping and multi-step transfer gaps. Most candidates benefit from moving between both once the basic rule is clear.
Does a practice percentage predict a CPA score?
No. Practice accuracy is a local study signal. It is not a 0–99 score, a percentage-correct conversion, or a passing-outcome forecast. Record what you could explain and transfer instead.
How often should I refresh the guide?
Finally, recheck the current AICPA Blueprint and relevant FASB literature before a dated plan. Confirm eligibility, NTS, fees, credit, and scheduling with the responsible jurisdiction-specific source. Those administration details do not belong in an evergreen accounting shortcut.
Next action: open the FAR review hub, choose one Blueprint topic, and write its question, evidence, and next action before starting your next practice block. If you need a broader multi-section calendar, use the site’s CPA Exam Study Guide.
Sources and refresh note for cpa far study guide
Scope and current FAR structure: AICPA CPA Exam Blueprints. Format familiarity: AICPA sample tests. Score-language boundary: AICPA scoring guidance. Candidate administration: NASBA CPA Exam FAQ. Technical research: FASB Accounting Standards Codification. Checked September 18, 2026. Reopen these live official pages and refresh the workbook’s Semrush US fields before publication. The map, six-week route, proof loop, examples, decision rules, and checklist are original editorial study content. Editorial review confirms the separation between official boundaries, technical research, and personal study guidance; this page is not legal, accounting, or licensure advice.