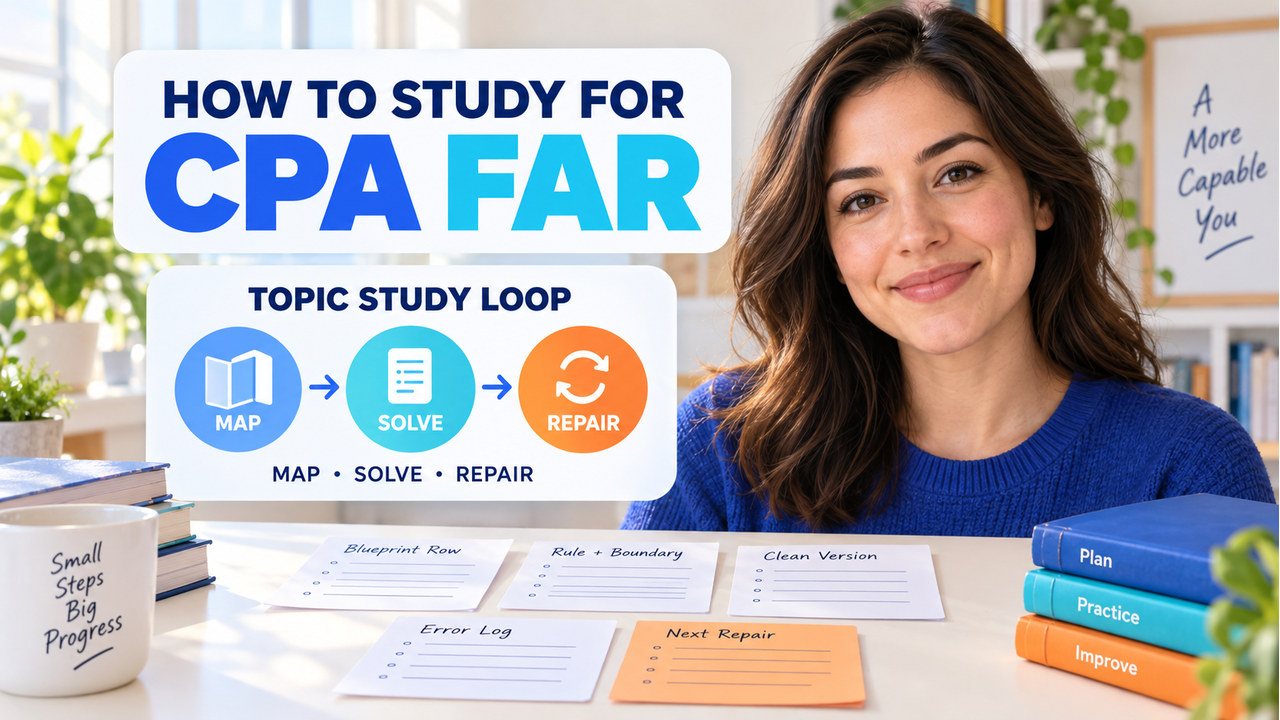

Quick answer: To learn how to study for CPA FAR, stop treating a chapter, a question count, or a calendar streak as the unit of progress. Start with one current Blueprint task, write the rule and its boundary, solve a clean version, test one changed fact or exhibit, and schedule the smallest repair from the first unsupported step. This method is study guidance, not an official weighting table, score calculator, or promise that one routine fits every candidate.
This page fits a FAR candidate who has access to a course or question bank but needs a reliable way to use it. If you need broad section navigation, start with the site’s FAR review hub. If you need a week-by-week capacity schedule, use the related study-plan page after you choose the topic method below.
How to study for cpa far: Start with one Blueprint row
The first decision is scope. Open the current AICPA Blueprint and choose one row that is small enough to explain and test in the time you have. Record the Area, Group, Topic, task statement, skill level, and response format. These fields keep a study session attached to tested work instead of turning it into an open-ended chapter tour.
- Target: name the smallest current task statement you can act on.
- Skill: note whether the task asks you to remember, understand, apply, analyze, or evaluate.
- Output: decide whether the first proof should be an MCQ, a calculation, an exhibit path, or a TBS-style response.
- Boundary: write what is outside this session so a difficult exception does not expand the topic without a decision.
A good study unit has one sentence that a reviewer could audit: “I will explain this task, solve one clean version, and test one changed fact.” If you cannot write that sentence, narrow the target before opening more material.
Make the how to study for cpa far target small enough to test
Use one target row, one evidence question, and one next action. For example, a cash-flow adjustment unit might ask you to state the adjustment logic, work a clean numerical example, and explain what changes when one input changes. It does not need to reproduce an official question. If the example turns on a detailed US GAAP exception, pause and check the current FASB Accounting Standards Codification.
Build a how to study for cpa far topic unit
Before studying, prepare four small artifacts. They make the session observable and prevent passive rereading from feeling like mastery.
- Scope card: copy the Blueprint row and write the expected output in plain language.
- Rule card: write the rule, one boundary, and one reason a tempting shortcut would fail.
- Practice card: choose a clean question or task that tests the same skill without extra noise.
- Evidence card: leave space for coverage, accuracy, transfer, and the first unsupported step.
Write a one-sentence rule and boundary
The rule card is not a miniature textbook. It should be short enough to say aloud and precise enough to stop a wrong shortcut. Add the boundary immediately: what fact, classification, date, or exhibit would make you look up the source? This habit is especially important in FAR because a familiar label can hide a different measurement, presentation, or disclosure task.
Create a clean version before adding difficulty
A clean version removes time pressure and irrelevant facts. Solve it with notes available, then solve it again without notes. If the second attempt fails, the gap is still in explanation or rule use. Do not respond by adding a harder mixed set; repair the first missing step first.
Run a five-pass how to study for cpa far loop
The loop is a reusable topic method. A pass can be short, but each pass must produce evidence for the next decision.
Pass 1 — Map the target
Read the Blueprint row and identify the requested action. Mark the nouns that define the scope and the verbs that define the skill. Then write one question: “What would a correct response have to show?” This prevents a vocabulary review from standing in for an application task.
Pass 2 — Explain the rule
Use your course, notes, or current technical source to write a plain-language explanation. Include one boundary and one worked step. Close the source and explain the rule aloud or in writing. If the explanation depends on a phrase you cannot define, mark that phrase as the first gap.
Pass 3 — Solve a clean version
Choose one focused MCQ, calculation, or short exhibit task. Before calculating, write the requested output and the sign, unit, or classification you expect to use. After the attempt, record the first wrong step rather than only the final answer. A correct guess is not the same as a supported solve.
Pass 4 — Test transfer
Change one fact, add one relevant exhibit, or switch the response format. An MCQ skill may need a TBS-style transfer check; a calculation may need an explanation of why the result changes. Keep the change small enough to identify the cause if performance drops.
Pass 5 — Repair and queue the next rep
Choose the smallest repair that addresses the first unsupported step. That may be another explanation, a two-question targeted set, a source check, an exhibit-reading drill, or a timed retry. Write the next rep as an action with a stopping rule: “After two supported solves, test one changed fact.”

Choose a how to study for cpa far block by evidence
Use the time you actually have, but let the evidence choose the job. A longer block is not automatically better if the first gap is still unnamed.
Use a 45-minute block for one narrow repair
Spend 5 minutes naming the Blueprint row, 15 minutes rebuilding the rule, 15 minutes on a clean solve, and 10 minutes labeling the next gap. This block is useful after a missed day or when your available time is limited. Keep the topic narrow and leave a clear stopping note.
Use a 90-minute block for learn, solve, and transfer
Spend 10 minutes on scope, 20 on explanation, 25 on a clean version, 20 on a changed fact or exhibit, and 15 on the handoff. This is a complete topic loop when the target is familiar enough to enter practice but not stable enough for a mixed set.
Use a 120-minute block for two formats and error review
Add a second transfer attempt only after the first unsupported step is labeled. Use one focused MCQ set and one TBS-style or exhibit-based task when the evidence calls for both. Finish by rewriting the error in a way that another candidate could follow. More questions without a repair note are just more unclassified evidence.
Use how to study for cpa far practice formats deliberately
Match the format to the gap rather than forcing every weakness through the same question bank routine.
- Rule recall is missing: return to the rule card and explain the boundary before attempting more questions.
- The rule is clear but the number is wrong: use a short MCQ or calculation set, write the setup before the arithmetic, and change one input on retry.
- The isolated solve works but exhibits cause confusion: use a TBS-style task and assign each exhibit one job before reading every detail.
- Untimed work is supported but slow: use a short timed block, then review the first unsupported or slow step rather than only the final time.
- The technical boundary is unclear: stop volume and consult current literature. The site’s FAR practice questions can provide drills after the rule is clear, while the task-based simulation guide can support evidence-to-output transfer.
The AICPA sample test is useful for learning the software and response environment. It is not scored and does not tell you whether your FAR preparation is ready. Keep software familiarity, local study evidence, and official score language in separate boxes.
Keep a how to study for cpa far review handoff
Close every topic session with a handoff. The goal is not to mark a chapter complete; it is to make the next useful rep obvious.
When all six lines are checked, move the topic into a light review queue and choose the next Blueprint row. If one line remains unchecked, keep the same target and change the study action. A review queue should preserve the first gap, not erase it with a new percentage.
Keep how to study for cpa far review honest
Review the rule card after a short gap, then retest one clean version and one changed fact. If both are supported, add the topic to a mixed set. If either fails, return to the first unsupported step. This is a local decision rule, not a prediction of a 0–99 score or a guarantee of passing.
How to study for cpa far when a week breaks
Missed days do not require a full reset. First, protect the next available block and reopen the last handoff. If the scope card is still valid, continue from the first unchecked line. If work, travel, or a new official update changed the boundary, rebuild the Blueprint row before adding practice.
When energy is low, use a 45-minute repair block. If time expands, add transfer and review rather than racing through unrelated chapters. When your question accuracy drops, record whether the cause was scope, rule, calculation, reading, exhibit mapping, or timing. The label tells you which pass to repeat.
If administration, eligibility, NTS, fees, credit, or scheduling is the real problem, leave the study loop and check current jurisdiction-specific guidance such as the NASBA CPA Exam FAQ. Do not make a study method carry facts that belong to a changing administrative process.
How to study for cpa far FAQ and next action
Should I read the whole FAR chapter before practicing?
No. Define one Blueprint task, learn enough to state the rule and boundary, and use a clean version to expose the next gap. Expand the reading only when the boundary or source check requires it.
How many FAR questions should I do in a session?
Use the number that lets you classify the first unsupported step and repair it. A small supported set is more useful than a large unreviewed count. The right volume changes with the task and your available time.
Should I study MCQs or TBSs first?
Start with the format that reveals the current gap. Use focused MCQs for recognition or calculation, then add a TBS-style task when evidence selection, exhibits, or multi-step transfer is the problem.
Can my practice percentage predict my CPA score?
No. A practice percentage is a local signal. Official section scores are reported on a 0–99 scale and are not percentage-correct conversions. Use coverage, accuracy, transfer, and timing to choose the next repair.
Next action: open the FAR review hub, choose one current Blueprint task, write its rule and boundary, and run the first three passes in your next protected block. For a broader multi-section route, continue to the site’s CPA Exam Study Guide.
Sources and refresh note
Scope and current FAR structure: AICPA CPA Exam Blueprints. Format familiarity: AICPA sample tests. Score-language boundary: AICPA scoring guidance. Candidate administration: NASBA CPA Exam FAQ. Technical research: FASB Accounting Standards Codification. Checked September 18, 2026. Reopen the live official pages and refresh the workbook’s Semrush US fields before publication. The topic-unit contract, five-pass loop, time-block guidance, error routing, worked method, and checklist are original editorial study content. This page is not legal, accounting, or licensure advice.