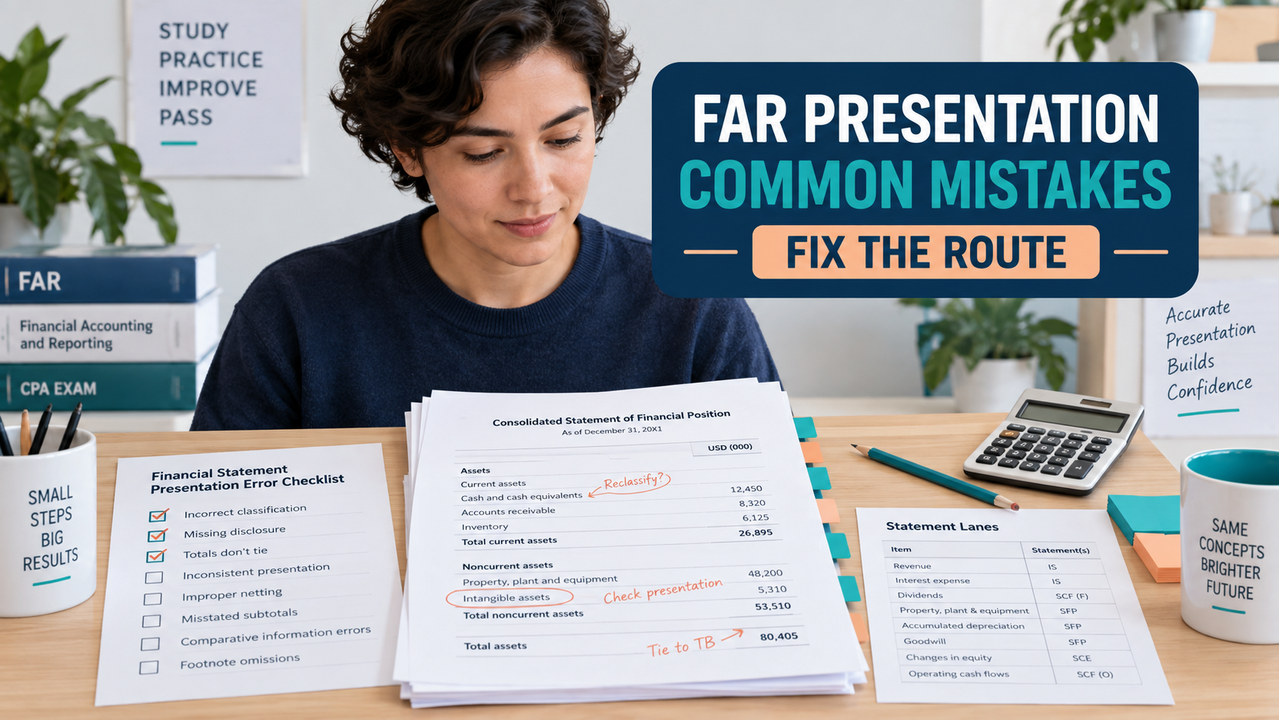

Far financial statement presentation common mistakes usually begin before the calculation. A learner sees a familiar account label, grabs the biggest number, and chooses a statement lane before asking what the event actually was. The repair is an evidence-first route: name the required output, identify the event, link the calculation, choose the presentation or cash-flow destination, check the disclosure path, and tie the conclusion back to current guidance.
This page uses original editorial practice facts, not an official or provider-owned CPA Exam question. The difficulty is moderate: the arithmetic is light, but each fact pattern separates recognition, measurement, display, cash-flow classification, and disclosure. If a changed fact affects entity type, reporting date, materiality, disposal scope, tax, or an effective date, reopen the current applicable topic instead of trusting a shortcut.
For a broader preparation path, continue with our CPA Exam Study Guide.
Financial Statement Presentation Common Mistakes: What These Errors Reveal
Presentation is not one final formatting step. In a TBS, it can involve four linked questions: Was the item recognized? Was the amount measured correctly? Where should the effect appear on the statements? What belongs in a note or supplemental disclosure? A response can be right on one question and wrong on the next.
The most useful diagnosis is therefore not “I forgot the rule.” It is “Which handoff broke first?” A scope error changes what you are solving. An event error changes the substance. A calculation error changes the amount or sign. A destination error sends a correct amount to the wrong lane. An evidence error leaves the conclusion unsupported or unreconciled. The rest of this guide turns those handoffs into a correction checklist.
Use this financial statement presentation common mistakes checklist to diagnose the first broken handoff before changing an amount or statement lane.
Use the five-part route before touching the numbers
Write five short prompts at the top of your scratch area:
- Scope: What does the cell ask for—amount, classification, presentation, correction, or disclosure?
- Event: What happened economically, and on what date?
- Calculation: Which amount, sign, carrying value, or change is actually linked to the requested output?
- Destination: Which statement, cash-flow category, line, or note receives the effect?
- Verify: Which current source and cross-statement tie-out would make the conclusion defensible?
Do not let an answer option supply the missing reasoning. If an option says “operating revenue,” start by asking whether the event was a customer sale, an owner contribution, an asset disposal, or something else. When another option says “cash paid,” confirm that cash moved in the reporting period. For “separate presentation,” identify the scope facts that justify it.

Financial Statement Presentation Common Mistakes: Mistake 1 — Letting the Account Label Define the Event
Consider an original practice fact pattern for Hawthorne Retail Systems. Equipment cost $260,000, accumulated depreciation is $180,000, and cash proceeds from the sale are $95,000. The draft posted the full $95,000 as operating revenue and left the equipment balance untouched.
Start with the carrying amount: $260,000 minus $180,000 equals $80,000. That carrying amount produces the simplified gain: $95,000 minus $80,000, or $15,000. The nearest distractor calls the entire cash receipt revenue because money arrived. A better route distinguishes the gain from the proceeds, removes the old asset balance, and sends the cash-flow question to the appropriate investing path under the applicable guidance. Finally, keep the exact presentation and disclosure conclusion tied to the current topic and facts.
Correction sentence: The event is an equipment disposal, and the $80,000 carrying amount controls the calculation. Do not collapse the $15,000 gain and the $95,000 proceeds into operating revenue.
Mistake 2: Routing every cash amount to operating activities
A cash column does not answer the cash-flow question by itself. Ask what generated the cash. Customer collections belong to an operating activity. When the company issues common shares, the receipt is an owner-financing event. When the company sells equipment, the proceeds connect to an investing event. The same amount can also have a separate income-statement or balance-sheet effect, so do not force one classification to answer every statement question.
In another Hawthorne practice item, the company issued shares for $140,000 cash. The general receipts screen labeled the deposit “service income.” The mistake is not merely a bad label: it changes equity, income, and cash-flow reasoning at once. The correction starts with the source of the cash, then checks the equity entry, then routes the cash-flow effect. A system label is evidence about data entry, not proof of economic substance.
Reveal the three-line correction
Classify three original facts before opening the correction: a customer collection, an owner share issuance, and a note-funded equipment acquisition.
Reveal the answer
Answer: Customer collection is operating; owner share issuance is financing; equipment acquired with a note is noncash until cash actually moves. An equipment sale is a separate investing question, not operating revenue.
The route follows the event's substance and the current applicable topic, not the data-entry screen, account label, or the fact that a number appears in a cash column.
Mistake 3: Putting a noncash event into the cash-flow total
Recognition and cash movement are different facts. Suppose Hawthorne acquires equipment by signing a $110,000 note on December 31. The equipment and obligation may require recognition under the applicable guidance, but Hawthorne pays no cash on the commencement date. Adding $110,000 to a cash-flow total invents a cash movement.
Use a two-line check: “Which event did Hawthorne recognize?” and “What cash changed hands during this period?” Then review the applicable supplemental noncash disclosure requirement. If Hawthorne pays the note later, that cash payment is a new event with its own classification. The common mistake is carrying the original recognition entry forward as if it were a later cash receipt or payment.
Financial Statement Presentation Common Mistakes: Mistake 4 Scope Gate
A component disposal can look like an automatic separate-presentation question, but the facts and current scope criteria determine the conclusion. Do not move a result to discontinued operations or a separate line merely because the prompt uses the word “sold.” Start by identifying what the component represented. Then confirm whether the exhibit supplies the required threshold or strategic-shift facts and which reporting date applies.
For practice, write “scope supplied” or “scope still open” beside the exhibit. If the prompt explicitly supplies the controlling criterion, use it as an assumption and continue. When it does not, record the missing fact and reopen the current presentation and disclosure topic. This habit prevents a familiar label from doing technical work that the exhibit never authorized.
Mistake 5: Treating disclosure as an afterthought
A correct amount can still need better presentation. Ask where the amount belongs: on the face of a statement, in a note, in a supplemental schedule, or in more than one place. Also check whether aggregation hides information that users need to understand the nature, amount, timing, or uncertainty of the item. Do not assume the answer is always “show a new line.” Sometimes you should clarify the note, separate the category, or provide a supplemental noncash disclosure.
Keep the three questions separate: display asks where the number appears; disclosure asks what additional explanation the note needs; materiality asks whether the level of detail changes the useful presentation. A TBS distractor often gives a technically true note requirement but attaches it to the wrong event or period.
Trace the same fact across recognition, measurement, display, and cash movement to make most financial statement presentation common mistakes easier to fix.
Mistake 6: Failing to reconcile the correction across statements
Before submitting, run a short tie-out. Remove the old carrying amount from the balance sheet when the asset leaves the records. Make sure the income-statement effect agrees with the gain calculation. Route cash proceeds to the lane that matches the event and period. If no cash moved, exclude the event from the cash-flow total even when recognition occurred.
Then write one proof sentence: “Because the event is ___, the controlling fact is ___, so the effect belongs in ___ rather than ___.” If you cannot complete that sentence without changing verbs halfway through, the route is probably incomplete. This is a small defense step, but it catches sign errors, date swaps, and destination shortcuts that a calculator will not catch.

Run the Financial Statement Presentation Common Mistakes Check in Two Minutes
Try this before reading the feedback. Hawthorne receives $75,000 from a customer, issues shares for $140,000, and signs a $110,000 note for equipment without paying cash at signing. For each fact, write the event, the likely destination, and the nearest wrong label. Do not solve a different question about later payments or tax effects.
Classify the customer receipt as a customer transaction. Treat the share issuance as an owner contribution. Record the note-funded equipment as noncash recognition at signing. The point is not to memorize three isolated labels; it is to show why the event controls the route and why you cannot backdate a later cash payment into the original recognition date.
Now change one fact: suppose Hawthorne pays for the equipment in cash on December 31 instead of using financing. Keep the equipment amount constant and change only the cash-flow question. If your answer changes everywhere, you may be mixing recognition with cash movement. If it changes nowhere, you may be ignoring the changed fact.
When you review financial statement presentation common mistakes, classify each one by its first broken handoff instead of memorizing a disconnected answer.
Turn Financial Statement Presentation Common Mistakes Into Your Next FAR Review Block
Use the first broken handoff to choose the next ten-minute block. Start with a scope miss by restating the task verb and identifying the missing criterion. For an event miss, rewrite the transaction in plain language without account labels. With a calculation miss, show the carrying amount and sign. If the destination is wrong, route the same facts to the statement, cash-flow category, or note. When evidence is missing, reopen the current source and write the exact fact that would change the result.
Then retry only two exhibits with one changed date, amount, or cash condition. Record the old route, the changed fact, the new route, and the distractor you rejected. Increasing question volume before this repair can make a recurring shortcut feel like speed. A better completion standard is: I can name the event, show the linked number, route the effect, state the disclosure check, and explain why the nearest distractor fails.
Use official boundaries without turning practice into a promise
Use the AICPA CPA Exam Blueprints as the current scope resource for Areas, Groups, Topics, task statements, skill levels, references, item types, and weighting. For software and format rehearsal, consult the AICPA sample test; it is not a scored readiness determination. A retired FAR TBS can show a public multi-step format without making its facts current or reusable.
For technical conclusions, reopen the applicable FASB Accounting Standards Codification topic when the entity, date, materiality, disposal scope, tax, or effective-date facts change. This page’s examples are original simplified practice, not official CPA Exam content. Your next action is small: take one presentation question you missed, label the first broken handoff, write the correction sentence, and rerun the same route with one changed fact.