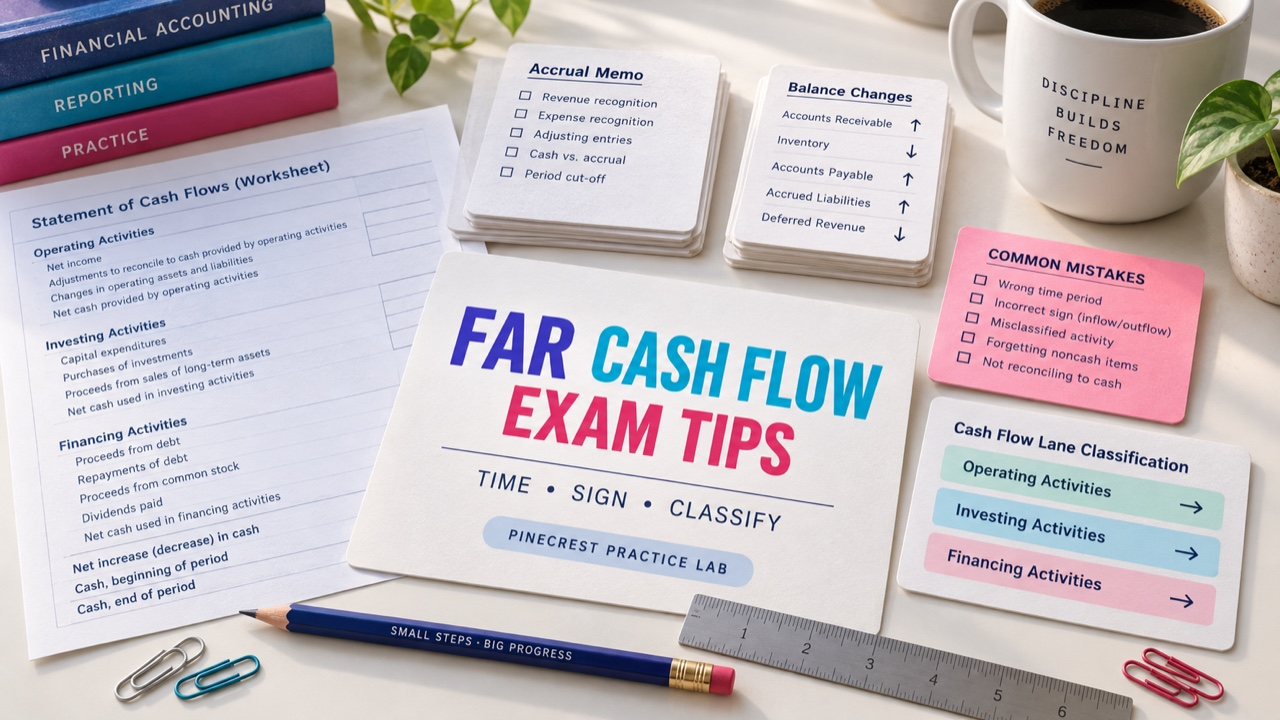

Direct answer: The most useful far cash flows and accrual accounting exam tips are a fixed five-second routine: confirm the method, name the starting amount, check whether the fact changed cash timing, write the sign in words, and classify the transaction by purpose. Skipping the first decision can still produce the wrong cash-flow answer.
Editorial review note: Written by the CPA Exam Prep study-content team and reviewed for accounting terminology, internal consistency, and learner usefulness. The Pinecrest facts, questions, answers, and retry are original editorial material, not published test content.
Use this page as a concept lesson and short practice lab. The AICPA Blueprint and current Accounting Standards Codification define the live boundary; this article turns the routine into a simplified case so you can see where an exam mistake begins. For a broader study path, visit the FAR review hub.
Far cash flows and accrual accounting exam tips: the five-second setup
Before you calculate, write five short labels in the margin: method, start, timing, sign, and lane. These labels keep the questions separate. The method tells you whether net income is a valid starting amount. The start tells you which number belongs in the first line. Timing tells you whether recognition and payment occurred together. Sign tells you how a balance movement changes cash. Lane tells you whether the transaction belongs in operating, investing, financing, or a separate noncash disclosure.
Do not begin with the largest number in the exhibit. Read the requested output first. If the prompt asks for indirect operating cash, net income is usually the starting point; a direct-method line or total change in cash needs a different setup. Put the deliverable beside the first number before calculating.

Method and deliverable for far cash flows and accrual accounting exam tips
Underline the method and the requested line. “Indirect operating cash” tells you to begin with net income and reconcile timing differences. “Cash paid to suppliers” asks a different question. “Net change in cash” requires operating, investing, and financing lanes to meet. Write the deliverable in plain words, such as indirect CFO before unlisted items, before copying any amount from the exhibit.
Tip 2 — Identify the starting amount
After the method, name the first line. Net income is not ending cash, revenue, total assets, or the opening bank balance. If the question gives a special starting amount, follow the instruction and state why. A one-line start prevents a later sign correction from hiding a wrong base.
Spot the timing trap with far cash flows and accrual accounting exam tips
Accrual accounting records an economic event when the reporting rules place it in the period. Cash reporting asks when money actually entered or left the bank. Exam prompts exploit the gap between those clocks. A customer can owe the company before paying. A supplier can be owed before the company pays. An expense can reduce net income while a payable remains outstanding. Depreciation can reduce income without a current cash payment.
The word accrued does not automatically tell you the cash-flow adjustment. Ask the payment-status question: Did the stated amount already involve cash during this period? If an unpaid accrued bonus reduced net income, the indirect bridge adds it back under the exercise assumptions. If the bonus was paid before period-end, the unpaid-accrual add-back disappears. The label stays the same; the controlling fact changes.
Keep a working-capital movement separate from a special memo. Point to the fact that controls each adjustment and mark whether it changed cash, income, or only presentation; this prevents double counting.
Tip 3 — Write “cash paid” or “cash unpaid” beside the fact
Tag each unusual fact as “cash paid,” “cash unpaid,” or “shares issued.” The tag stops you from inferring payment from a noun such as expense, purchase, or acquisition.
Tip 4 — Separate noncash value from cash consideration
A shares-for-patent exchange can have measured value while cash paid is zero. Keep it outside the cash total and record a separate noncash boundary. If the seller later receives cash, update that conclusion only.
Use a written bridge for far cash flows and accrual accounting exam tips
The safest sign rule is a sentence, not a mnemonic. For an indirect operating bridge, an increase in an operating asset generally consumes cash, while a decrease in that asset generally releases cash. An increase in an operating liability generally provides cash, while a decrease generally consumes cash. Noncash expenses such as depreciation are added back when the method and facts support that treatment. Always read the specific balance and direction instead of applying “assets down, liabilities up” to an account that does not belong in the operating adjustment.
Write the sentence beside the number: “receivable increased, so subtract”; “inventory increased, so subtract”; “payable decreased, so subtract”; “prepaid decreased, so add.” Stop at the first line whose sentence and sign disagree.
Classify the lane with far cash flows and accrual accounting exam tips
Once the operating bridge is stable, classify transactions by economic purpose. In this teaching case, equipment is investing because it acquires a long-lived resource. Borrowing and principal repayment are financing because they change debt funding. Dividends are financing because they distribute capital to owners. A shares-for-patent exchange is noncash because the stated consideration is equity rather than cash. Do not move a transaction into operating simply because depreciation later appears in net income.
Use three columns: cash amount, purpose, and presentation boundary. Build operating, investing, and financing separately, then combine only at the requested final step. A correct total with the wrong lane is still a classification error.
Original Pinecrest cash-flow trap practice set
Tested skill, assumptions, and difficulty: This original practice set tests the five-second setup, accrual timing, working-capital signs, activity lanes, and a changed-fact retry. Use the indirect method for operating cash, read every movement literally, treat the unpaid bonus as an additional noncash timing adjustment, and keep the shares-for-patent exchange outside the cash totals. Difficulty is moderate: the arithmetic is short, but each result depends on the fact that controls it. Attempt each prompt before opening its reveal.
Pinecrest Office Systems reports net income of $72,500, which includes a $3,600 bonus expense accrued but unpaid at period-end. Depreciation expense is $5,400. Accounts receivable increased by $2,700; inventory increased by $1,800; accounts payable decreased by $1,200; and prepaid insurance decreased by $600. Pinecrest paid $14,000 cash for equipment, borrowed $9,000, repaid $3,500 of principal, and paid $1,800 of dividends. It acquired a patent by issuing shares directly to the seller; Pinecrest paid no cash for the patent.
The simplified operating bridge is: $72,500 + $5,400 + $3,600 − $2,700 − $1,800 − $1,200 + $600 = $76,400. The investing lane is −$14,000. The financing lane is +$9,000 − $3,500 − $1,800 = +$3,700. The shares-for-patent exchange is a separate noncash fact because the stated cash consideration is zero.

Tasklet 1 — Find the first controlling fact
Original practice prompt: Which fact should you verify before doing any sign math, and why can the bonus change the indirect bridge even though Pinecrest has not paid it?
Reveal Tasklet 1 answer and reasoning
Answer: Confirm the indirect method and the bonus payment status. The bonus reduced net income but remained unpaid, so the stated exercise adds back $3,600. The distractor adds it because every bonus is “noncash”; payment status, not the label, controls. First review action: underline method, start, and paid/unpaid status in three short stems.
Tasklet 2 — Build the operating bridge
Original practice prompt: Using the listed facts and the indirect method, calculate Pinecrest’s operating cash before any unlisted items. Show the starting amount and every adjustment.
Reveal Tasklet 2 answer and reasoning
Answer: CFO is $76,400: $72,500 net income + $5,400 depreciation + $3,600 unpaid bonus − $2,700 receivable increase − $1,800 inventory increase − $1,200 payable decrease + $600 prepaid decrease. The distractor is $72,800, which omits the unpaid bonus; another is $78,200, which reverses the inventory sign. First review action: recalculate from a blank bridge and write one sentence beside each line.
Tasklet 3 — Explain the working-capital signs
Original practice prompt: Which listed balance movements consume cash, and which release cash relative to the indirect starting amount? Explain the direction instead of listing only plus or minus.
Reveal Tasklet 3 answer and reasoning
Answer: The receivable increase, inventory increase, and accounts-payable decrease consume cash, so subtract them. The prepaid-insurance decrease releases cash previously paid, so add it. The distractor treats every asset change or every liability change as if the account moved in the opposite direction. First review action: translate four new movements into complete cash-effect sentences.
Tasklet 4 — Classify the activity lanes
Original practice prompt: Place the $14,000 equipment payment, $9,000 borrowing, $3,500 principal repayment, and $1,800 dividend into the appropriate lanes. What is net financing cash?
Reveal Tasklet 4 answer and reasoning
Answer: Equipment is investing outflow of $14,000. Borrowing is financing inflow of $9,000; principal repayment is financing outflow of $3,500; dividends are financing outflow of $1,800. Net financing cash is +$3,700. The distractor puts equipment in operating because depreciation appears in net income. First review action: sort six transactions by purpose before calculating totals.
Tasklet 5 — Protect the noncash boundary
Original practice prompt: Pinecrest issued shares directly for a patent and paid no cash. Should the patent’s value enter investing cash, and what changes if the seller receives cash instead?
Reveal Tasklet 5 answer and reasoning
Answer: Do not enter the patent’s value as a cash investing outflow when the stated consideration is shares and cash paid is zero. If a later fact says Pinecrest paid cash to the seller, the changed consideration can create an investing outflow. The distractor confuses measured asset value with cash consideration. First review action: mark value transferred and cash paid as separate fields.
Review far cash flows and accrual accounting exam tips by first error
Review the first broken link instead of counting only the final total. Missing Tasklet 1 signals a setup or timing gap. For Tasklet 2, check the starting amount, bridge construction, or first failed sign. A Tasklet 3 miss points to balance-direction language. If Tasklet 4 fails, sort by purpose before calculating. A Tasklet 5 miss means value and cash consideration were not separated.
Use a compact record after the reveals: first broken link (method, start, timing, sign, lane, or noncash); controlling fact (the exact sentence that decided it); repair verb (underline, label, translate, classify, or compare); and next block (five to ten minutes on that same skill). This record is a study aid, not an official exam score or readiness prediction.
Retry far cash flows and accrual accounting exam tips after one changed fact
Change one fact: Pinecrest pays the $3,600 bonus before period-end instead of leaving it unpaid. Keep net income, depreciation, receivables, inventory, payables, prepaids, equipment, debt, dividends, and the shares-for-patent consideration fixed. The only linked change is the unpaid-bonus add-back.
Under the changed fact, the operating bridge becomes $72,500 + $5,400 − $2,700 − $1,800 − $1,200 + $600 = $72,800. The investing lane remains −$14,000, the financing lane remains +$3,700, and the patent exchange remains noncash. Do not reverse the receivable sign or move equipment into operating just because the CFO total changed.
The point of the retry is controlled transfer. Mark the changed sentence, name the affected line, list the unchanged facts, and state the new total. If more than the bonus line changes, schedule a timing-status drill.
Far cash flows and accrual accounting exam tips: FAQ
Should I memorize one cash-flow sign rule?
Memorize the direction as a starting aid, then write the sentence for the specific account and movement. An operating-asset increase usually consumes cash, but the prompt’s method, account type, and facts still control the conclusion.
Does every accrued expense get added back?
No. Check whether the amount reduced income without a same-period cash payment and whether the requested method supports the adjustment. A paid expense does not receive an unpaid-accrual add-back simply because the word “accrued” appears.
Why is equipment not operating when depreciation is added back?
Depreciation is a noncash expense inside the simplified operating reconciliation, while the cash purchase of equipment serves a long-lived-asset purpose. The same fact pattern can therefore create an operating adjustment and a separate investing outflow.
Can a shares-for-patent exchange be a cash outflow?
Not when the stated consideration is shares and cash paid is zero. Separate the value transferred from cash consideration, then follow the applicable current presentation or disclosure guidance.
Sources and refresh note
Current tested-content boundary: AICPA CPA Exam Blueprints. Format and software boundary: AICPA sample tests. Technical refresh: FASB Accounting Standards Codification. Candidate-process routing: NASBA CPA Exam FAQ. The team checked these pages September 23, 2026. Reopen current guidance when the entity, method, reporting date, activity presentation, noncash disclosure, or candidate-process detail changes. The Pinecrest facts, questions, answers, reasoning, and retry are original editorial study content.