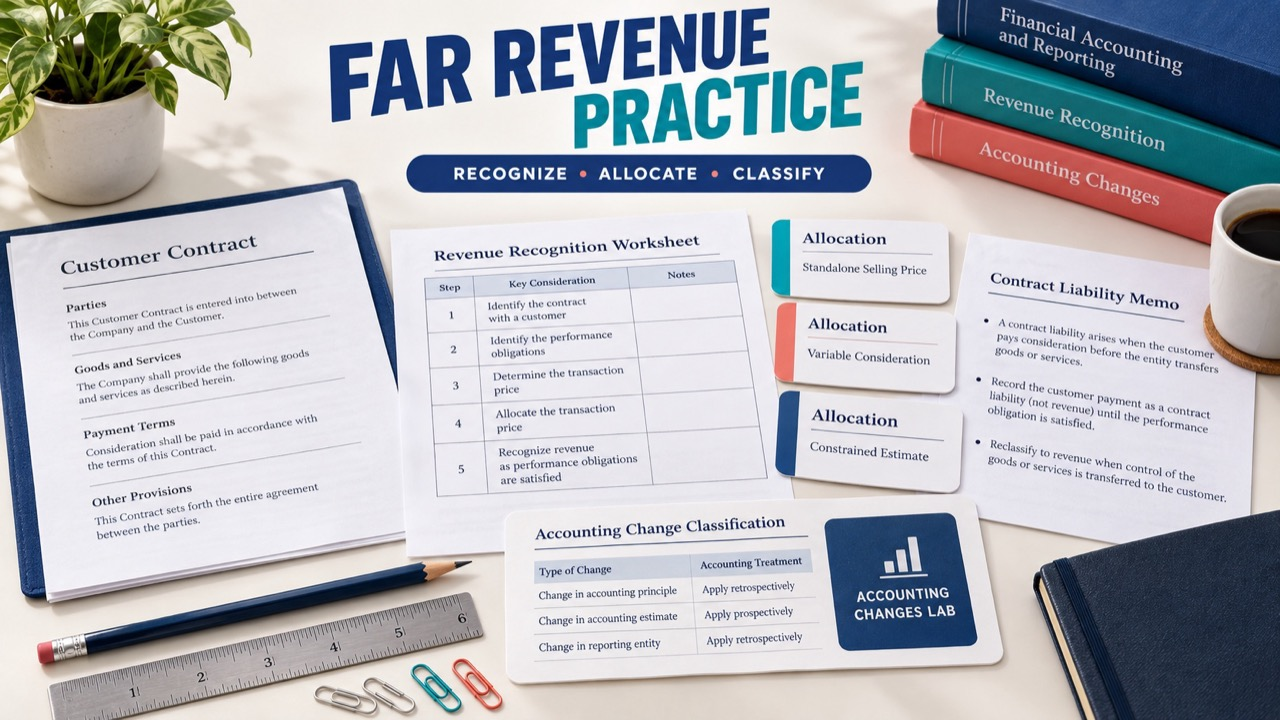

Direct answer: The safest way to use revenue recognition practice questions is to write the controlling fact before the number: identify the contract, separate the performance obligation, set the transaction price, allocate it, and recognize revenue only after the customer receives the promised good or service. Then keep a second lane for accounting changes: ask whether the fact is a new estimate, a change in principle, or an error.
Editorial review note: Written by the CPA Exam Prep study-content team and reviewed for terminology, arithmetic, internal consistency, and learner usefulness. The cases, amounts, questions, answers, distractors, and retry are original editorial practice, not released exam content.
These far revenue recognition and accounting changes practice questions use simplified assumptions so the reasoning stays visible. The AICPA Blueprint and current FASB literature define the live boundary; this page gives you a compact lab and sends entity-specific questions back to current authoritative guidance. For broader study routing, visit the FAR review hub.
Build revenue recognition practice questions around a five-step contract map
Start every contract question with a written map instead of jumping to a familiar answer. The five steps below are a study routine, not a substitute for reading the applicable current Codification. The point is to keep a contract liability, an allocated price, and earned revenue from collapsing into one number.
- Identify the contract: confirm that the parties have approved the arrangement, rights and payment terms are identifiable, the arrangement has commercial substance, and collection is probable under the exercise assumptions.
- Identify the performance obligation: ask what distinct good or service the customer receives. The entity can satisfy a stand-ready service over time; the seller may transfer a delivered machine at a point in time under the stated facts.
- Determine the transaction price: separate fixed consideration from a variable amount or financing feature. Do not invent a refund, bonus, or constraint when the question gives none.
- Allocate the price: use relative standalone selling prices when the exercise gives them. Keep the calculation visible so an allocation error does not masquerade as a timing error.
- Recognize revenue: connect recognition to transfer. Cash received before the entity delivers the service can create a contract liability; it is not automatically current-period revenue.

With a service arrangement, write three lines: cash collected, service delivered, and contract liability remaining. For a bundle, add a fourth line for standalone selling prices and an allocation ratio. On every line, add the phrase because the customer received. That phrase forces you to explain transfer instead of treating billing as recognition.
Separate cash, contract liability, and earned revenue
Suppose a customer prepays for a year of support. The entry on receipt can increase cash and a contract liability. As the customer receives support, the entity releases part of that liability to revenue. The entity may collect the same cash while earned revenue and the remaining liability move each reporting period. The question’s service period and reporting date control the amount.
Make allocation a ratio before making it a journal entry
When a machine and maintenance are sold together, add the standalone selling prices first. Divide each standalone price by the total, then multiply by the transaction price. Only after that allocation should you ask when the customer receives each performance obligation. A correct total price with the wrong allocation is still a wrong answer.
Keep revenue recognition practice questions and accounting changes in separate lanes
Revenue questions and accounting-change questions can appear beside each other, but they are not the same decision. A change in estimate uses new information about an amount or timing and generally affects the current and future periods under the stated assumptions. A change in accounting principle involves changing from one acceptable principle to another and may require a prescribed transition or retrospective treatment. An error means the prior accounting omitted information available when the entity prepared the statements; a material error can require the entity to correct prior-period information. Always follow the current guidance and any transition rule provided.
Use a four-word test before choosing a treatment: new information, new principle, or missed information? “New information” points toward estimate. “New principle” points toward principle-change guidance. “Missed information” points toward error analysis. The label alone is not enough; the reason for the change controls the lane.
Do not restate a new estimate by reflex
If updated experience changes a useful-life estimate, leave prior depreciation based on the information available then and recalculate the remaining carrying amount prospectively. If the original amount was wrong because the entity ignored an available invoice or schedule, the question is testing error correction, not estimation. Write the reason in a margin note before calculating.
Do not call every method switch an error
A voluntary move between acceptable principles is not automatically a mistake. Ask whether the entity changed a principle, received new information, or discovered that prior reporting omitted or misstated available information. Then read the applicable transition and disclosure requirements instead of importing a one-size-fits-all rule.
Original revenue recognition practice questions and accounting-change practice set
Tested skill, assumptions, and difficulty: This original set tests service timing, relative allocation, estimate classification, and principle-versus-error reasoning. Assume a calendar-year entity, simplified facts, no unusual financing component, no variable consideration unless stated, and current guidance as the final authority. Difficulty is moderate: the arithmetic is short, but each answer depends on a controlling fact. Attempt each tasklet before opening its reveal.
The four cases are intentionally different. Metroline tests whether a learner mistakes advance cash for revenue. Brightwell tests whether a learner allocates a bundle before applying recognition timing. Maple tests whether a learner applies new useful-life information prospectively. Redwood tests whether a learner separates a method switch from omitted available information.

Tasklet 1 — Recognize the service, not the deposit
Original practice prompt: Metroline Data receives $18,000 on January 1 for twelve months of stand-ready support. Assume the entity satisfies the service evenly and three months have passed by March 31. How much revenue and contract liability should the simplified case show at March 31?
Reveal Tasklet 1 answer and reasoning
Answer: Revenue is $4,500 ($18,000 ÷ 12 × 3), and the remaining contract liability is $13,500. The distractor recognizes all $18,000 because the customer paid cash; that confuses billing or collection with transfer. First review action: write cash collected, months delivered, revenue earned, and liability remaining as four separate fields.
Tasklet 2 — Allocate before recognizing the bundle
Original practice prompt: Brightwell sells a machine and twelve months of maintenance for $132,000. Their standalone selling prices are $120,000 for the machine and $30,000 for maintenance. The seller transfers the machine immediately and delivers three months of maintenance. What amount should the allocation assign to the machine, what maintenance revenue should the entity earn, and what liability should remain?
Reveal Tasklet 2 answer and reasoning
Answer: Total standalone selling price is $150,000. The machine receives 120/150 of the transaction price, or $105,600; maintenance receives 30/150, or $26,400. Three months of maintenance earns $6,600, leaving $19,800 for the remaining nine months. The distractor uses the invoice split or recognizes the full $132,000 at delivery. First review action: repeat the allocation ratio before touching the service calendar.
Tasklet 3 — Classify the useful-life update
Original practice prompt: Maple Tools has a machine with a $60,000 carrying amount at the start of Year 3 and no residual value. At that date, new production evidence changes the remaining useful-life estimate from six years to four years. How much should the entity record for Year 3 depreciation, and should it restate prior periods?
Reveal Tasklet 3 answer and reasoning
Answer: Year 3 depreciation is $15,000 ($60,000 ÷ 4), and prior periods are not restated merely because the estimate changed. The controlling fact is new information about the remaining life. The distractor keeps the old six-year amount or treats the estimate as a prior-period error. First review action: write “new information” beside the fact, then recalculate only the remaining period.
Tasklet 4 — Separate principle change from error
Original practice prompt: Redwood Retail moves from FIFO to weighted-average inventory costing, with both methods acceptable and no special transition instruction stated. In a separate fact, it discovers that the entity omitted a prior-year invoice from inventory records even though it had the invoice before issuance. How should the learner classify the two facts for further analysis?
Reveal Tasklet 4 answer and reasoning
Answer: The voluntary move between acceptable methods is a change in accounting principle; follow the applicable transition and disclosure guidance rather than calling it an error. The omitted available invoice is a prior-period error; if material, analyze correction and comparative-period effects under current guidance. The distractor calls both facts estimates because both change a number. First review action: label each fact “new principle” or “missed information” before considering presentation.
Review revenue recognition practice questions by the first broken decision
Do not use a total score as the only feedback. Find the first broken decision. A Tasklet 1 miss signals a timing or contract-liability problem. For Tasklet 2, a miss signals an allocation-ratio problem. With Tasklet 3, a miss signals an estimate-versus-error classification problem. In Tasklet 4, a miss signals a reason-for-change problem. The next study block should repair that first link, not repeat every question at random.
After the reveals, record the tasklet, confidence, controlling fact, first broken decision, and repair verb (separate, allocate, classify, or restate). This is a local study aid, not an official score or readiness prediction.
Retry revenue recognition practice questions after one changed fact
Change only the Metroline reporting date: assume the entity delivered six months of the twelve-month support service by June 30 instead of three months by March 31. Keep the $18,000 advance payment, stand-ready promise, and even service pattern fixed. Which amounts change, and which conclusion stays the same?
Revenue becomes $9,000 ($18,000 ÷ 12 × 6), and the remaining contract liability becomes $9,000. The conclusion that cash collected is not automatically revenue stays unchanged. Do not change the allocation rule, invent a refund, or treat the remaining liability as a loss. The retry is useful only if one fact changes and every fixed fact remains visible.
Revenue recognition practice questions: FAQ
Is cash collection the same as revenue?
No. Customers can pay cash before the promised good or service reaches them. Under the simplified service case, advance cash first supports a contract liability, and the entity releases that liability to revenue as the customer receives service.
Do I allocate a bundle after recognizing the first item?
Allocate the transaction price using the stated standalone selling prices before applying each performance obligation’s timing. Allocation and recognition are linked but separate steps.
Does a new depreciation estimate restate prior years?
Not merely because it is an estimate change. Under the simplified facts, use the new information for the remaining carrying amount and follow the applicable current guidance for the entity and reporting facts.
Is every method change an error?
No. Ask why the change occurred. A move between acceptable principles, a new estimate, and omitted available information belong to different analysis lanes.
Revenue recognition practice questions: sources and refresh note
Current tested-content boundary: AICPA CPA Exam Blueprints. Format boundary: AICPA sample tests. Revenue framework background: FASB Revenue Recognition project summary. Technical refresh: FASB Accounting Standards Codification. Candidate-process routing: NASBA CPA Exam FAQ. The team checked these pages September 23, 2026. Reopen current guidance when the contract, entity, transition method, reporting date, or accounting-change fact changes. The cases, formulas, questions, answers, reasoning, and retry are original editorial study content.