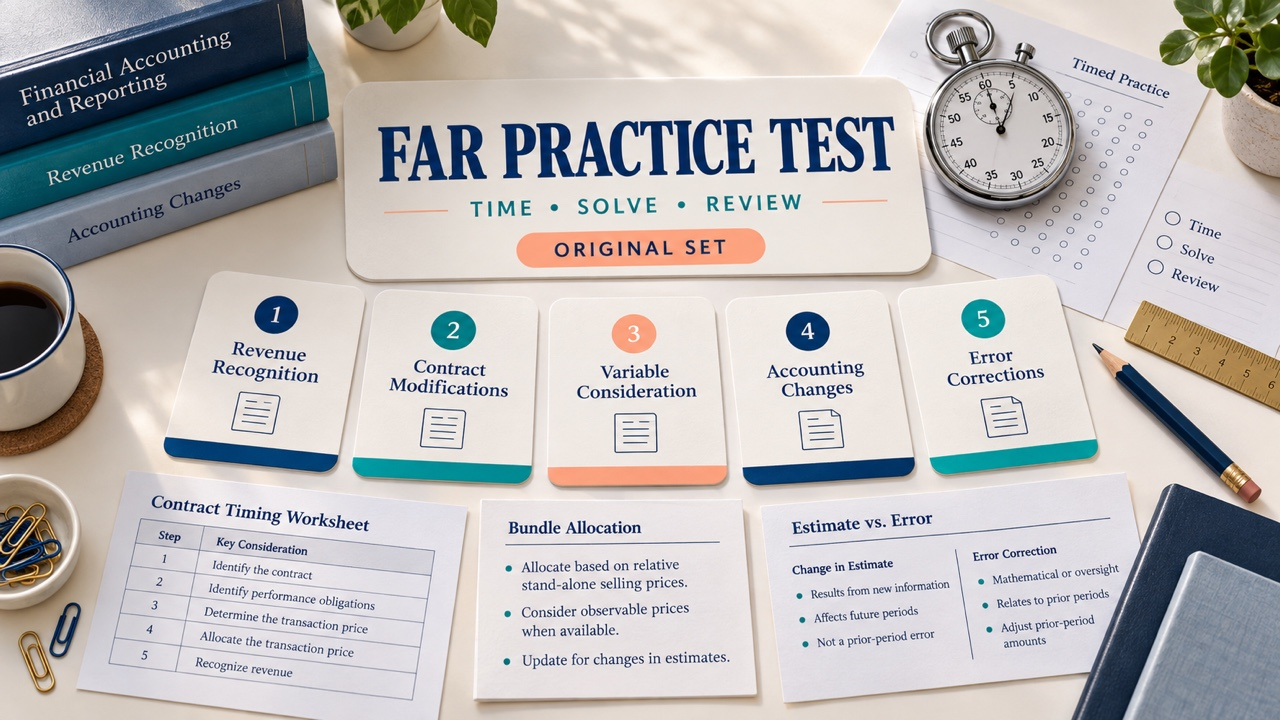

Direct answer: Overall, treat this revenue recognition practice test as a timed decision exercise, not a race to a number. Read the ask, mark the controlling fact, select the accounting lane, calculate once, and reserve a final minute to explain why the nearest distractor fails. The five original items below mix contract timing, bundle allocation, estimates, principles, and errors.
The test uses simplified facts so you can isolate the decision. However, cash collection is not automatically revenue, a bundle must be allocated before each promise is timed, new information is not the same as an error, and an acceptable method switch has a different starting classification from an omitted invoice. Use the current AICPA Blueprint and FASB literature for live boundaries; the stems, options, scoring rubric, and retry are original study practice. For broader routing, visit the FAR review hub.
Editorial review note: Written by the CPA Exam Prep study-content team and checked for terminology, arithmetic, internal consistency, and learner usefulness. This is original editorial practice, not released exam content or an exam-readiness prediction.
Use a timed route for the revenue recognition practice test
First, set a practical time box before you look at the answer choices. Give yourself five minutes per item, then keep the final five minutes for review. If a calculation takes longer than two minutes, write the controlling fact and move on; a clean classification is more useful than a half-finished calculation.
- Read the ask: identify whether the item requests revenue, a liability, an allocated price, depreciation, or a classification.
- Mark the trigger: underline the delivered months, transfer point, standalone selling prices, new evidence, or availability date.
- Write one formula or label: use consideration ÷ service months × months delivered, relative allocation, or estimate/principle/error.
- Choose before explaining: record one answer letter and one sentence explaining the controlling fact.
- Flag the next review: classify the miss as timing, allocation, estimate, principle, or error.

Revenue recognition practice test: set the clock before reading
Do not let a long stem create false difficulty. Read the requested output, circle the date or period, and identify whether the customer has received the promised good or service. For example, a prepayment item usually tests the difference between cash and performance; an equipment-plus-training item usually tests allocation before timing.
Protect the fact pattern from familiar-looking distractors
Next, ask what fact the attractive wrong answer ignores. A full cash receipt may be a real amount but still be unearned. An invoice split may be printed on the document but may not be the relative allocation. A retrospective restatement may sound cautious but may not fit a change caused by new information. Write the ignored fact beside the distractor.
Reserve review time for accounting changes
Meanwhile, the last two lanes begin with the reason for change. A revised estimate starts with new evidence about an amount or timing. A principle-change lane starts with a move between acceptable methods. An error lane starts with information that was available but omitted or misstated. For this reason, label the lane before choosing the treatment.
Original FAR revenue recognition practice test: five timed items
Tested skill, assumptions, and difficulty: This original practice set tests service timing, relative allocation, estimate classification, acceptable-principle changes, and available-fact errors. Assume a calendar-year entity, simplified facts, no unusual financing component, no variable consideration unless a stem states otherwise, and current guidance as the final authority. Difficulty is moderate: each item has short arithmetic or classification, but the score is useful only when paired with an error label.

Item 1 — Even service and contract liability
Original practice item: Harbor Cloud receives $48,000 on January 1 for twelve months of stand-ready support. Five months are delivered evenly by May 31. What revenue and contract liability should the simplified case show at May 31?
- $48,000 revenue and $0 contract liability
- $20,000 revenue and $28,000 contract liability
- $28,000 revenue and $20,000 contract liability
- $4,000 revenue and $44,000 contract liability
Reveal Item 1 answer and reasoning
Correct answer: B. Revenue is $48,000 ÷ 12 × 5 = $20,000, leaving $28,000 for the remaining seven months. Option A treats cash as revenue, option C reverses delivered and undelivered months, and option D divides the annual amount by twelve without applying the five months. Review action: Therefore, write “months delivered” beside the formula before reading the options again.
Item 2 — Relative allocation and training timing
Original practice item: Meridian sells equipment and six months of training for $300,000. Standalone selling prices are $210,000 for equipment and $90,000 for training. Equipment transfers immediately, and four months of training are delivered. What equipment allocation and training revenue are earned so far?
- $210,000 equipment and $60,000 training revenue
- $300,000 equipment and $0 training revenue
- $210,000 equipment and $90,000 training revenue
- $150,000 equipment and $60,000 training revenue
Reveal Item 2 answer and reasoning
Correct answer: A. The standalone prices total $300,000, so equipment receives $210,000. Training revenue is $90,000 ÷ 6 × 4 = $60,000. Option B recognizes the full price at equipment transfer, option C recognizes all training at once, and option D invents an equal split. Review action: As a result, allocate first, then apply the training period.
Item 3 — Revised estimate
Original practice item: Pinecrest has a machine with a $64,000 carrying amount and no residual value at the start of Year 4. New production evidence changes the remaining useful life to two and one-half years. What Year 4 depreciation and prior-period treatment best fit the simplified facts?
- $12,800 depreciation with retrospective restatement
- $25,600 depreciation with prospective application
- $25,600 depreciation with retrospective restatement
- $64,000 depreciation with prospective application
Reveal Item 3 answer and reasoning
Correct answer: B. The revised estimate uses new production evidence, so the remaining amount is $64,000 ÷ 2.5 = $25,600 for Year 4 under the simplified facts, applied prospectively. Option A uses the old five-year amount, option C treats an estimate as an error, and option D writes off the whole carrying amount without an impairment fact. Review action: In practice, write “new evidence” before choosing a transition treatment.
Item 4 — Acceptable method change
Original practice item: Ridgeway changes from weighted-average inventory costing to FIFO. Both methods are acceptable under the stated facts, and the stem supplies no special transition instruction. Which classification should you investigate first?
- Change in accounting principle
- Change in estimate
- Prior-period error
- Revenue contract liability
Reveal Item 4 answer and reasoning
Correct answer: A. The entity moved between acceptable accounting principles, so begin with change-in-principle guidance and then check the applicable transition and disclosure requirements. Option B needs new information about an amount, option C needs an available fact that was omitted or misstated, and option D changes the topic. Review action: Similarly, label “acceptable method switch” before thinking about presentation.
Item 5 — Available invoice and error analysis
Original practice item: Seaside finds that a prior-year inventory invoice was omitted, although the accounting team had the invoice before issuing the financial statements. Which lane should you investigate first?
- New estimate based on current information
- Change in accounting principle
- Prior-period error, followed by materiality and correction analysis
- Revenue recognized over the remaining service period
Reveal Item 5 answer and reasoning
Correct answer: C. The invoice was available before issuance but was omitted, so the facts point toward a prior-period error. Materiality and correction effects still require current guidance and the entity’s facts. Option A ignores when the information was available, option B describes a different reason for change, and option D imports a contract concept that the stem does not contain. Review action: Finally, circle “available before issuance” before considering the correction.
Score the revenue recognition practice test and label the miss
Then, use the score only as a routing device. Five correct answers means review the hardest distractor and then move to mixed practice. Four correct answers means revisit the one broken lane before adding new facts. Three correct answers means repeat the weakest category with untimed questions. Two or fewer correct answers means return to the route, especially the difference between timing, allocation, estimate, principle, and error.
For each miss, record the item number, confidence before the reveal, controlling fact, chosen distractor, and repair verb: separate, allocate, estimate, classify, or correct. This changes the next study action; it is not an official score or readiness prediction.
Retry the revenue recognition practice test after one changed fact
For the retry, change only Harbor Cloud’s reporting date: assume nine months of the twelve-month support service have been delivered instead of five months. Keep the $48,000 payment, stand-ready promise, and even service pattern fixed. What result follows?
As a result, revenue becomes $36,000 ($48,000 ÷ 12 × 9), and the remaining contract liability becomes $12,000. The unchanged boundary is that the advance payment was not automatically earned on January 1. Do not change the allocation rule, invent a refund, or move the remaining liability into expense.
Revenue recognition practice test: FAQ
How should I time the five items?
Finally, use five minutes per item and reserve the final five minutes for review. If one calculation stalls, mark the controlling fact, select a provisional option, and return after the other items.
What should I write beside a prepayment item?
Also, write cash received on one line and service months delivered on another. The earned portion follows the transfer pattern; the remaining portion stays a contract liability under the simplified facts.
What is the fastest bundle check?
Then, compare the transaction price with the standalone selling prices, allocate first, and only then apply the timing for equipment or training.
How do I distinguish an estimate from an error?
In contrast, new evidence about a remaining amount or life points toward an estimate. Information that was already available but omitted or misstated points toward error analysis.
Revenue recognition practice test: sources and refresh note
Current tested-content boundary: AICPA CPA Exam Blueprints. Format boundary: AICPA sample tests. Revenue framework background: FASB Revenue Recognition project summary. Technical refresh: FASB Accounting Standards Codification. Candidate-process routing: NASBA CPA Exam FAQ. The team checked these pages September 23, 2026. Reopen current guidance when the contract, entity, reporting date, or accounting-change fact changes. The stems, answer choices, calculations, rationales, distractors, scoring rubric, and retry are original editorial study content.