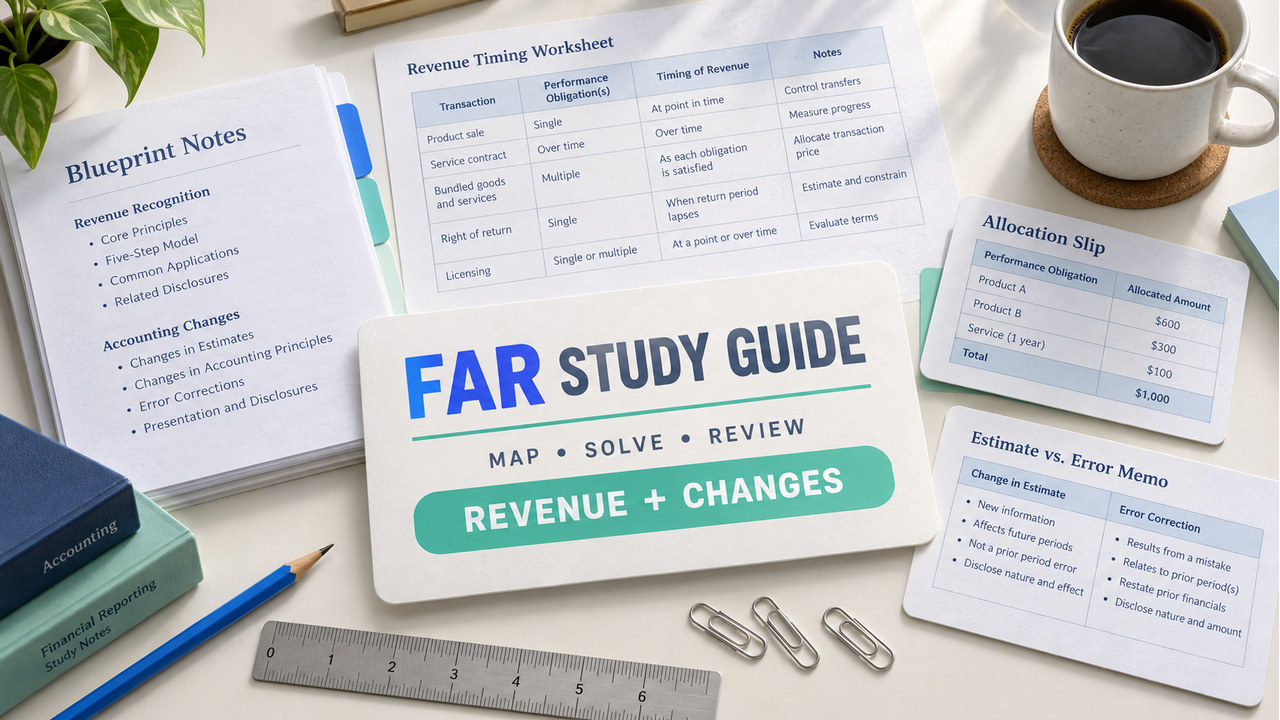

Direct answer: Use this revenue recognition study guide as a decision map, not as a paragraph to memorize. First identify the output the question asks for. Next, separate contract timing and allocation from the reason an accounting number changed. Then calculate or classify the smallest controlling fact, check the applicable current guidance, and turn the result into one specific review block.
That order matters because a prepayment, a bundle, a revised estimate, an acceptable method switch, and an omitted available fact can look similar when a FAR stem is long. The AICPA Blueprint and current FASB literature define the live boundary. The map, examples, checkpoints, and review routine below are original editorial study material, not exam-issued or score-predictive content. For a broad section route, visit the FAR review hub.
Editorial review note: Written by the CPA Exam Prep study-content team and checked for terminology, arithmetic, internal consistency, and learner usefulness. A candidate should reopen the current Blueprint and Codification when a fact pattern, effective date, or transition rule changes.
Use this revenue recognition study guide as a decision map
Before reading the answer choices, write the requested output in the margin. Is the stem asking for revenue, a contract liability, an allocated transaction price, depreciation, a classification, or a transition treatment? Once that output is visible, mark the one fact that controls it. The following five-pass routine keeps the topic from becoming a vocabulary race.
- Name the output: write one noun such as revenue, liability, allocation, estimate, principle, or error.
- Circle the trigger: mark months delivered, the transfer point, standalone selling prices, new evidence, an acceptable method, or when information was available.
- Choose the lane: keep cash-versus-performance and allocation-versus-timing separate from estimate, principle, and error classification.
- Run one calculation or rule: use only the numbers and facts the stem gives; do not invent a refund, impairment, discount, or transition result.
- Explain the nearest distractor: state which controlling fact the tempting wrong answer ignores, then assign the next review action.

Revenue recognition study guide: start with the question’s requested output
For example, “How much revenue?” is not the same task as “Which accounting-change lane?” A correct number can still answer the wrong question. Therefore, underline the verb and the object before calculating. If the stem asks what to investigate first, classify the reason for change before discussing presentation or disclosure.
Revenue recognition study guide: keep the fact pattern visible
Short notes are more reliable than a mental summary. Write the payment date, service months delivered, transfer point, standalone prices, evidence date, and information-availability date in separate lines. In addition, write “simplified facts” beside any practice assumption so you do not carry it into a real client conclusion.
Revenue recognition study guide: use a source check as the final pass
The study guide can route your reasoning, but it cannot replace authoritative research. Use the AICPA Blueprint for tested-content boundaries and use current FASB literature for the accounting conclusion. If the item turns on a transition requirement or a fact omitted from this guide, stop and verify the current Codification rather than relying on a remembered shortcut.
Revenue recognition study guide: map the FAR blueprint
The live Blueprint is the scope anchor for a study plan. This page uses it as a boundary rather than pretending that one article reproduces every task statement. The practical map has two connected branches: revenue recognition asks how a contract promise is measured and timed, while accounting-change questions ask why a reported amount or method changed. The branches meet when a stem supplies a new fact that changes an estimate or reveals an earlier omission.
Branch one: contract promises, price, and timing
Start by asking what the customer is promised and when that promise is satisfied under the stated facts. A cash receipt may precede performance. A bundle may contain more than one promise. An amount may be allocated before each promise is timed. Consequently, a full invoice amount is not automatically the answer merely because it is easy to spot.
Branch two: estimates, principles, and errors
Start by asking why the number changed. New evidence about a remaining useful life or amount usually sends the question toward an estimate lane. A voluntary move between acceptable methods sends it toward a principle-change lane, after which the applicable transition guidance still needs to be checked. Information that was already available but was omitted or misstated sends it toward error analysis.
The boundary that prevents category mistakes
A timing question can contain a date, but that does not make it an accounting-change question. Similarly, an accounting-change question can contain an amount, but the amount alone does not tell you whether the issue is an estimate or an error. Label the reason first; only then choose the calculation, correction, or transition path.
Revenue recognition study guide: timing and allocation
Under simplified study facts, use the transfer pattern supplied by the stem. If support is delivered evenly over a service period, divide the consideration by the total months and multiply by the months delivered. The undelivered portion remains separate from earned revenue. If equipment and training share one transaction price, allocate before applying immediate or over-time timing.
Worked example: a stand-ready service
Assume Northstar receives $72,000 on January 1 for twelve months of stand-ready support. Eight months are delivered evenly by August 31. The simplified earned amount is $72,000 ÷ 12 × 8 = $48,000. The remaining $24,000 is the undelivered portion. The key fact is not the payment date; it is the service period delivered.
Worked example: allocate before timing
Assume Cedar sells equipment and three months of training for $240,000. The stated standalone selling prices are $180,000 for equipment and $60,000 for training. Equipment transfers immediately, and two months of training are delivered. First, assign $180,000 to equipment and $60,000 to training. Then, recognize $40,000 of training revenue for two delivered months. A distractor that recognizes all $240,000 at the equipment transfer skips the allocation and timing split.
Revenue recognition study guide: accounting changes
The accounting-change branch is a classification exercise before it is a presentation exercise. A study answer should state the trigger, explain why the nearest alternative fails, and mark the follow-up research. The labels below are a routing aid; entity-specific materiality, correction, disclosure, and transition conclusions still require current authoritative guidance.

New evidence points toward an estimate
Suppose a machine has a $90,000 carrying amount and no residual value at the beginning of Year 5. New production evidence changes the remaining useful life to four years. Under the simplified facts, the next-period depreciation is $90,000 ÷ 4 = $22,500. The teaching point is the source of the change: new evidence about the remaining estimate, not a prior-period omission. The next action is to review prospective estimate treatment under current guidance.
An acceptable method switch requires a transition check
Suppose an entity moves from weighted-average inventory costing to FIFO and both methods are acceptable under the stated facts. Begin by labeling the issue a potential change in accounting principle. Do not write a universal transition answer from memory. Instead, check the applicable current guidance, effective date, permitted alternatives, and disclosure requirements. The useful review verb is classify, followed by check.
An available omitted fact points toward error analysis
Suppose an inventory invoice was in the accounting team’s possession before the financial statements were issued but was omitted. That availability fact points first toward prior-period error analysis. Next, research materiality, correction, comparative-period, and disclosure effects for the entity’s facts. A new-estimate answer is the nearest distractor because it ignores when the information was available.
Build a one-week FAR review plan from the map
A study guide becomes useful when it changes the next session. Use the following sequence for one week, then repeat only the weakest lane. Keep the score private and diagnostic; it is not an official exam score or a readiness forecast.
- Day 1 — Scope: read the current Blueprint boundary and write the two branches: contract timing/allocation and accounting-change classification.
- Day 2 — Timing: complete three short prepayment or stand-ready-service examples and label payment, delivered months, earned amount, and remaining liability.
- Day 3 — Allocation: solve three bundle examples. Allocate first, then time each promise. Mark any answer that uses invoice lines without a relative-allocation reason.
- Day 4 — Changes: sort new evidence, acceptable method switches, and available omitted facts into estimate, principle, and error lanes.
- Day 5 — Mixed review: complete one timing item and one accounting-change item without notes, then explain the nearest distractor in one sentence.
- Day 6 — Repair: repeat only the first broken lane with a changed fact. Keep all other facts fixed so you can see what actually changed.
- Day 7 — Refresh: review the current source boundary, update your error log, and choose the next mixed set based on the weakest repair verb.
Revenue recognition study guide: self-check
Try each checkpoint before opening the explanation. These are original editorial checks designed to expose category mistakes, not official questions.
Checkpoint 1 — What remains after a prepayment?
Bluebird receives $60,000 for ten months of even support. Three months are delivered. What simplified amount is earned, and what amount remains undelivered?
- $60,000 earned and $0 remaining
- $18,000 earned and $42,000 remaining
- $42,000 earned and $18,000 remaining
- $6,000 earned and $54,000 remaining
Reveal Checkpoint 1 reasoning
Correct answer: B. $60,000 ÷ 10 × 3 = $18,000 earned, leaving $42,000 undelivered. The payment date does not replace the service-transfer fact. Next action: repeat two even-service timing items if you chose A or C.
Checkpoint 2 — What comes before timing in a bundle?
Atlas sells equipment and training for $200,000. Standalone prices are $140,000 and $60,000; two of four training months are delivered. What should you do first?
- Recognize the full invoice when equipment transfers
- Split the price using the printed invoice lines without checking the standalone prices
- Allocate the transaction price, then apply each promise’s transfer pattern
- Wait until all training is complete before recognizing equipment
Reveal Checkpoint 2 reasoning
Correct answer: C. Allocation comes first; then the equipment transfer and two months of training are timed. Next action: practice bundle allocation if you chose A, B, or D.
Checkpoint 3 — Which change lane fits available information?
An invoice was available before issuance but was omitted from the prior-year records. Which lane should you investigate first?
- New estimate
- Change in accounting principle
- Prior-period error analysis
- Revenue recognized over future service months
Reveal Checkpoint 3 reasoning
Correct answer: C. Availability before issuance is the controlling fact, so begin with error analysis and then check materiality and correction guidance. Next action: sort three “new evidence” and “available fact” examples if you chose A or B.
Route a missed answer to the next review
For each miss, record the checkpoint number, your confidence before revealing the answer, the fact you ignored, the distractor you chose, and the repair verb. Use separate for cash and performance, allocate for a bundle, estimate for new evidence, classify for a method switch, and correct for an available omitted fact. Then schedule one short block for the first broken verb instead of rereading the entire chapter.
Revenue recognition study guide: FAQ
Is cash received the same as revenue?
No. Under a simplified stand-ready-service pattern, separate the payment from the portion of service delivered. The contract facts and transfer pattern control the earned amount.
Why allocate before timing?
When one transaction price covers more than one promise, allocation identifies the amount assigned to each component. Only then can each component’s transfer pattern be applied.
Does every method change have the same treatment?
No. First classify why the method or amount changed. A move between acceptable principles requires a transition check; new information may revise an estimate; an available omitted fact points toward error analysis.
Can this guide replace current accounting research?
No. Use the article to organize a study session, then reopen the current AICPA Blueprint and FASB Codification when the real fact pattern includes a transition, effective-date, contract, or entity-specific issue.
Revenue recognition study guide: sources and refresh note
Current tested-content boundary: AICPA CPA Exam Blueprints. Revenue framework background: FASB Revenue Recognition project summary. Technical refresh: FASB Accounting Standards Codification. Candidate-process routing: NASBA CPA Exam FAQ. The team checked these pages September 23, 2026. Reopen current guidance when the contract, entity, reporting date, accounting method, or transition fact changes. The examples, checkpoints, answer choices, rationales, study plan, and review prompts are original editorial study content.