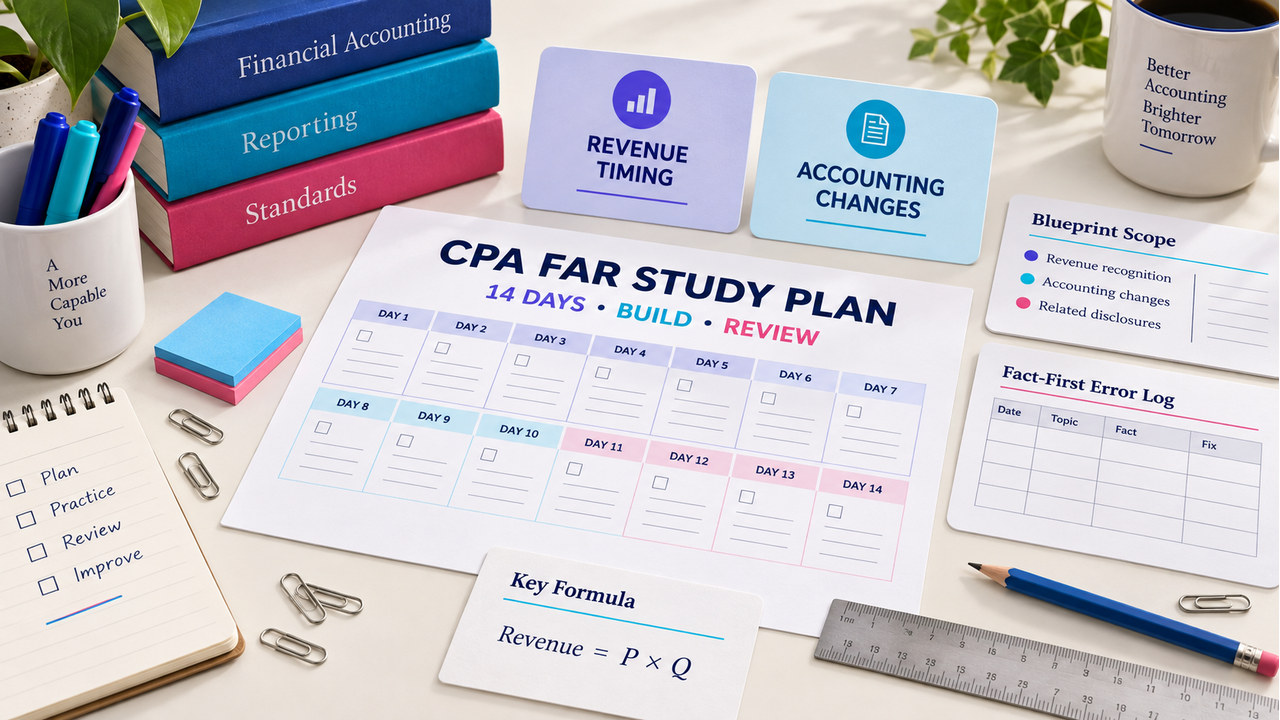

Direct answer: To build a revenue recognition study plan for CPA FAR topics efficiently, use a two-lane method: first separate contract timing and allocation from estimate, principle, and error classification; then let each missed controlling fact choose the next review block. Without that lane split, a calendar creates busywork. Likewise, a lane split without a calendar creates rereading. Together, the method connects both.
The schedule below is a practical study method, not an exam prediction or an official score tool. In practice, it uses the current AICPA Blueprint as a scope check and current FASB literature as the research boundary. The examples, mini-cases, answer choices, and review prompts are original editorial study material. For a broad section route, visit the FAR review hub.
Editorial review note: Written by the CPA Exam Prep study-content team and checked for terminology, arithmetic, internal consistency, and learner usefulness. Reopen the current Blueprint and Codification when a fact pattern, effective date, method, or transition rule changes.
How to study revenue recognition accounting changes CPA FAR topics
Begin every session with one visible target. For example, do not write “study FAR” on the page. Instead, write “separate payment from performance,” “allocate a bundle,” “classify a new estimate,” “check a principle transition,” or “route an available omission.” The verb tells you what to practice and makes the result measurable.
- Set the target: name the output or decision the stem demands.
- Split the lanes: put timing and allocation on one side; estimate, principle, and error on the other.
- Work one fact: change only the controlling fact in a short original mini-case.
- Log the miss: record the fact you ignored and the nearest distractor you chose.
- Book the retry: schedule a changed-fact question within the next two study sessions.
Revenue recognition study plan: define the output
Before looking at choices, underline what the question asks for: earned revenue, a remaining contract liability, an allocated amount, depreciation, classification, correction, or a transition step. Although a long stem can contain several dates and amounts, only one output may control the answer. Therefore, writing the output first prevents you from calculating a true number for the wrong task.
Revenue recognition study plan: keep the two lanes separate
Revenue timing asks when a promise is satisfied. By contrast, allocation asks how one transaction price is assigned to more than one promise. Accounting-change questions ask why a reported amount or method changed. These can appear together, but the cause still matters. A revised useful life is not automatically an error; an invoice already available before issuance is not automatically a new estimate. Accordingly, label the lane before you choose the rule.
Revenue recognition study plan: use a fact card
Write five short fields: payment date, performance or transfer date, standalone prices, new-evidence date, and information-availability date. Next, add “simplified facts” beside any assumption supplied only for practice. This small card gives you something concrete to compare when the next question changes one fact.

Put the AICPA Blueprint at the start of the plan
The Blueprint is the scope boundary for your study method. In addition, it helps you decide what belongs in the block and what should be researched separately. It does not replace the Codification for a real accounting conclusion. Spend one short session checking the current area, group, topic, task statement, skill, and item type that frame your FAR work.
Revenue recognition study plan: set a clear boundary
Write a one-sentence boundary note such as: “This block practices revenue recognition timing and allocation plus accounting-change classification under simplified facts.” If a question turns on a transition provision, unusual financing, variable consideration, or entity-specific presentation, mark it for a source check rather than forcing it into the simplified drill.
Revenue recognition study plan: turn weak verbs into blocks
Use verbs instead of vague labels. For example, separate means distinguish cash from performance. Allocate means assign a transaction price before timing each promise. Estimate means investigate new information. Classify means identify a possible principle change and then check transition guidance. Finally, correct means investigate an available omitted fact. Your error log should store the verb, not only the topic name.
Use a 14-day schedule that changes with your weak lane
Use the schedule as a repeatable cycle. Each block can be 25 to 45 minutes; the exact duration depends on your available time. However, keep the sequence, but shorten the number of examples when time is tight. The important control is that every block ends with one decision about what to do next.
- Days 1–3 — Scope and setup: read the current Blueprint boundary, create the two lanes, and complete one short output-identification drill. Do not begin by rereading every revenue definition.
- Days 4–6 — Timing and allocation: work prepayment, stand-ready service, and bundle cases. Write the formula or allocation basis before looking at the result.
- Days 7–9 — Changes: sort new evidence, an acceptable method switch, and an available omitted fact. For each, write the next research question rather than a universal treatment.
- Days 10–12 — Mixed work: complete one timing item and one change-classification item under a time limit. Explain why the nearest distractor fails.
- Days 13–14 — Retry and refresh: change one fact in the lane you missed, review the current source boundary, and book the next cycle from the repair verb.

Revenue recognition study plan: use a weak-lane score
A percentage by itself is not a study plan. Instead, record questions completed, correct without notes, lane, ignored fact, and next action. If timing is weak, schedule two even-service cases. If classification is weak, sort three “new evidence” and “available fact” cases. Therefore, keep the record diagnostic; it is not an official exam score or readiness forecast.
Practice timing and allocation with one controlling fact
Use short calculations to train attention. Keep the facts simple enough that the error comes from the lane, not from arithmetic noise. Afterward, state the fact that controls the answer and the choice you rejected.
Revenue recognition study plan: separate payment from performance
Northstar receives $72,000 on January 1 for twelve months of stand-ready support. Eight months are delivered evenly by August 31. Under the simplified facts, $72,000 ÷ 12 × 8 = $48,000 earned, with $24,000 remaining for undelivered service. The payment date is not the controlling fact. Instead, the delivered service period is. If you chose $72,000, schedule two prepayment drills and write “cash is not performance” at the top of the page.
Revenue recognition study plan: allocate before timing
Cedar sells equipment and three months of training for $240,000. Standalone selling prices are $180,000 for equipment and $60,000 for training. Equipment transfers immediately, and two months of training are delivered. First, assign the stated amounts to the two promises. Then recognize two months of training: $60,000 ÷ 3 × 2 = $40,000. A full-invoice answer skips both allocation and transfer timing. If you chose it, schedule one allocation case before another timing case.
Practice accounting changes by cause, not by label
When a number changes, ask “What caused the change?” before asking “How do I present it?” The labels below are study routing aids. Then research materiality, correction, disclosure, effective date, and transition requirements under current authoritative guidance when the real fact pattern requires them.
Revenue recognition study plan: route new evidence
A machine has a $90,000 carrying amount and no residual value at the beginning of Year 5. New production evidence changes the remaining useful life to four years. Under the simplified facts, the next-period depreciation is $90,000 ÷ 4 = $22,500. Therefore, the controlling fact is new evidence about the remaining estimate. Your next study verb is estimate, followed by a prospective-treatment source check.
Revenue recognition study plan: check a method switch
Suppose an entity moves from weighted-average inventory costing to FIFO and both methods are acceptable under the stated facts. Start with classify: this may be a change in accounting principle. However, do not write a universal transition answer from memory. Check the applicable guidance, effective date, permitted alternatives, and disclosure requirements. If you chose an automatic prospective answer, schedule a principle-change drill that ends with “check transition.”
Revenue recognition study plan: analyze an available fact
Suppose an inventory invoice was in the accounting team’s possession before the financial statements were issued but was omitted. That availability fact points first toward correct and prior-period error analysis. Then research materiality, correction, comparative-period, and disclosure effects. If you called it a new estimate, your retry should change only the information-availability date.
Use a diagnostic score to choose the next block
After a mixed set, do not restart the whole chapter. Record the lane, score without notes, controlling fact, nearest distractor, and repair verb. A score record is useful only if it changes what you will do next. Therefore, use the small form below as a private study aid.
Self-check: choose your next lane
First, attempt each original check before opening the explanation. These are editorial study checks, not official exam items. Put the controlling fact beside your answer.
Checkpoint 1 — What is earned after the service is delivered?
Bluebird receives $60,000 for ten months of even support. Three months are delivered. What simplified amount is earned?
- $60,000
- $18,000
- $42,000
- $6,000
Reveal Checkpoint 1 reasoning
Correct answer: B. $60,000 ÷ 10 × 3 = $18,000. Therefore, the next action is two more even-service cases if you selected A or C.
Checkpoint 2 — What comes before timing in a bundle?
Atlas sells equipment and training for $200,000. Standalone prices are $140,000 and $60,000; two of four training months are delivered. What should you do first?
- Recognize the full invoice at equipment transfer
- Use the printed invoice lines without checking standalone prices
- Allocate the transaction price, then apply each promise’s transfer pattern
- Wait until all training is complete
Reveal Checkpoint 2 reasoning
Correct answer: C. Allocation comes first; timing follows for each promise. Therefore, the next action is one bundle case with changed standalone prices.
Checkpoint 3 — Which fact changes the classification?
An invoice was available before issuance but was omitted from prior-year records. Which lane should you investigate first?
- New estimate
- Change in accounting principle
- Prior-period error analysis
- Future revenue timing
Reveal Checkpoint 3 reasoning
Correct answer: C. Information availability is the controlling fact. Therefore, the next action is to sort one available-fact case against one genuinely new-evidence case.
Turn the first missed lane into a retry
For each miss, record the checkpoint number, confidence before the reveal, fact ignored, distractor chosen, repair verb, and scheduled follow-up. Change one fact only. Timing misses call for a change to months delivered. For allocation misses, change standalone prices. If classification is the problem, change when the evidence became available. Finally, this makes the retry diagnostic instead of repetitive.
FAR study-method FAQ and refresh note
Revenue recognition study plan: should the two topics be together?
Keep them in one 14-day plan so you practice switching, but keep the drills separate long enough to identify the controlling fact. In other words, mixed review belongs after the lane-specific work, not before it.
Revenue recognition study plan: how long should one block take?
Use 25 to 45 minutes as a starting point. If your available time is shorter, keep the target, one fact, miss log, and next action while reducing the number of examples. That way, the method remains diagnostic.
Revenue recognition study plan: when both lanes are weak
Return to output identification and the fact card. Next, complete one timing case and one classification case with notes, then repeat them without notes. The goal is to locate the first broken decision, not to reread everything.
Revenue recognition study plan: when to use current research
No. Use it to organize learning, but reopen the current AICPA Blueprint and FASB Codification when a question turns on a transition, effective date, contract detail, entity-specific issue, materiality, or disclosure.
Revenue recognition study plan: sources
Current tested-content boundary: AICPA CPA Exam Blueprints. Revenue framework background: FASB Revenue Recognition project summary. Technical refresh: FASB Accounting Standards Codification. Candidate-process routing: NASBA CPA Exam FAQ. The team checked these pages September 23, 2026. Reopen current guidance when the contract, entity, reporting date, accounting method, or transition fact changes. The examples, calculations, schedules, answer choices, rationales, and review prompts are original editorial study content.