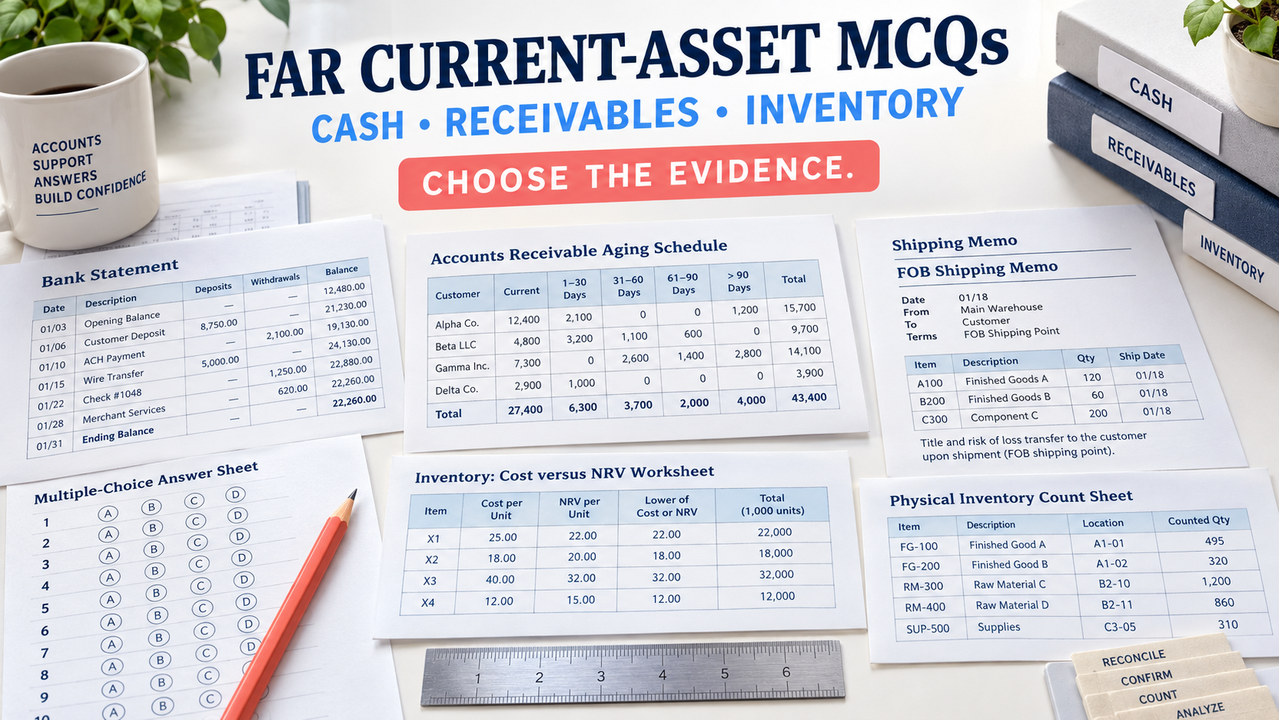

Direct answer: The safest way to solve inventory multiple choice questions is to name the evidence lane before choosing an option. First mark whether the fact belongs to cash timing, receivables collectibility, inventory ownership, inventory quantity, or inventory valuation. Then mark the date or shipping term, write the controlling rule, and eliminate the distractor that uses the wrong lane.
Editorial review note: This page was checked for terminology, arithmetic, internal consistency, and learner usefulness. The fact patterns, answer choices, rationales, visuals, and retry are original study material.
These FAR multiple-choice cases use simplified assumptions so the first reasoning decision stays visible. The current AICPA Blueprint and FASB reference pages define the boundary for live study; this page supplies a compact practice lab. If a prompt changes the reporting date, cost-flow assumption, allowance model, or shipping term, reopen current guidance instead of forcing a shortcut. For broader routing, visit the FAR review hub.
Inventory multiple choice questions: use a four-box answer grid
Before reading the options, draw four small boxes. This keeps the question from becoming a hunt for a familiar number.
- Lane: write cash, receivables, ownership, quantity, or valuation. A bank statement and an aging schedule are not interchangeable evidence.
- Date: circle the reporting date, count date, shipment date, receipt date, or later collection date. Most cutoff errors begin here.
- Rule: write the one rule the prompt actually gives you, such as FOB destination, target allowance, or cost compared with NRV.
- Distractor: explain why the nearest option is wrong. It often applies a true rule to the wrong record, date, owner, or balance.
Only after those four boxes are filled should you calculate. For a numeric question, label the amount as recorded, evidence, adjustment, or ending balance. For a classification question, label the owner, timing, or measurement rule. The method is short enough to use under time pressure but specific enough to reveal what broke when the choice is wrong.

Cash and receivables multiple choice questions: read the evidence source
Cash and receivables are both current assets, but their questions start from different evidence. A reconciliation compares two records of cash at the same date. An allowance question compares a required ending estimate with the balance already recorded. Start with the record before touching the arithmetic.
Inventory multiple choice questions: separate bank timing from book adjustments
Deposits in transit and outstanding checks explain why the bank statement and the entity’s ledger differ. Under the simplified facts, they adjust the bank side of the reconciliation. Bank fees, an NSF customer check, and bank interest usually require a book-side entry because the entity has not yet recorded those items. If every difference is placed on one side, the final equality will fail.
The clean sequence is: adjust the bank balance for timing, adjust the book balance for unrecorded bank activity, and confirm that both adjusted balances agree. If they do not, inspect the sign and the evidence source before inventing a new rule.
Inventory multiple choice questions: compare the allowance target with expense
When an aging analysis gives the required ending allowance, compare that target with the existing allowance balance. An existing debit balance must be reversed and then replaced by the required ending credit balance, so the current expense is larger than the target alone. An existing credit balance works differently. Write the target, the current balance, and the direction of the adjustment on separate lines.
Net receivables are gross receivables less the required ending allowance under the stated simplified method. A write-off can reduce both the customer balance and the allowance without creating a second expense when the allowance method applies. The key move is to use the target and existing balance together, not to treat the target as a new expense by reflex.
Inventory multiple choice questions: separate ownership, quantity, and valuation
Inventory questions normally test one of three different assertions: who owns the goods at the reporting date, how many units or dollars belong in the count, or whether the recorded cost remains recoverable under the stated measurement rule. Those are separate lanes. Read the term and date before deciding what belongs in ending inventory.
Inventory multiple choice questions: apply shipping terms at cutoff
FOB destination generally keeps the goods with the seller until delivery under a simplified question. If the goods are shipped on December 30 but arrive on January 3, the buyer does not include them in its December 31 inventory merely because an invoice exists. Consigned goods also remain with the owner rather than the warehouse holder. A cutoff question is therefore an ownership question first and a physical-location question second.
Inventory multiple choice questions: compare cost with NRV
When the prompt gives non-LIFO, non-retail facts and asks for a cost-versus-NRV comparison, use those stated amounts. If NRV is lower, the simplified write-down is the difference and the ending amount is the lower recoverable figure. Do not import a market ceiling, a profit estimate, or a different cost-flow rule unless the question supplies it. If the facts move outside the simplified lane, stop and consult current guidance.
Inventory multiple choice questions: investigate physical count quantity
A verified physical count below the perpetual record creates a quantity variance under the stated assumptions. It does not by itself decide whether goods in transit are owned, whether consigned goods belong to the entity, or whether recorded cost is recoverable. Keep quantity, ownership, and valuation as three distinct checkboxes when reviewing a wrong answer.
Original FAR cash, receivables, and inventory multiple-choice set
Tested skill, assumptions, and difficulty: This original set tests bank reconciliation, allowance estimation, inventory cutoff, cost-versus-NRV reasoning, and physical-count variance. Assume a calendar-year entity and the simplified facts stated in each item. Difficulty is moderate: the arithmetic is short, but the correct option depends on identifying the evidence source. Attempt every question before opening its reveal.
The questions are original editorial practice. They are not a live assessment or a score prediction. Use each rationale to identify the first broken decision, then write the next review action.

Question 1 — Reconcile the two cash records
Original practice prompt: The December 31 bank statement shows $64,200. A deposit of $3,400 is in transit, and checks totaling $2,100 are outstanding. Book cash is $65,700 before recording a $50 bank service charge, a $180 NSF customer check, and $30 of bank interest. What adjusted cash balance should both sides show?
Reveal Question 1 answer and reasoning
Answer: $65,500. The adjusted bank balance is $64,200 + $3,400 − $2,100 = $65,500. The adjusted book balance is $65,700 − $50 − $180 + $30 = $65,500. The deposit and outstanding checks are bank-side timing items; the fee, NSF check, and interest are book-side items. The nearest distractor applies every item to both sides. Repair verb: reconcile.
Question 2 — Move an allowance from debit to the required credit
Original practice prompt: Gross accounts receivable are $186,000. The allowance for doubtful accounts has a $2,400 debit balance. The aging analysis requires a $9,600 credit ending balance. Under the simplified allowance-method facts, what bad-debt expense and net receivables should the learner report?
Reveal Question 2 answer and reasoning
Answer: $12,000 expense and $176,400 net receivables. The allowance must move from a $2,400 debit to a $9,600 credit, so the expense is $2,400 + $9,600 = $12,000. Net receivables are $186,000 − $9,600 = $176,400. The nearest distractor records only the target credit and ignores the existing debit balance. Repair verb: target.
Question 3 — Apply FOB destination at year-end
Original practice prompt: On December 30, the entity buys goods costing $18,500 under FOB destination. The seller ships them on December 30, the goods arrive on January 3, and the buyer’s December 31 count excludes the shipment. What should the buyer include at year-end under the simplified facts?
Reveal Question 3 answer and reasoning
Answer: Exclude the $18,500 from the buyer’s December 31 inventory and payable. Under FOB destination, the seller retains the goods until delivery in this simplified case. The December 31 physical location and the shipping date point to the same conclusion: the buyer does not yet own the goods. The nearest distractor treats shipment as enough for buyer ownership without reading the term. Repair verb: cut off.
Question 4 — Compare cost with NRV under the stated assumption
Original practice prompt: A non-LIFO, non-retail inventory group has recorded cost of $72,000 and net realizable value of $69,400 at year-end. Ignore other complications. What write-down and ending inventory amount follow from the stated comparison?
Reveal Question 4 answer and reasoning
Answer: $2,600 write-down and $69,400 ending inventory. The difference is $72,000 − $69,400 = $2,600. The simplified ending amount is the lower NRV. A nearby distractor leaves cost unchanged because the goods remain on hand, or imports another market test not provided by the question. Repair verb: compare.
Question 5 — Explain a physical-count variance
Original practice prompt: The perpetual inventory record shows $38,250 at cost, while the verified physical count supports $37,600. No ownership or valuation issue is stated. What amount should the learner investigate, and what does it support?
Reveal Question 5 answer and reasoning
Answer: Investigate a $650 quantity variance. The difference is $38,250 − $37,600 = $650. Under the simplified facts, investigate the count, cutoff, and applicable shortage treatment. The result does not prove a broad control conclusion or a performance score. The nearest distractor changes the valuation rule even though the prompt gives only a quantity difference. Repair verb: verify.
Review inventory multiple choice questions by the first broken field
Do not turn five answers into one percentage and stop. Find the first broken field. A Question 1 miss means bank timing and book activity were mixed. A Question 2 miss means the existing debit balance was ignored. A Question 3 miss means the shipping term was not read. A Question 4 miss means the supplied measurement rule was replaced with a familiar one. A Question 5 miss means the physical record was not compared with the perpetual record.
Record the question, confidence before the reveal, evidence source, first broken field, repair verb, and next ten-minute review block. If the first field is bank timing, redo one reconciliation. If it is allowance logic, write target minus existing balance before reading the answer. If it is ownership or valuation, state the rule in words before touching the amount.
Retry inventory multiple choice questions after one bank fact changes
Change only Question 1’s bank service charge from $50 to $90. Keep the bank statement, deposit in transit, outstanding checks, book cash balance, NSF check, and interest unchanged. Which amount changes, and which relationship remains intact?
The adjusted book balance becomes $65,460 ($65,700 − $90 − $180 + $30). The adjusted bank balance remains $65,500, so the simplified records now differ by $40 until the book-side adjustment is recorded correctly or another fact is found. The retry changes one fact and exposes the next investigation; it does not justify changing the bank-side timing items.
Cash, receivables, and inventory multiple-choice questions: FAQ
Which bank-reconciliation items usually change the books?
Under the simplified facts, an unrecorded bank fee, NSF item, or bank interest amount changes the books. Deposits in transit and outstanding checks usually explain timing on the bank side. Follow the exact evidence in the prompt.
How do I calculate expense when the allowance starts with a debit?
Start with the required ending credit allowance, then move from the existing debit balance through zero to the required credit. The total movement is the current adjustment under the stated allowance-method assumptions. Net receivables then subtract the required ending allowance from gross receivables.
Does physical nonreceipt always exclude goods from inventory?
No. Read the shipping term first. FOB destination and FOB shipping point can produce different ownership results at the same reporting date. Consignment also depends on who owns the goods, not only where the boxes sit.
What should I do when a question changes the valuation method?
Stop using the shortcut from this page, write down the new assumption, and reopen current accounting guidance. A familiar cost-versus-NRV calculation is not a universal answer to every inventory measurement question.
Sources and refresh note for current-asset multiple-choice practice
Use the AICPA CPA Exam Blueprints for current scope and item-type boundaries, the FASB Accounting Standards Codification for current accounting guidance, and the NASBA exam FAQ for current exam-administration questions. These references were checked September 23, 2026. Recheck them before reusing this practice set after a Blueprint, reporting-date, or accounting-guidance change.
Next action: Attempt the five questions again tomorrow, record only the first broken field for each miss, and spend the next review block on that field. Keep the answer grid visible: lane, date, rule, distractor.