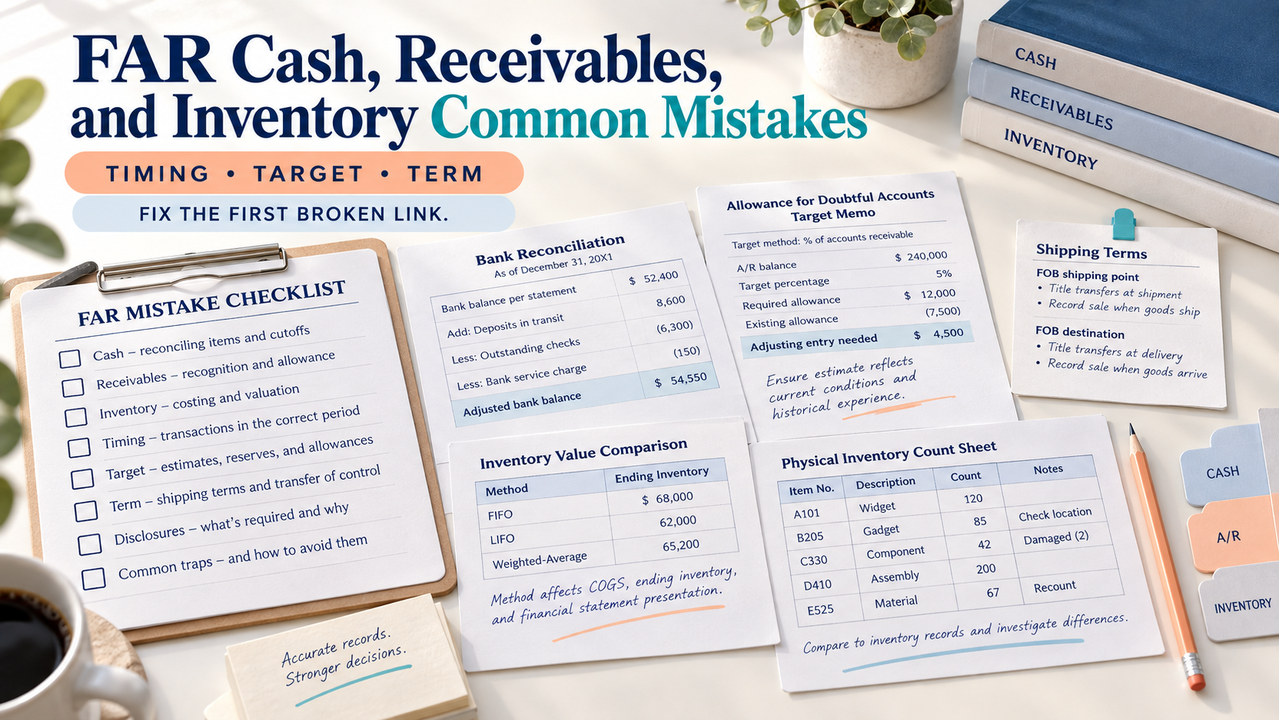

Direct answer: The fastest way to fix far cash receivables and inventory common mistakes is to name the controlling trigger before changing the number. Cash cases require separating bank timing from book activity. Receivables cases instead require moving the opening allowance to the required ending target. Inventory cases meanwhile require reading the ownership term, measurement premise, or count evidence before choosing a treatment.
Editorial review note: This page was checked by the CPA Exam Prep study-content team for terminology, arithmetic, internal consistency, source boundaries, and learner usefulness. In particular, the examples, prompts, answers, distractors, and correction checklist are original editorial practice, not provider-owned exam content.
These far cash receivables and inventory common mistakes use simplified facts so the failure mode stays visible. Meanwhile, the current AICPA Blueprint and current accounting guidance define the live boundary; this article gives you an original repair method. For broader topic routing, continue with the FAR review hub.
How to fix far cash receivables and inventory common mistakes
Before solving, write five short fields: asked output, source record, controlling fact, calculation or classification, and next check. Therefore, most current-asset mistakes begin when a familiar amount is treated as the answer before the source record has been classified. As a result, the repair is a decision sequence, not a longer formula list.
First, read the wording for the requested output. For example, a bank reconciliation asks for an adjusted balance, an allowance case may ask for expense movement and net receivables, a shipping case asks who owns goods at a date, a value case asks for a measurement adjustment, and a count case asks for an investigation difference. Next, circle the fact that controls that output. Finally, write one sentence explaining why the nearest distractor is wrong.
However, use only the facts stated in each original case. If a live question adds a reporting-date complication, different shipping term, allowance model, cost-flow method, or measurement rule, stop and reopen current authoritative guidance. Therefore, these practice cases are meant to expose the first broken link in reasoning; they are not a substitute for entity-specific accounting research or an official score prediction.
Build a far cash receivables and inventory common mistakes checklist
Keep the checklist beside your scratch work. Then, it should make the evidence lane visible before the arithmetic begins. In practice, a useful checklist is short enough to use under time pressure but specific enough to stop the five recurring shortcuts in this topic cluster.
Bank timing changes the bank side; fees and interest change the books.
Expense is the movement to the target, not automatically the target itself.
FOB terms can control the buyer’s inclusion at the reporting date.
A cost-to-NRV comparison is not the same evidence as a physical count.
Name the document or changed fact that would prove the correction.
When you miss an item, do not just copy the right number. Mark the first field that broke. When the source was misread, reread the record. If the trigger was misclassified, write the rule boundary. When the arithmetic was wrong, rebuild the equation. If the conclusion was unsupported, add the fact that would prove it. Consequently, that sequence keeps review targeted and prevents a broad reread from hiding the original mistake.

Five far cash receivables and inventory common mistakes
Attempt each case before opening the explanation. For every answer, record the requested output, the evidence lane, and the first tempting shortcut. The amounts below are independently authored so the method can be practiced without implying access to provider-owned questions.
Mistake 1 — Put bank timing items on the books
Question: The bank statement shows $96,400. Deposits in transit total $4,250, and outstanding checks total $2,980. The books show $97,340 before a $180 bank fee and $510 of bank interest. What adjusted balance should both sides support?
Reveal Mistake 1 answer and correction
Answer: $97,670. On the bank side, $96,400 + $4,250 − $2,980 = $97,670. On the book side, $97,340 − $180 + $510 = $97,670. However, the common mistake is to post deposits in transit and outstanding checks to the books. Therefore, the correction is to label bank timing items separately from book activity before entering a number.
Mistake 2 — Treat the ending allowance as the expense
Question: Gross receivables are $402,000. The allowance has an opening $11,600 credit balance, and the required ending credit is $20,300. What expense movement and net receivables follow?
Reveal Mistake 2 answer and correction
Answer: $8,700 expense movement and $381,700 net receivables. Expense movement is $20,300 − $11,600 = $8,700. Net receivables are $402,000 − $20,300 = $381,700. However, the mistake is recording the full ending allowance as current expense and forgetting the opening credit. Write the target balance and the movement to that target on separate lines.
Mistake 3 — Let the shipment date replace the ownership term
Question: Goods costing $13,250 were shipped FOB shipping point on December 31. Goods costing $18,900 were shipped FOB destination on December 31 and arrived January 4. Which goods belong in the buyer’s December 31 inventory under the stated facts?
Reveal Mistake 3 answer and correction
Answer: include the $13,250 FOB shipping point goods and exclude the $18,900 FOB destination goods. Here, the stated shipping term controls the ownership trigger under the simplified facts. By contrast, the common mistake is to use the shipment date for both lots. Circle the term first, then decide whether the buyer owns the goods at the reporting date.
Mistake 4 — Turn a value comparison into a count adjustment
Question: Under the simplified comparison supplied for this exercise, recorded inventory cost is $74,800 and NRV is $72,950. What write-down and ending amount follow?
Reveal Mistake 4 answer and correction
Answer: a $1,850 write-down and $72,950 ending inventory. The difference is $74,800 − $72,950 = $1,850. However, the mistake is to look for a physical shortage because the prompt contains an inventory amount. This is a measurement lane, so support the answer with the cost-versus-NRV comparison and preserve the stated simplification.
Mistake 5 — Treat a physical difference as an immediate valuation conclusion
Question: The perpetual record supports $61,480 at cost, while the verified physical count supports $60,930 at cost. No ownership or value complication is supplied. What amount should you investigate first?
Reveal Mistake 5 answer and correction
Answer: investigate a $550 shortage. First, the physical amount is $550 below the record. Check count accuracy, cutoff, receiving records, and shortage support before choosing a final treatment. Finally, the common mistake is to convert a quantity difference into a valuation conclusion without evidence.
Review far cash receivables and inventory common mistakes by the first broken link
Score a case only when the number or decision, the evidence lane, and the correction sentence are all right. A 0–2 result means rebuild the checklist and redo the two weakest lanes. With a 3–4 result, target the first broken field with a changed amount or term. Once you reach 5, transfer the method to a mixed packet without reopening the same answer key. These are local study routes, not official score bands.
Next, use the first broken link as the review label. Source error means the wrong document or fact was used. Trigger error means the document was read but the rule boundary was missed. Calculation error means the correct lane was selected but the sign, movement, or difference was wrong. Support error means the result may be right but the reason does not identify the controlling fact. Each label points to a different next action.

Retry far cash receivables and inventory common mistakes after one changed fact
Change only the allowance fact in Mistake 2. Next, keep gross receivables at $402,000 and the required ending credit at $20,300, but change the opening credit from $11,600 to $9,900. As a result, net receivables remain $381,700 because the ending target did not change. The expense movement becomes $20,300 − $9,900 = $10,400. If you change net receivables instead, you moved the target line when only the opening balance changed.
Choose a second retry based on your first weak lane. In the cash lane, change only the bank fee and recompute the book side. Ownership cases change only the shipping term and explain the inclusion. Value cases change only NRV and state the comparison. Count cases change only the physical amount and investigate the difference. Finally, the controlled retry should change one fact, preserve the evidence structure, and require a new correction sentence.
Research and support far cash receivables and inventory mistake corrections
Research narrowly. Next, use the current AICPA Blueprint to orient tested scope, then use current authoritative accounting guidance when a live fact pattern goes beyond the simplified assumptions here. However, a real question may turn on a reporting date, shipping term, allowance method, cost-flow assumption, or measurement requirement that this page intentionally holds constant.
When documenting each correction, write a support sentence in this form: “Because the source is ___ and the controlling fact is ___, the correct output is ___.” Cash corrections should name bank timing versus book activity. The allowance case should name the ending target and opening balance. Ownership corrections should name the term. Value corrections should name the comparison. Count corrections should name the record-to-physical difference and the investigation step.
Finally, do not use a practice result as a readiness claim. Meanwhile, the AICPA sample-test page can help with format orientation, but a local five-case result only tells you which study lane to review next. Likewise, the FASB Codification remains the source for a real technical conclusion; the cases here are a controlled learning aid.
FAR cash receivables and inventory common mistakes FAQ
Why do cash reconciliation mistakes keep happening?
They usually come from mixing bank timing with book activity. Label the side affected by each item before adding or subtracting it.
Why is the allowance expense not always the ending allowance?
Instead, the expense is the movement from the opening balance to the required ending target. Therefore, net receivables use the ending target against gross receivables.
Does the shipment date decide inventory ownership?
Not by itself. Under the stated practice facts, the shipping term determines the ownership trigger; a live case may require additional research.
What is the difference between inventory value and inventory count?
In contrast, a value case compares a recorded cost with a supplied measurement benchmark such as NRV. A count case compares a record with physical evidence and begins an investigation.
What should I do after a correct answer with a weak explanation?
Afterward, keep the point provisional, write the missing controlling fact, and retry one case after changing one fact. Ultimately, the goal is a defensible path, not a lucky number.
Sources and refresh note
Begin with the AICPA CPA Exam Blueprints for current scope. For format orientation, consult the AICPA sample tests. For current accounting guidance, use the FASB Accounting Standards Codification and the NASBA CPA Exam FAQ for administration questions. Finally, these pages were checked September 23, 2026; reopen them before reusing a fact-specific example after a scope or guidance change.
Next action: Recopy the five-field checklist, attempt Mistake 1 without notes, and label the first broken link before opening the answer.