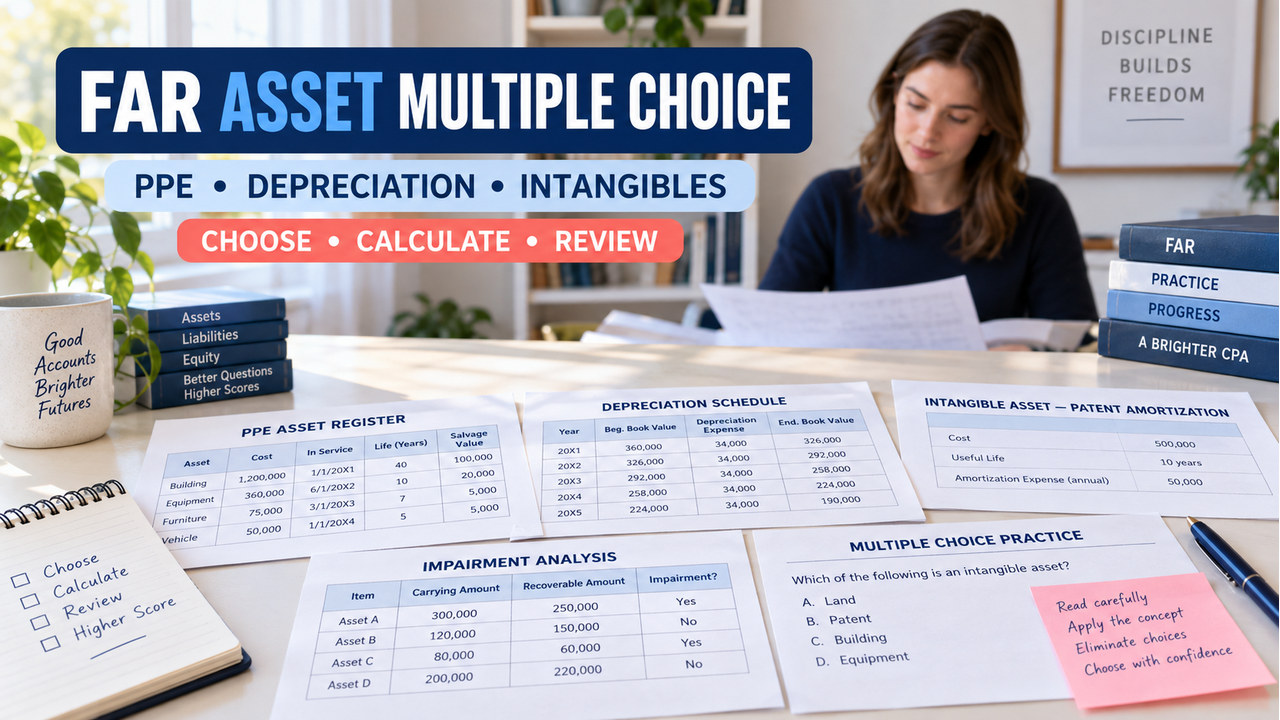

Quick answer: For impairment multiple choice questions that also mix PPE, depreciation, and intangibles, identify the lane before you calculate. Name the asset, build the basis, mark the relevant clock, identify the trigger, and then match the requested output to the answer choice. This order makes it easier to eliminate a familiar-looking formula that belongs to a different asset.
Editorial review note: This is an original FAR study set. The stems, amounts, answer choices, calculations, distractors, explanations, visuals, and retry were written for practice; they do not reproduce provider-supplied or exam-source items.
Additionally, use the current AICPA CPA Exam Blueprint for live scope and the FASB Accounting Standards Codification for current accounting guidance. The simplified cases below are designed to expose the controlling fact. For a wider study route, continue to the FAR review hub; for administration questions, check the current NASBA CPA Exam FAQ.
Impairment multiple choice questions: start with the lane
First, before reading the choices, write five labels in the margin: ASSET, BASIS, CLOCK, TRIGGER, and OUTPUT. The labels are a guardrail. They keep a partial-year depreciation problem from being answered with a full-year amount, and they stop a finite-life patent from being treated like an indefinite-lived mark.
- Asset: Decide whether the fact pattern describes PPE, a finite-lived intangible, an indefinite-lived intangible, or a held-and-used long-lived asset group.
- Basis: Include costs that make the asset ready for intended use when the simplified facts call for capitalization. Separate training, repairs, or other stated expense items.
- Clock: Circle the placed-in-service or available-for-use date, useful life, residual value, and reporting date. A “year one” answer may cover only part of a year.
- Trigger: Ask whether the question calls for routine depreciation, finite-life amortization, an indefinite-life impairment comparison, or a recoverability screen.
- Output: Only then calculate the requested number. If the question asks for a loss after a failed gate, do not stop at the undiscounted cash-flow amount.
Five choice filters for FAR asset questions
First, separate lane errors from arithmetic errors. A choice can be numerically tidy and still be wrong because it uses the wrong basis or the wrong date. For example, a full-year depreciation option may equal the correct annual amount, but it is not the correct first-year answer when the asset entered service on July 1.
Filter 1: ready-for-use cost, not every invoice line
For example, in the simplified PPE cases here, freight and installation help place the asset into service, while training is stated as an expense. The question is testing the cost boundary before it tests the depreciation formula. Write the basis on a separate line and keep salvage value outside the basis calculation.
Filter 2: the service date controls the first period
Next, apply the date the problem gives you. If the asset is available on July 1, six months of a twelve-month year is the stated first-period fraction. Do not silently substitute a convention that the question did not provide.
Filter 3: life classification changes the treatment
Similarly, a finite-lived patent normally has a stated amortization period in a simplified question. In contrast, an indefinite-lived mark is not amortized while the life remains indefinite under the stated facts, but applicable impairment testing still matters. That is why “no amortization” does not mean “no test.”
Filter 4: a recoverability screen is not the loss measurement
Similarly, in that lane, compare the carrying amount with the undiscounted cash flows first. If the carrying amount is not recoverable, use the stated fair value to measure the loss. The cash-flow amount is evidence for the gate, not automatically the recorded loss.
Filter 5: audit distractors in impairment multiple choice questions
Finally, do not mark a letter correct until you can say why the closest alternative misses. That sentence tells you whether the error was basis, clock, life, trigger, or measurement. It also gives you a better next study block than a raw percentage.

Original impairment multiple choice questions
Next, attempt each question before opening its answer. Use the stated assumptions only. These are original editorial practice questions, not provider-supplied items. Record the letter, your confidence, and the controlling label from the five-field map.
Question 1: PPE basis and straight-line depreciation
Difficulty: foundational calculation. A machine invoice is $480,000. Freight is $14,000 and installation is $26,000. Employee training is $8,000 and is expensed under the stated facts. The machine has a $20,000 salvage value and an eight-year useful life. What is the annual straight-line depreciation?
- $60,000
- $62,500
- $63,500
- $65,000
Reveal the answer to Question 1
First, the correct choice is B, $62,500. The basis is $480,000 + $14,000 + $26,000 = $520,000. Training is excluded under the stated facts. Then calculate ($520,000 − $20,000) ÷ 8 = $62,500. Choice A forgets the installation cost; C adds training; D subtracts salvage from the wrong total or treats the life incorrectly. The controlling label is BASIS.
Question 2: partial-year depreciation
Difficulty: timing check. A $360,000 depreciable basis has no salvage value and a six-year life. It is placed in service on July 1. Under the simplified facts, what depreciation belongs in the first calendar year?
- $30,000
- $60,000
- $45,000
- $5,000
Reveal the answer to Question 2
Next, the correct choice is A, $30,000. Annual depreciation is $360,000 ÷ 6 = $60,000. Then, July 1 through December 31 is six months, so $60,000 × 6/12 = $30,000. Choice B is a full-year amount; C assumes nine months; D divides the annual charge by twelve without applying the six-month period. The controlling label is CLOCK.
Question 3: finite-lived patent amortization
Difficulty: classification plus timing. A patent costs $270,000, has a stated nine-year useful life, and is available for use on October 1. Under the simplified facts, what is the first-year amortization?
- $30,000
- $22,500
- $7,500
- $2,500
Reveal the answer to Question 3
Likewise, the correct choice is C, $7,500. The annual amount is $270,000 ÷ 9 = $30,000. Next, October through December is three months, so $30,000 × 3/12 = $7,500. Choice A ignores the availability date; B uses nine months; D divides the annual amount by twelve but forgets the three-month count. The controlling labels are LIFE and CLOCK.
Question 4: indefinite-lived trademark
Difficulty: treatment choice. A trademark remains indefinite-lived under the simplified facts. Its carrying amount is $340,000 and its fair value is $315,000 at the testing date. What is the best answer?
- Record $25,000 impairment and no amortization while the life remains indefinite
- Record $25,000 amortization and no impairment
- Record $315,000 impairment because fair value is the new carrying amount
- Record no change because indefinite-lived assets are never tested
Reveal the answer to Question 4
Therefore, the correct choice is A. Under the stated simplified facts, the difference is $340,000 − $315,000 = $25,000. An indefinite life means no routine amortization while that classification remains, not immunity from impairment testing. Choice B confuses finite-life amortization with the test; C records the entire fair value rather than the difference; D mistakes “indefinite” for “not tested.” The controlling label is LIFE.
Question 5: held-and-used impairment gate
Difficulty: gate plus measurement. A held-and-used asset group has a $760,000 carrying amount. The stated undiscounted cash flows are $730,000 and fair value is $655,000. Under the simplified two-step facts, what impairment loss is recorded?
- $30,000
- $105,000
- $730,000
- $0
Reveal the answer to Question 5
Finally, the correct choice is B, $105,000. The carrying amount of $760,000 exceeds the $730,000 undiscounted cash flows, so the recoverability screen fails. Then, the loss is measured as $760,000 − $655,000 fair value = $105,000. Choice A stops at the gate difference; C records the cash-flow estimate; D ignores the failed screen. The controlling labels are TRIGGER and OUTPUT.
Review impairment multiple choice questions by the first broken lane
As a result, after five attempts, review the first broken field rather than rereading every formula. If you chose the correct letter for the wrong reason, treat that as a miss for study planning. The goal is to make the decision path repeatable when one fact changes.

| First broken lane | What the miss usually means | Next ten-minute action |
|---|---|---|
| Basis | You included or excluded the wrong ready-for-use cost. | Rewrite one PPE cost schedule and label capitalized versus expensed items. |
| Clock | You used a full-year amount for a partial period. | Draw a twelve-month line and mark the service or availability date. |
| Life | You treated finite and indefinite assets the same. | Make two columns: amortize while finite; test while applicable and indefinite. |
| Trigger | You skipped the recoverability screen or applied the wrong test. | Write carrying amount, undiscounted cash flows, then fair value in order. |
| Output | You found evidence for the gate but answered a different requested number. | Underline the words “annual,” “first year,” “loss,” or “carrying amount.” |
Retry impairment multiple choice questions after one changed fact
First, change only Question 1’s salvage value from $20,000 to $30,000. Keep the invoice, freight, installation, training treatment, and eight-year useful life fixed. Before revealing the result, state which lane stayed constant and which number changed.
For this reason, the basis remains $520,000 because salvage value does not change the cost of getting the machine ready for use. The revised annual depreciation is ($520,000 − $30,000) ÷ 8 = $61,250. If your answer changed the basis instead, review the BASIS lane; if the arithmetic changed but the lane stayed correct, review the OUTPUT step.
Use impairment multiple choice questions in your next FAR study block
First, take the five questions without notes and record confidence before each reveal. Next, write one sentence for the nearest distractor. Then schedule only the first broken lane: basis, clock, life, trigger, or output. Finally, retry one changed fact the next day. This sequence converts multiple-choice practice into a review plan instead of a one-time score.
However, these simplified examples do not settle every real-world accounting judgment. When a question introduces a disposal classification, asset group, tax effect, alternative impairment model, or jurisdiction-specific rule, return to the current Codification and the live exam-administration guidance.
CPA exam questions
How should I start FAR impairment multiple choice questions?
Name the asset, basis, clock, trigger, and requested output before choosing an answer.
Does a full-year depreciation option ever work for a partial-year question?
Only when the facts support a full year. If the asset entered service during the year, apply the stated fraction.
Does indefinite-lived mean no impairment test?
No. Under the simplified lesson, it means no routine amortization while the life remains indefinite; applicable impairment testing still matters.