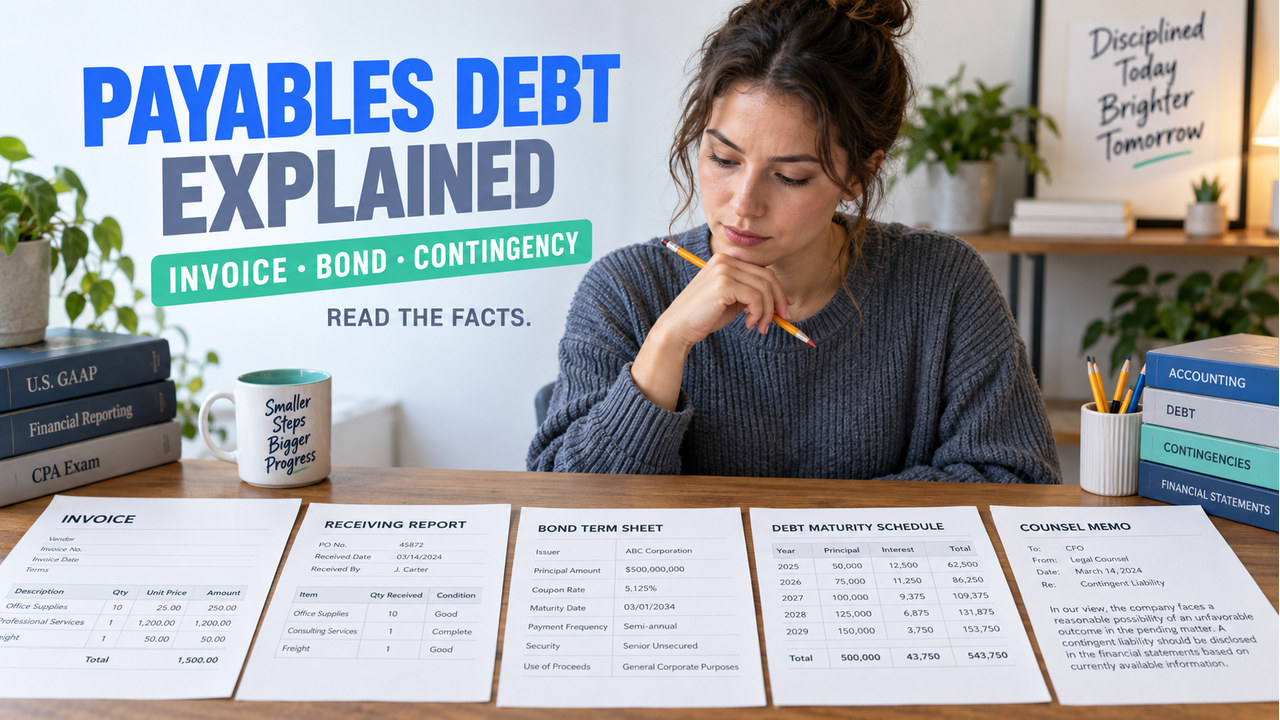

Direct answer: Payables, bonds, debt, and contingencies are related FAR liability topics, but they do not answer the same accounting question. In a payables debt review, start by naming the controlling source, the relevant date, the requested measure, the classification, and the disclosure consequence. That five-field check keeps an invoice from replacing a receiving report, a coupon from replacing an effective yield, a maturity schedule from disappearing into one long-term balance, or a serious-sounding legal memo from becoming an automatic loss. The examples below are original study material, not official or recalled CPA Exam questions.
What payables debt explanations need to separate
The phrase payables debt can sound like one large topic, yet FAR questions usually test a distinction inside it. A trade payable begins with an obligation for goods or services. A bond is a debt instrument with a face amount, contractual cash terms, and a carrying amount that may differ from face. Current debt is a presentation question about what is due within the relevant period. A contingency is a possible loss or gain whose recognition and disclosure depend on the facts and applicable guidance.
That means the first question is not “Which formula do I remember?” It is “Which lane does the fact pattern enter?” The answer determines what evidence matters next. For technical conclusions, reopen the current FASB Accounting Standards Codification. This page teaches a review method and simplified cases; it is not a substitute for the complete facts or authoritative guidance.
Use the five-field liability lens
Before choosing an answer, write five short labels. I repeat them deliberately because the same method can transfer across several FAR areas.
- Source: Which record controls the fact? It may be an invoice, receiving report, bond term sheet, maturity schedule, contract, or counsel memo.
- Date: Which date controls the question? Mark acceptance, issuance, reporting date, maturity, settlement, or elapsed-interest period.
- Measure: What unit does the question request? Separate face amount, carrying amount, cash interest, interest expense, current portion, loss, estimate, and disclosure.
- Classify: Which presentation or accounting lane fits? A result can be a payable, debt, current debt, contingency, expense, cash payment, or note disclosure.
- Disclose: What judgment or uncertainty must remain visible after you record the number—or when you record no number?
However, the lens is a guardrail, not a replacement for a standard. If two records disagree, preserve the disagreement and research the controlling rule. If the question changes one fact, restart the affected field rather than copying the prior conclusion.

Explain the accounting lanes without mixing them
Trade payables: start with the obligation and acceptance facts
A vendor invoice proves that a vendor billed an amount. It does not, by itself, answer every cutoff question. A receiving report may show when goods arrived and when staff accepted them. A contract may establish delivery terms. The reporting date determines whether the obligation belongs in the tested period.
First, for a payable question, read the document trail before calculating. Ask whether the goods or services arrived, whether staff accepted them, whether the complete evidence supports the requested amount, and whether the question asks for recognition, cutoff, or presentation. An invoice date can be useful evidence, but it does not automatically control the event.
Bonds: keep face, cash coupon, yield, and carrying amount separate
Bond questions often place several numbers close together. The issuer states face amount as the principal due at maturity. Coupon rate determines contractual cash interest. Effective yield and carrying amount can drive interest expense in an effective-interest pattern. Meanwhile, the issue price may create a discount or premium, so the carrying amount may differ from face.
Next, write a label beside each input before using it. Then read the requested unit: cash paid, interest expense, accrued interest, amortization, or ending carrying amount. A neat calculation can still be wrong when it uses a coupon rate to answer an effective-interest question or uses face amount to answer a carrying-value question.
Current debt: let the reporting date drive classification
Long-term borrowing can contain a portion due in the near term. A maturity schedule helps identify that portion at the reporting date. For a payables debt review, the question may ask for current debt, total debt, the remaining long-term amount, or a presentation decision. Those are not interchangeable outputs.
Then, mark the reporting date first. Separate principal due in the relevant period from the remaining balance. Afterward, check whether a refinancing, covenant, or waiver fact changes the analysis. Do not let the original label “long-term note” erase the current portion the schedule shows.
Contingencies: probability, estimate, and disclosure are different fields
A counsel memo supplies evidence, not an automatic journal entry. Read the probability language, the ability to estimate an amount, the reporting date, and the question’s requested response. A possible unfavorable outcome may lead to a different response from a probable outcome with a reliable estimate. A disclosure question is also different from a recognition question.
Instead, use the memo to identify the facts that need research. Do not convert emotional wording such as “serious” or “high risk” into a recorded loss without testing the applicable criteria. The current Codification, including the relevant contingency guidance, controls the conclusion.
Disclosure: finish the explanation, not just the arithmetic
Many liability questions still require a sentence explaining the judgment, uncertainty, terms, maturity, or classification. Finally, ask what a reader of the financial statements would need to understand about the recorded amount or unresolved exposure. When the prompt asks for a note, do not answer with a cash payment. When it asks for measurement, do not stop at a vague description.
Practice the payables debt distinction
Attempt each original check before opening the explanation. For example, use only the facts shown, write the requested unit, and identify the nearest distractor. These are original learning cases. They are not official, recalled, leaked, or exam-memory questions.
Check 1 — Which record leads the payable review?
Goods arrive on December 30. The receiving report shows acceptance on January 2. The invoice is dated December 29, and the reporting date is December 31. Which record should you inspect first?
- A. Invoice date only
- B. Receiving and acceptance records
- C. Vendor payment date
- D. Next month’s bank statement
Reveal the reasoning
Best answer: B. The first broken field is source/date. The invoice establishes a billed amount, but the receiving and acceptance records address the event and timing that the cutoff question is testing. Next action: retry the case after moving acceptance to December 31.
Check 2 — Which input answers interest expense?
A bond has a $100,000 face amount, a 5% coupon, and a 6% effective yield. The prompt asks for period interest expense. Which pair should lead the calculation?
- A. Face amount and coupon only
- B. Cash payment and maturity date
- C. Carrying amount and effective yield
- D. Face amount and maturity date only
Reveal the reasoning
Best answer: C. The first broken field is measure. Cash coupon and effective interest answer different questions. Next action: change the carrying amount while keeping the coupon unchanged and recalculate the requested expense.
Check 3 — Which debt amount is current?
A $240,000 note is payable in installments. The maturity schedule shows $40,000 due within the next operating cycle and $200,000 afterward. The prompt asks for the current portion.
- A. $40,000
- B. $200,000
- C. $240,000
- D. Zero because the note began as long-term debt
Reveal the reasoning
Best answer: A. The first broken field is classification. The reporting-date schedule separates the near-term principal from the remaining balance. Next action: change the installment date so the current portion must be recomputed.
Check 4 — What does a counsel memo establish?
Counsel describes an unfavorable outcome as reasonably possible, but the amount cannot be estimated. What should you identify before selecting a recognition answer?
- A. Probability wording and estimate availability
- B. Invoice number only
- C. Bond coupon
- D. Cash balance
Reveal the reasoning
Best answer: A. The first broken field is disclosure/recognition judgment. The memo supplies facts to analyze; its tone is not the answer. Next action: change the probability wording while keeping the estimate unavailable and explain how the response changes.
Check 5 — What does a cash payment prove?
A company pays six months of contractual interest on July 1. The prompt asks for interest accrued at December 31. Which step is necessary?
- A. Treat the July payment as the full-year expense
- B. Draw the timeline through December 31
- C. Use face amount as accrued interest
- D. Ignore the reporting date
Reveal the reasoning
Best answer: B. The first broken field is date/measure. Cash paid and interest accrued are different outputs. Next action: change the last payment date and mark the elapsed period again.
Check 6 — What changes when the yield changes?
Your original answer used a 5% effective yield. A revised case gives a 6% yield and leaves the coupon unchanged. What is the best first action?
- A. Copy the old answer
- B. Restart every FAR topic
- C. Circle the changed yield and recompute the affected measurement field
- D. Replace the yield with the coupon
Reveal the reasoning
Best answer: C. The first broken field is measurement. Change one input, preserve the other facts, and test transfer. Next action: write one support sentence explaining why the coupon did not replace the effective yield.
Reveal the lane and the reason
Attempt the six original checks first. Then reveal the answer, the controlling field, the nearest distractor, and the next ten-minute retry.
Reveal the answer
Answer: The useful result is not the letter alone: record the first broken field and repeat one changed fact.
Compare your process with the reasoning shown above.
Compare the accounting lanes without mixing them
Use the same four questions for each lane: What does the prompt ask? Which measure answers it? Where does the result appear? What should you check next? Start with cutoff evidence for payables. For bonds, check the relationship between carrying amount, yield, and cash coupon. Next, current debt requires the reporting-date maturity schedule. Finally, use current recognition and disclosure guidance for contingencies, together with the complete fact pattern.
This parallel method prevents a common study failure: rereading the whole chapter after one mistake. If the error is a current-portion classification error, a second unrelated bond calculation may not repair it. If the error is using coupon instead of yield, another invoice cutoff example may not help. Name the lane and choose a changed fact in that lane.

Use a first-broken-field log
Log the earliest wrong decision, not only the final wrong number. Write: “I used ___, but the prompt required ___.” Then save the source record, date, requested unit, nearest distractor, and one next drill. A useful log might say, “I used coupon cash interest, but the prompt required effective interest expense; reopen the carrying amount and yield fields; retry with a changed yield.”
Common questions about payables, bonds, debt, and contingencies
Is an invoice always enough to record a payable?
No. Use the complete reporting-date facts, including receiving, acceptance, contract, and cutoff evidence. The correct conclusion depends on the applicable guidance and the question’s requested output.
Are face value and carrying amount interchangeable?
No. The issuer states face value as the principal due at maturity; carrying amount may reflect the issue price and subsequent effective-interest accounting. Read the requested unit before calculating.
Does a serious legal memo prove a recorded loss?
No. Probability, estimability, reporting date, recognition, and disclosure are separate fields. Research the current contingency guidance and complete facts.
How should I use a missed check?
Identify the first broken field, reopen the relevant source, change one fact, and retry the same lane. Do not treat a local practice result as an official CPA Exam score or prediction.
Sources and scope boundary
Use the AICPA CPA Exam Blueprints to confirm the current FAR tested boundary, task statements, skill levels, and references. Use the FASB Standards page and the current Topic 405, Topic 450, and Topic 470 Codification research routes for technical accounting. The FASB debt-exchange project page is a status checkpoint, not a replacement for current GAAP. Use the NASBA CPA Exam FAQ for administration questions and our FAR review hub for the broader study route.
Before reusing this article, reopen each official source, confirm the effective date and current Codification content, and recheck every number, label, and assumption in the original practice cases. These cases teach distinctions; they do not reproduce official questions or predict a score.
CPA exam questions
Is an invoice always enough to record a payable?
No. Use complete reporting-date and acceptance evidence.
Are face value and carrying amount interchangeable?
No. Read the requested unit and use the relevant bond inputs.
Does a serious legal memo prove a recorded loss?
No. Analyze probability, estimability, recognition, and disclosure.