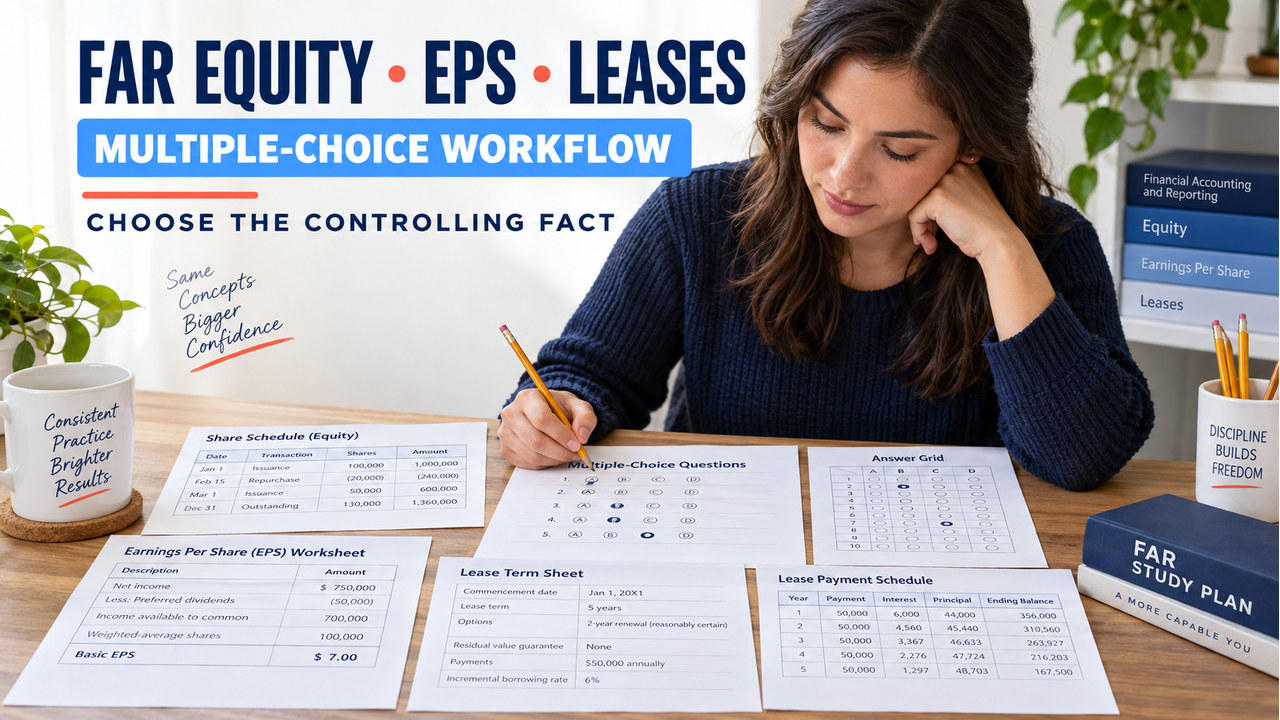

Short answer: The safest way to solve EPS multiple choice questions across FAR equity and leases is to read the ask before touching the numbers. Name the requested unit, circle the fact that controls it, eliminate choices from the wrong lane, and explain why the remaining option fits. That sequence keeps issued shares separate from weighted-average shares, preferred dividends separate from the EPS denominator, and lease timing separate from equity calculations. The items below are original study material, not official, recalled, or leaked CPA Exam questions.
This page combines three related FAR decision lanes: equity and share counts, earnings per share, and lease measurement. The AICPA Blueprints define the current study boundary, while the FASB Accounting Standards Codification remains the technical research checkpoint. Therefore, use the simplified cases to practice multiple-choice reasoning, then reopen complete guidance when a fact pattern becomes more complex.
How to read FAR equity, EPS, and lease choices
Multiple-choice questions reward the answer that fits the exact request, not the answer that contains the most familiar number. A stem may mention net income, share issuances, option prices, payments, renewal rights, and classification indicators in one paragraph. However, the question usually asks for one output. Before calculating, identify whether the output is a share count, numerator, basic EPS, diluted EPS, liability, right-of-use asset, lease term, or classification.
- Read the verb: compute, identify, classify, measure, or determine each points to a different response.
- Mark the unit: write the requested output in the margin before reviewing the options.
- Circle the controlling fact: timing, preferred dividends, exercise price, payment date, renewal certainty, or another stated condition may decide the result.
- Remove category errors: an option from the wrong accounting lane can sound reasonable but still answer a different question.
- Explain the survivor: a correct choice becomes useful only when you can state why its nearest distractor fails.

Use the stem-to-unit route before calculating
First, start with the sentence that contains the question mark. If it asks for a denominator, do not solve the numerator first. When it asks for a lease liability, do not report the annual cash payment. When it asks whether potential shares dilute EPS, do not add the entire option pool without applying the stated method.
Separate the record from the output
For example, a share certificate proves an ownership fact, but it does not by itself provide the period-weighted EPS denominator. A cap table shows the capital structure, while the income statement and preferred-dividend terms help identify income available to common shareholders. Similarly, a lease contract supplies term and payment facts, but the requested output may be the liability, the right-of-use asset, or a classification conclusion.
Use timing before arithmetic
Timing is often the hidden switch in a multiple-choice stem. A share issued halfway through the year does not belong in the denominator for the whole year. A payment at commencement does not create the same present-value pattern as a payment at period-end. In addition, a renewal option affects the lease term only when the stated facts support including it. Write the timeline before choosing a formula.
Read options as evidence of the trap
Wrong answers are often built from one true fact used in the wrong place. A total share count may ignore the time weighting. Net income may ignore preferred dividends. A coupon payment may be confused with the effective-interest amount. A lease liability may be substituted for the right-of-use asset. Consequently, ask what shortcut produced each option. That question points to the fact you need to recheck.
Compare answer choices without mixing the lane
Equity and EPS questions share some inputs, but their requested outputs differ. For EPS multiple choice items, write the requested output beside the stem before you compare the options. Lease questions use a different measurement path even when the stem also contains dates and payment amounts. Keep a three-column mental filter: what the stem asks, what record supports the fact, and what common trap the option represents.
Specifically, a share timeline supports the denominator; an EPS worksheet connects income available to common shareholders with weighted-average shares; a lease schedule supports the liability and right-of-use measurements. Meanwhile, a classification answer needs the stated economic indicators, not a copied payment total. Use the visual below as a comparison board, not as a sequence that forces every item through the same formula.

Original FAR multiple-choice questions
Attempt each item before opening its rationale. Write the requested unit first. Then record the fact that controls the choice and the option that looks attractive but answers a different question. Every item is original practice and uses simplified assumptions so that one skill remains visible.
Question 1 — What share count belongs in the denominator?
Skill: use time weighting for basic EPS. Assumptions: 80,000 common shares are outstanding from January 1 through June 30. The company issues 24,000 additional common shares on July 1 and makes no other changes. Which weighted-average share count should be used for a calendar-year basic EPS calculation?
- A. 80,000
- B. 86,000
- C. 92,000
- D. 104,000
Reveal the rationale
Best answer: C. The first half uses 80,000 shares and the second half uses 104,000. The weighted average is 80,000 × 1/2, plus 104,000 × 1/2: 40,000 + 52,000 = 92,000. Choice A ignores the issue, while D treats the ending share count as if it applied all year. Retry by moving the issue to October 1 and recomputing the weighting.
Question 2 — Which numerator should common EPS use?
Skill: identify income available to common shareholders. Assumptions: net income is $315,000. Noncumulative preferred dividends declared for the period are $15,000. The question asks for the numerator of basic common-stock EPS. Which amount is the best answer?
- A. $15,000
- B. $300,000
- C. $315,000
- D. $330,000
Reveal the rationale
Best answer: B. Subtract the preferred dividend from net income: $315,000 − $15,000 = $300,000. Choice C repeats the income-statement total but skips the preferred claim. Choice A identifies the deduction rather than the numerator, while D adds a claim that should be removed. Retry by keeping net income fixed and changing the preferred dividend to $22,000.
Question 3 — What is the incremental effect of the options?
Skill: apply the treasury-stock method under stated assumptions. Assumptions: 12,000 options are outstanding, each has an exercise price of $18, and the average market price is $24. Ignore taxes and use the treasury-stock method. Which incremental share amount belongs in diluted EPS?
- A. 12,000
- B. 9,000
- C. 3,000
- D. Zero
Reveal the rationale
Best answer: C. Exercise proceeds are $216,000. At the $24 market price, those proceeds would repurchase 9,000 shares, leaving 3,000 incremental shares. Choice A adds every option without the method, and B reports the repurchased shares rather than the incremental amount. Choice D would fit an out-of-the-money option, not this in-the-money fact pattern. Retry by lowering the market price below $18 and explain why the dilution test changes.
Question 4 — Which lease fact changes the present-value pattern?
Skill: distinguish payment timing. Assumptions: a lessee owes four equal annual payments. In Case A, each payment is due at the end of the year. In Case B, each payment is due at the beginning of the year. Which change should you evaluate first?
- A. The payment timing and present-value schedule
- B. The number of common shares
- C. The preferred-dividend deduction
- D. The legal name of the lessor only
Reveal the rationale
Best answer: A. Moving the payment from the end to the beginning changes when cash leaves the lessee and therefore changes the present-value pattern. The other choices belong to the equity and EPS lanes or do not affect the measurement requested. Retry by changing only the discount rate while leaving the payment dates unchanged.
Question 5 — Which amount belongs in the right-of-use asset?
Skill: keep the lease liability and right-of-use asset distinct. Assumptions: at commencement, the lease liability is $210,000. The lessee pays $8,000 of initial direct costs and receives a $3,000 lease incentive. Ignore other adjustments for this simplified item. Which amount is the initial right-of-use asset?
- A. $199,000
- B. $210,000
- C. $215,000
- D. $221,000
Reveal the rationale
Best answer: C. Start with the $210,000 liability, add $8,000 of initial direct costs, and subtract the $3,000 incentive: $215,000. Choice B reports the liability rather than the asset. Choice D adds the incentive instead of reducing the asset, while A removes both adjustments. Retry by changing only the incentive to $6,000.
Question 6 — When should a renewal period enter the lease term?
Skill: connect the lease term to the stated renewal fact. Assumptions: the noncancelable period is four years. The lessee has a three-year renewal option and is reasonably certain to exercise it because the replacement site would require a major relocation cost. What term should the analysis use?
- A. Four years only
- B. Three years only
- C. Seven years
- D. The vendor invoice period
Reveal the rationale
Best answer: C. The stated reasonable-certainty fact supports including the three-year renewal period, giving a seven-year lease term for this simplified question. The option is not included merely because it exists; the fact pattern supplies the economic reason. Retry by removing the relocation cost and reassessing the certainty conclusion.
Reveal the controlling fact
Attempt all six multiple-choice items first. Then record the requested unit, controlling fact, eliminated choice, and one changed-fact retry.
Reveal the answer
Answer: A letter without a unit and reason is not a completed review.
Compare your process with the reasoning shown above.
Turn a wrong option into a transfer drill
After each reveal, write four short lines: requested unit, controlling fact, eliminated choice, and next change. After a gross share count, change the issue date. When you used net income, change preferred dividends. When you added every option, change the exercise price. For a lease-liability mix-up, change the incentive or direct-cost fact. If renewal certainty was ignored, change the economic evidence.
- Share error: redraw the timeline and weight each period.
- EPS numerator error: separate income available to common shareholders.
- Dilution error: write the proceeds and repurchase step before the incremental shares.
- Lease timing error: label beginning versus end of period.
- Lease measurement error: keep liability, asset, incentive, and direct costs in separate lines.
- Lease-term error: state the evidence for or against reasonable certainty.
As a result, the retry should preserve the original skill while changing one fact. Do not change the amount, timing, classification, and requested output at once; that creates a new problem instead of testing transfer.
Review the pattern, not just the letter
Similarly, an EPS multiple choice review is useful when it explains why a choice won and why the runner-up failed. One missed share-timing item does not require rereading every lease rule. Instead, classify the miss as unit selection, timing, numerator, dilution, lease measurement, or lease term. Then choose one ten-minute drill that changes only that field. This keeps the next study action proportional to the error.
- One miss in the same lane: solve the same skill with a new date or amount.
- Two misses across equity and EPS: repeat the stem-to-unit route before calculating.
- Two lease misses: rebuild a liability and right-of-use schedule from separate inputs.
- Correct letter but weak explanation: name the controlling fact and nearest distractor in writing.
FAQ about EPS multiple choice practice
Should I calculate before reading all choices?
No. For EPS multiple choice items, read the ask, mark the unit, and scan the choices for category traps before doing the arithmetic. The options often show which shortcut the question is testing.
Can I use issued shares as the EPS denominator?
Not automatically. The period and share changes matter, so compute the weighted-average common shares required by the stated facts.
Are lease liability and right-of-use asset the same amount?
No. They begin with related facts but can differ because of incentives, initial direct costs, prepayments, and other stated adjustments.
Are these official CPA Exam questions?
No. The six items are independently authored practice. Official sources define the study boundary and research routes; they do not turn these items into released or recalled questions.
Sources and scope boundary
Use the AICPA CPA Exam Blueprints for the current FAR tested boundary, task statements, skills, and references. Use the FASB Standards page and the current Topic 260 and Topic 842 Codification routes for technical research. Use the NASBA CPA Exam FAQ for administration questions and our FAR review hub for the broader study route.
Before reuse, reopen official sources, confirm the applicable facts, and recheck every assumption in these simplified cases. The goal is better reasoning about the requested unit, not a claim about an official exam result.