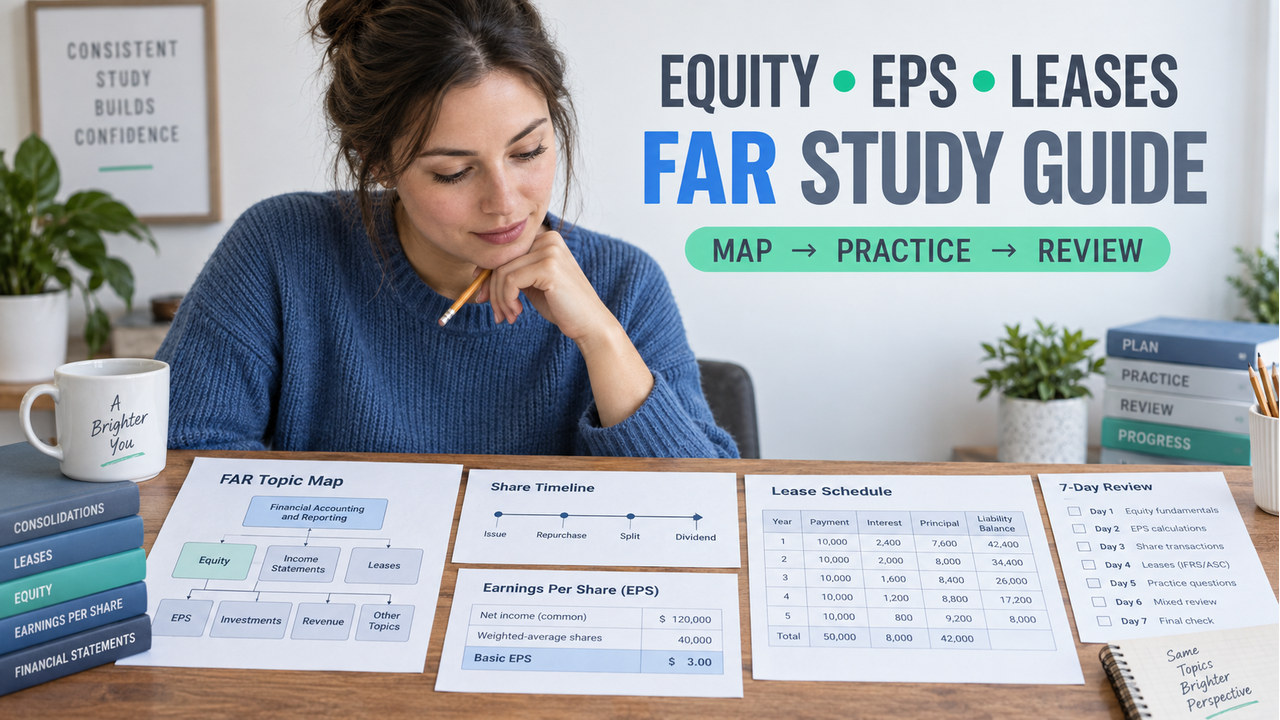

Short answer: A useful equity EPS lease study guide should do more than list formulas. It should map the three accounting lanes, identify the fact that controls each answer, and tell you what to review after a miss. Start with equity actions and share timing, move to EPS numerator and dilution mechanics, then study lease liability, right-of-use assets, and term judgments. Finish each block with a changed-fact retry.
This guide is built for that sequence. It uses the current AICPA Blueprint as a scope boundary and the FASB Codification as the technical research route. The examples are simplified and original. They are not official, recalled, leaked, or score-predictive questions. Your goal is not to memorize one number. Instead, you want to recognize the controlling fact, name the requested unit, and choose the next review block quickly.
What this FAR study map is designed to solve
Equity, EPS, and leases often appear together in a study plan because all three reward careful reading. However, they fail in different ways. Equity questions may turn on when shares changed or how a repurchase is presented. EPS questions may turn on the numerator, weighted-average shares, or incremental dilution. Lease questions may turn on payment timing, present value, right-of-use adjustments, or reasonable certainty about a renewal.
That difference matters after a missed question. If you misread an issue date, another lease formula will not repair the problem. If you used a coupon instead of an effective yield in a diluted-EPS setting, rereading a share-repurchase definition may feel busy without changing the weak skill. Therefore, this equity EPS lease study guide keeps the lane boundaries visible before you mix them.
- Equity actions: identify the transaction, timing, and direction of the equity effect.
- EPS measurement: separate income available to common shareholders, weighted-average shares, and potential dilution.
- Lease accounting: separate payment timing, liability measurement, right-of-use adjustments, and term evidence.
In each lane, ask four questions: What fact controls? What unit is requested? Which shortcut is tempting? What should I practice next? That common language makes the study plan easier to maintain.
Map the three accounting lanes
First, build a one-page map before opening a large question bank. On the equity side, place share issues, repurchases, treasury stock, and preferred dividends in the “transaction and timing” lane. For EPS, place basic EPS, weighted-average shares, options, convertibles, and anti-dilution in the “measurement” lane. For leases, place commencement, payment timing, discounting, right-of-use adjustments, renewal options, and classification in the “contract and judgment” lane.
Next, attach a controlling document or fact to each topic. A share timeline controls a time-weighted denominator. An income statement and preferred-dividend fact pattern control basic EPS. An option exercise price and market price control a treasury-stock calculation. A lease payment schedule controls present value. A renewal fact pattern controls whether the optional period belongs in the term. The map keeps the fact in view before you reach for a formula.

Lane 1: Equity actions and timing
Begin with the event, not the account label. When a new share issue occurs, mark the date and the number of shares that existed before and after the event. For a repurchase, mark the transaction as a reduction of equity under the simplified fact pattern and distinguish treasury stock from an operating expense. Meanwhile, preferred dividends can reduce income available to common shareholders before the basic EPS division.
Your first checkpoint is a timeline. Write the opening balance, the change date, the new balance, and the fraction of the reporting period. If the answer choices include the ending balance, the opening balance, and a weighted amount, the requested unit is probably time-weighted shares. Do not choose the largest number merely because it is visible at year-end.
Lane 2: EPS measurement and dilution
Separate the numerator from the denominator on scratch paper. Basic EPS begins with income available to common shareholders, so preferred dividends may matter before you divide by weighted-average common shares. Diluted EPS adds only the incremental effects that make the per-share result more dilutive under the stated assumptions. A treasury-stock method case needs the option count, exercise price, market price, and the repurchase effect. An if-converted case needs the after-tax numerator adjustment and the incremental shares.
A reliable EPS habit is to write the requested output beside the equation: “dollars per share,” “incremental shares,” or “income available to common.” This prevents a familiar intermediate number from looking like the final answer. It also exposes a common shortcut: adding every potential share without testing whether the instrument is dilutive.
Lane 3: Lease accounting
Lease cases become easier when you split them into four boxes. Start with payment timing: at commencement, at each period-end, or in advance. Box two is liability measurement: which payments are discounted and at what rate? Then check the right-of-use asset: which prepayments, incentives, or direct costs adjust the starting amount? Finally, check term evidence: what noncancelable period exists, and is the renewal decision reasonably certain under the facts?
However, do not let an attractive total payment replace the requested present value. Likewise, do not copy the lease liability as the right-of-use asset when the case supplies a prepayment, incentive, or direct cost. If the prompt asks for a term, look for economic evidence rather than treating every option as automatic.
Use a seven-day study sequence
Next, this equity EPS lease study guide becomes useful when it creates a repeatable calendar. The following seven-day route is a planning tool, not an official exam weighting. Use one focused block per day, keep a short error log, and change the facts in the final retry. If you have less time, combine adjacent days but preserve the order of map, lane practice, mixed application, and retry.
- Day 1 — Map: write the three lanes and attach one controlling fact, one requested unit, and one tempting shortcut to each.
- Day 2 — Equity: complete share-timing and repurchase cases. Draw the timeline before calculating.
- Day 3 — EPS: complete basic EPS, weighted-average shares, and one dilution case. Keep numerator and denominator on separate lines.
- Day 4 — Lease: complete one present-value case, one right-of-use adjustment, and one term judgment. Label payment timing.
- Day 5 — Mix: alternate the lanes so you must identify the topic before choosing a method.
- Day 6 — Retry: change one fact in each missed case and solve without looking at the original rationale.
- Day 7 — Check: explain one case aloud or in writing, then schedule the weakest lane for the next cycle.
For example, if Day 5 exposes two lease measurement errors but no equity timing error, carry the lease lane forward. Do not restart all three lanes simply because the mixed set felt difficult. A narrow next block is easier to complete and gives cleaner evidence about whether the repair worked.
Run five original transfer checks
Attempt these cases before opening the rationales. They are designed to test transfer, not recognition of a memorized answer. Record the requested unit and lane for each item. Then reveal the explanation and write the first broken field in your log.
Check 1 — Share timing
A company has 80,000 common shares from January 1 through June 30. It issues 20,000 more on July 1 and makes no other changes. What weighted-average share count applies to the year?
- A. 80,000
- B. 90,000
- C. 100,000
- D. 160,000
Reveal the rationale
Best answer: B, 90,000. First, the opening 80,000 shares apply for half the year and the 100,000 ending balance applies for the other half: 40,000 plus 50,000. The nearest shortcut is using the ending balance for every month. Next, the next block is another issue-date timeline with a three-month weighting.
Basic EPS numerator — Check 2
Net income is $420,000. Preferred dividends are $20,000, and weighted-average common shares are 200,000. What simplified basic EPS should you calculate?
- A. $1.90
- B. $2.00
- C. $2.10
- D. $2.20
Reveal the rationale
Best answer: B, $2.00. Subtract the preferred claim first: $420,000 minus $20,000 equals $400,000. Divide by 200,000 shares. The nearest shortcut is dividing total net income by shares and forgetting the numerator bridge. Next, change the preferred dividends while keeping the denominator fixed.
Check 3 — Dilution
There are 12,000 options with a $15 exercise price. The average market price is $20, and taxes are ignored. Under the treasury-stock method, what incremental share amount should be tested?
- A. 3,000
- B. 5,000
- C. 9,000
- D. 12,000
Reveal the rationale
Best answer: A, 3,000. Exercise proceeds are $180,000. At $20 per share, those proceeds repurchase 9,000 shares, leaving 3,000 incremental shares. The nearest shortcut is adding all 12,000 options. Next, lower the market price below the exercise price and decide what changes about dilution.
Check 4 — Lease payment timing
A lessee makes two $40,000 payments at each year-end. The provided present-value factors are 0.9524 and 0.9070. What approximate initial lease liability follows?
- A. $74,376
- B. $76,376
- C. $80,000
- D. $85,716
Reveal the rationale
Best answer: B, $74,376. Multiply $40,000 by the sum of the factors, 1.8594, to get $74,376. The nearest shortcut is using the undiscounted $80,000. Next, move the first payment to commencement and explain which timing fact changed.
Check 5 — Renewal evidence
A lease has a five-year noncancelable period and a three-year renewal option. The lessee built specialized improvements that cannot be moved economically. Which initial term is the best simplified conclusion?
- A. Five years automatically
- B. Three years automatically
- C. Eight years, if the facts support reasonable certainty
- D. The useful life of the improvements automatically
Reveal the rationale
Best answer: C. The specialized improvements are evidence that may support reasonable certainty, so the optional period can be included when the complete facts support that conclusion. The nearest shortcut is treating every option as automatic or ignoring every option. Next, remove the specialized-improvement fact and reassess.
Reveal the transfer check
Attempt the five original cases first. Then reveal the answer, the controlling field, the nearest shortcut, and the next ten-minute review block.
Reveal the answer
Answer: The useful result is the first broken field: timing, numerator, dilution, payment measurement, or renewal evidence. Change one fact and retry that lane.
Compare your process with the reasoning shown above.
Use the first-broken-field review ladder
After the five checks, write one sentence for each miss: “I used ___, but the prompt required ___.” Then assign the miss to one field. Timing errors call for a timeline. Numerator errors call for a bridge from income to common shareholders. Dilution errors call for an incremental-share calculation. Lease measurement errors call for a payment schedule and discount factors. Term errors call for an evidence sentence about reasonable certainty.
- Locate: name EQUITY, EPS, or LEASE.
- Label: name timing, numerator, dilution, measurement, term, or presentation.
- Change: alter one fact while holding the others constant.
- Retry: solve the same kind of problem without reopening the old answer.
- Schedule: keep the lane in the next review cycle only if the changed fact still causes an error.
This ladder keeps your study action proportional to the evidence. One wrong payment-timing calculation does not require a full lease restart. Conversely, repeated confusion between a liability and a right-of-use asset is a signal to return to the four-box lease model before doing more mixed questions.

How to use an equity EPS lease study guide
Use the equity EPS lease study guide as a map, then choose the next block from your first broken field. If share timing was weak, do three timeline cases with different issue dates. For EPS numerator or dilution weaknesses, separate numerator and denominator work before adding mixed instruments. When lease measurement was weak, label payment timing and discount factors. When lease term was weak, write the economic evidence for and against including the option.
To broaden the route, use the site’s FAR review hub to connect this map to the wider section plan. Use the official AICPA and FASB links below for scope and technical research. Keep the local cases separate from any official exam material.
FAQ about an equity, EPS, and lease study guide
Is this an official FAR blueprint or exam prediction?
No. The AICPA Blueprint and official research sources set the boundary, but this sequence is an original study aid. It does not assign official weights or predict a result.
Should I study all three lanes in one sitting?
Use a mixed block after you understand each lane separately. If every topic is new, follow the seven-day sequence and add mixed questions on Day 5.
Why does the guide ask for a changed-fact retry?
A changed fact tests whether you understood the method rather than remembered one answer. Keep the retry narrow so the result identifies the weak field.
What if I keep missing lease term questions?
Stop calculating and write the evidence for reasonable certainty. Then change one fact, such as removing specialized improvements, and reassess the term.
Sources and scope boundary
Use the AICPA CPA Exam Blueprints to confirm the current FAR boundary, task statements, skill levels, and references. Use the FASB Standards page and the current Topic 260 and Topic 842 Codification routes for technical accounting research. Use the NASBA CPA Exam FAQ for administration questions.
Before reuse, reopen the official sources, verify the applicable facts and dates, and recheck each simplified calculation. This guide teaches a review method; it does not reproduce official questions or promise exam success.