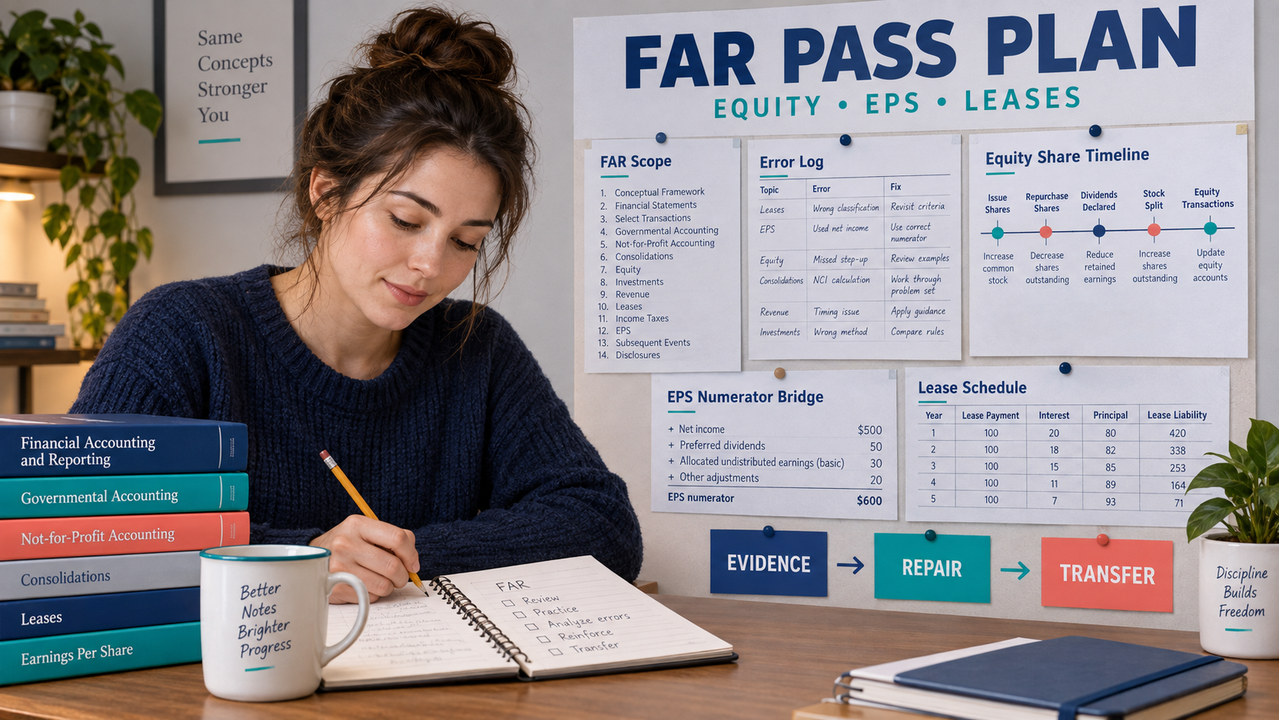

Short answer: To pass equity EPS lease accounting on FAR, build an evidence loop rather than a pass promise. Set the current scope, diagnose the first broken field, repair one method, and test that method on a changed fact. Advance only when the evidence holds without notes; otherwise, keep the lane narrow and repeat the repair. This gives a pass goal a practical method without pretending that any study plan can guarantee an exam result.
The AICPA Blueprint supplies the scope boundary, while the FASB Codification supplies the technical research route. The cases and review rules below are original and simplified. They are not official, recalled, leaked, or score-predictive CPA Exam questions.
Set the pass goal around evidence, not a promise
A pass goal is useful when it changes what you do next. It becomes unhelpful when it turns every practice result into an emotional verdict. A useful pass equity EPS lease accounting plan therefore defines observable evidence: you can identify the lane, explain the trigger, complete the method, and transfer it when one fact changes.
Start with the current FAR boundary and the task shape in the Blueprint. Then choose a narrow accounting output for the session. Equity may ask for weighted-average shares or income available to common shareholders. EPS may ask you to separate the numerator from potential-share dilution. Leases may ask for a liability schedule, right-of-use adjustment, or renewal-term judgment. The output determines the review evidence.
Do not use a single practice percentage as the whole decision. A familiar question can produce a correct answer for the wrong reason, while a new fact can expose a small but important gap. Keep the pass goal, the study evidence, and the official scope boundary as three separate records.
Build a three-lane diagnostic before studying
Use one short diagnostic to locate the first broken field. Give yourself one original case in each lane, then record the first point where the method stopped being explainable. The point is not to create a reliable score prediction. The point is to choose the next repair.
Equity: mark timing before calculating
For an equity case, write a dated timeline before touching an equation. Mark opening shares, issues, repurchases, preferred dividends, and any date that changes the weighting. If the error came from using an ending balance for every month, the repair is a share-timing timeline with one changed transaction date. Do not jump to a mixed set until the timeline remains correct under that change.
EPS: split the numerator from dilution
For EPS, put the numerator and denominator on separate lines. A numerator error may involve income available to common shareholders or preferred dividends. A dilution error may involve potential shares, an after-tax adjustment, or the question of whether an instrument is dilutive at all. One bridge and one potential-share decision are more useful than copying every formula into one page.
Leases: label payment timing and term evidence
For leases, label when payments occur before calculating the initial liability. Then separate the payment schedule from the right-of-use asset adjustments. If a renewal option appears, treat the term as an evidence question about reasonable certainty rather than as a vocabulary quiz. A repair should produce a labeled schedule or a short evidence comparison, not only a final number.
Use five progress gates
Five gates turn a broad pass goal into a repeatable decision. Each gate has a visible output. If the output is missing, do not hide the gap with more mixed questions; return to the smallest useful repair.
- Scope: write the FAR topic, task shape, and source route you are using.
- Diagnose: name the first broken field, not just the broad topic.
- Repair: complete one lane-specific method with notes available.
- Transfer: close the notes, change one fact, and explain the result.
- Mix: add a second lane only after the first repair holds.
The transfer gate is the most important safeguard against false confidence. If the changed fact breaks the method, keep the same lane and reduce the task. If the method holds, add one mixed item and log why advancement was justified.

Choose a weekly rhythm that protects weak fields
A realistic week does not require every day to look identical. Start with diagnosis and mapping on day one. Give day two to the weakest equity or EPS field. Reserve day three for leases or the second-most persistent field. Use day four for a changed-fact retry. Schedule day five as a small mixed set. Save day six for the field that failed transfer. On day seven, explain one case aloud and choose the next cycle.
Keep the stable lane in maintenance instead of giving it the whole schedule. For example, a correct lease schedule does not cancel a repeated EPS dilution error. Likewise, a good equity timeline does not prove that lease-term evidence is clear. The weekly rhythm should change allocation when the error log changes. Keep this pass equity EPS lease accounting routine tied to that evidence instead of to a fixed page count.
Set a stop rule for each block. Stop adding new material when you cannot state the requested output, when the calculation has no labeled inputs, or when the explanation depends on an answer letter. These stops protect the pass plan from becoming a volume contest.
Apply a decision rule to each study lane
Use a different first move for each lane, but keep the same evidence standard. The method below is deliberately narrow so that a learner can see what improved.
When equity timing is weak
Draw the timeline, place each share event on its date, and calculate the weight for only the affected interval. Then change one issue or repurchase date. A correct retry should include a sentence explaining why the weighted average changed. If the date change is handled mechanically without an explanation, stay at the repair gate.
When EPS numerator or dilution is weak
Make a numerator bridge first. Next, isolate one potential-share test and state the condition that makes it dilutive or anti-dilutive. Change one preferred-dividend amount or one market-price input. The next review action depends on the failed line: return to the bridge for a numerator error, or return to the potential-share decision for a dilution error.
When lease measurement or term is weak
Write the payment timing and discount inputs before the schedule. Then show how the liability and right-of-use asset are connected at commencement. For a term question, list the evidence for reasonable certainty and change one renewal fact. A final number without the schedule is not enough to clear transfer.
Run five original pass-plan checks
These cases test the next study decision, not official CPA Exam content. Attempt each one before opening the rationale. Record the lane, the first broken field, and the gate you expect to reach.
Check 1 — A broad pass goal with no evidence
You have studied the three lanes for a week but cannot explain which field caused your last three misses. What should the next block produce?
- A. Another mixed set with no error log
- B. One diagnostic case per lane and a first-broken-field record
- C. A new formula sheet for every topic
- D. A longer study block with no stop rule
Reveal the rationale
Best answer: B. The missing evidence is the lane and field, so the next action should create that record. More mixed questions would add noise. Use the results to choose one repair lane.
Check 2 — Equity timing repair
Your equity answer used the year-end share balance for every month. Which repair clears the diagnose gate?
- A. Memorize a new EPS formula
- B. Build a dated share timeline, then move one issuance date and recalculate
- C. Read a lease summary without calculating
- D. Repeat the same question until the answer feels familiar
Reveal the rationale
Best answer: B. The first broken field is timing. A changed issuance date tests whether the timeline method transfers instead of checking recognition alone.
Check 3 — EPS split
You subtract preferred dividends correctly but add every potential share to diluted EPS. What should lead the next session?
- A. A numerator bridge followed by one incremental-share test
- B. A lease-term evidence list
- C. A mixed set with no notes
- D. Copying all EPS vocabulary into a notebook
Reveal the rationale
Best answer: A. The numerator is stable, so keep it as a short confirmation and make dilution the primary repair. The changed fact should alter the market price or potential-share condition.
Check 4 — Lease transfer gate
Your lease liability schedule is correct, but you cannot explain why a renewal option belongs in the term. What is the right next move?
- A. Advance because the final number is correct
- B. Write an evidence comparison, change one renewal fact, and explain the term decision
- C. Abandon leases and switch to a new topic
- D. Add three unrelated payment schedules
Reveal the rationale
Best answer: B. Calculation accuracy does not clear a term-transfer gap. The next output must expose the evidence behind reasonable certainty and show how one fact changes the decision.
Check 5 — When to mix
Equity and lease repairs hold after changed facts, but EPS dilution fails twice. Which weekly allocation is most defensible?
- A. Mix all three lanes equally
- B. Keep equity and leases in short maintenance retrieval, and give EPS dilution the primary block
- C. Stop recording errors because two lanes are stable
- D. Repeat the same mixed set without changing a fact
Reveal the rationale
Best answer: B. The evidence supports maintenance for two lanes and a focused repair for EPS dilution. Mixing can return after the dilution transfer gate holds.
Close the block with evidence
End every session with four lines: “The broken field was ___; I repaired it with ___; the changed fact was ___; the next gate is ___.” This note prevents a correct answer from becoming an unexplained feeling of readiness.
Keep the changed fact narrow. Change one date, one payment timing, one preferred-dividend amount, one market price, or one renewal assumption. If three facts change together, a correct result cannot show which repair transferred. Record the failed line and repeat only that lane.
Route a weak result without resetting everything
Classify the miss before choosing the next topic. Misreads send you back to the wording and requested output. For a concept gap, write a short rule explanation. Calculation gaps send you to a labeled workpaper. A transfer gap sends you to the same method with one changed fact. This classification keeps a pass plan from treating every miss as a reason to restart the entire FAR section.

How to pass equity EPS lease accounting without a score promise
Use the pass equity EPS lease accounting method as a preparation framework, not a guarantee. A learner is ready to advance a lane when the task is identified, the method is explainable, the workpaper is labeled, and a changed fact holds without notes. That is stronger evidence than a single familiar score, but it still does not predict an official result.
For the broader section route, use the site’s FAR review hub. Use the official AICPA and FASB resources below for scope and technical research. Keep this local method separate from any official question, weighting, or result claim.
FAQ about a FAR pass plan
Can any study plan guarantee that I will pass?
No. A plan can organize preparation and create better evidence, but it cannot guarantee an official result. Keep the scope, current requirements, and your own testing decisions separate.
How do I know whether to repeat or advance?
Repeat when the same method fails on a changed fact or the explanation is not clear. Advance when the method transfers without notes and the workpaper shows the relevant inputs.
Should I mix equity, EPS, and leases every day?
No. Keep the weakest field primary and place stable lanes in short maintenance retrieval. Add mixed work after the primary repair clears transfer.
What if my mistake was reading rather than accounting?
Log it as a misread, rewrite the requested output, and retry the same facts before changing the accounting lane. A reading repair should not trigger a full topic restart.
Sources and scope boundary
Use the AICPA CPA Exam Blueprints to confirm the current FAR boundary, task statements, skill levels, and references. Use the FASB Standards page and the current Topic 260 and Topic 842 Codification routes for technical research. Use the NASBA CPA Exam FAQ for administration questions.
Before reuse, reopen the official sources, verify the applicable facts and dates, and recheck every simplified calculation. This is an original preparation method with original cases, not an official exam simulation or pass prediction.