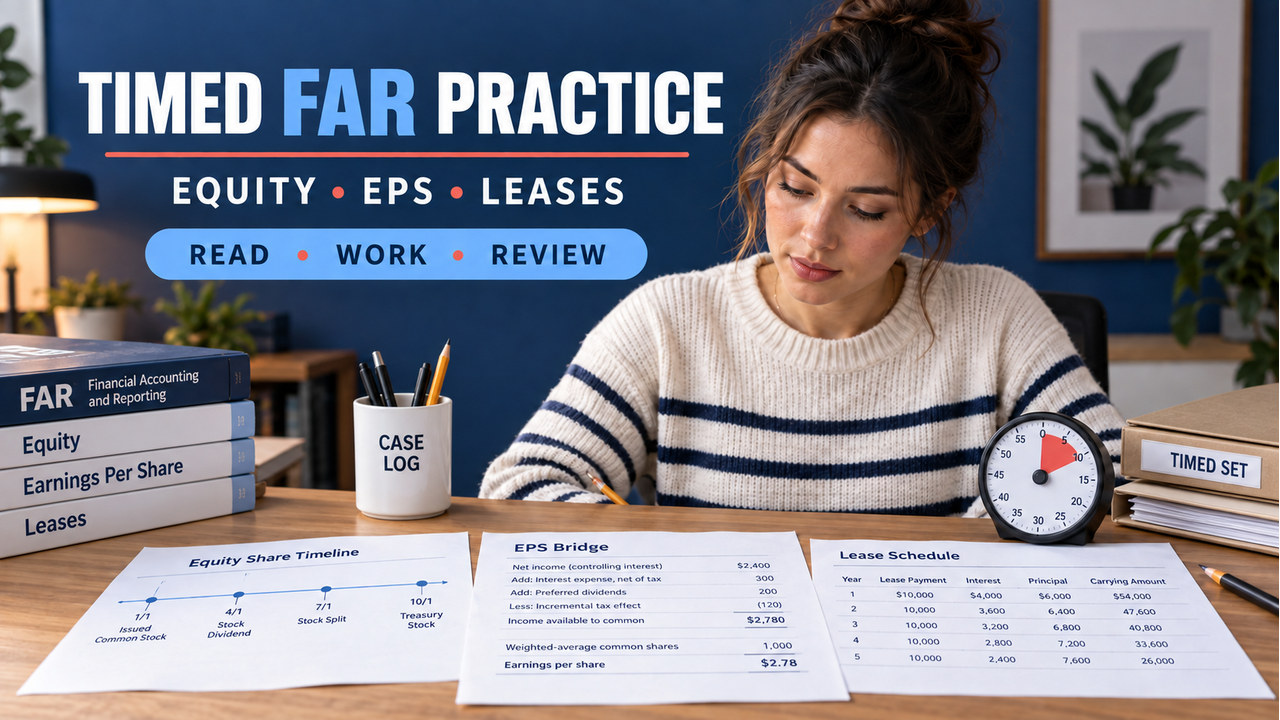

Short answer: A timed FAR equity practice set should test both accounting reasoning and pacing. Use a 45-minute block for five original cases: read the requested output, build only the workpaper you need, flag a slow or uncertain item, and review after the timer stops. The set below covers Equity timing, basic and diluted EPS, lease measurement, and a mixed transfer case. It is original practice, not official, recalled, leaked, or score-predictive content.
Before starting, keep the AICPA Blueprint as the scope boundary and use the FASB Codification for technical research after the attempt. Additionally, do not open the rationales until you have committed to an answer or written the exact point where you stopped.
Set the timer before you start
First, use one sheet for the timer log and one sheet for calculations. Next, give each case a short working window, but allow yourself to flag an item instead of spending the whole block on one difficult line. However, the goal is not to imitate an official exam screen. The goal is to make time use visible while you practice the accounting method.
- Minute 0–3: read the scope, write the five case labels, and prepare a flag mark.
- Minute 3–33: spend about six minutes on each case, including the answer choice and a one-line reason.
- Minute 33–38: return to one flagged item and finish the smallest missing workpaper.
- Minute 38–45: stop calculating and classify the clock result before reading rationales.
For example, in a 30-minute block, use four cases and reserve five minutes for review. By contrast, in a 60-minute block, keep the same five cases and add a changed-fact retry rather than another copy of the set. A useful timed FAR equity practice session makes the clock change the review action.

Original practice set: five timed cases
All five cases below are original teaching cases with simplified facts. Attempt each case before opening its rationale. Record the minutes used, the first broken field, and whether the issue was accounting, reading, setup, or pacing.
Case 1 — Equity share timing
Time box: 6 minutes. At January 1, a company has 100,000 common shares outstanding. It issues 20,000 shares on April 1 and repurchases 10,000 shares on October 1. Ignore preferred dividends and stock splits. What weighted-average share count should be used for a simplified annual calculation?
- A. 100,000
- B. 112,500
- C. 110,000
- D. 120,000
Reveal the rationale
Best answer: B. Weight the share balance by time. The company has 100,000 for three months, 120,000 for six months, and 110,000 for three months. Therefore, the simplified average is 25,000 + 60,000 + 27,500 = 112,500. The repair action is to rebuild the timeline and check the dates before moving on.
Case 2 — EPS numerator
Time box: 6 minutes. Net income is $480,000. Preferred dividends are $30,000. Weighted-average common shares are 225,000. No other adjustments apply. Which basic EPS amount is closest?
- A. $1.87
- B. $2.00
- C. $2.13
- D. $2.27
Reveal the rationale
Best answer: B. Income available to common shareholders is $450,000, and $450,000 ÷ 225,000 equals $2.00. The distractor in A reflects dividing net income by the share count without subtracting preferred dividends. If the calculation took more than six minutes, keep the numerator bridge visible and practice the preferred-dividend step.
Case 3 — Lease measurement
Time box: 7 minutes. A lessee makes four annual payments of $100,000 at each year-end. The present value of those payments at commencement is $354,600. Ignoring other adjustments, which amount is the best description of the initial lease liability?
- A. $100,000
- B. $300,000
- C. $354,600
- D. $400,000
Reveal the rationale
Best answer: C. The initial liability is based on the present value of the lease payments, not the first payment and not the undiscounted total. Meanwhile, the schedule should show the liability declining as payments are made and interest is recognized. Instead, a slow setup here usually calls for a payment-timing template, not another final-number question.
Case 4 — Diluted EPS
Time box: 7 minutes. Basic income available to common shareholders is $450,000 and basic weighted-average shares are 225,000. A potential common-share instrument would add 25,000 shares, with no numerator adjustment. Assume the instrument is dilutive. Which diluted EPS amount is closest?
- A. $1.80
- B. $2.00
- C. $2.22
- D. $2.50
Reveal the rationale
Best answer: A. The diluted denominator is 250,000 shares, so $450,000 ÷ 250,000 equals $1.80. The common trap is to keep the basic denominator or to add every potential share without testing whether it is dilutive. If this case was correct but slow, practice writing the numerator, denominator, and dilution assumption on three separate lines.
Case 5 — Mixed transfer and lease term
Time box: 8 minutes. A lease includes a renewal option. At commencement, management is reasonably certain to exercise it because the replacement location would be much more expensive and the improvements are specialized. Which review action is most useful before mixing this case with an EPS question?
- A. Memorize the lease abbreviation again
- B. Write the evidence for reasonable certainty and change one renewal fact
- C. Ignore the term because the payment schedule is correct
- D. Repeat the same mixed question without notes
Reveal the rationale
Best answer: B. The case turns on lease-term evidence, not on the abbreviation or the final schedule alone. Change one fact, such as removing the specialized improvements, and explain whether the renewal conclusion changes. This is a transfer check before a broader mixed set.
Review the answer and the clock separately
After all five cases, create two columns: accounting result and clock result. By contrast, a wrong answer with a clear method is different from a right answer produced by guessing. Likewise, a correct case that consumed twice its time box may still need a pacing repair.
Slow setup
Slow setup appears when you spend several minutes deciding what the question asks or how to lay out a schedule. Use a fixed first line: requested output, relevant dates, and the numerator or liability input. Then start the smallest workpaper.
Rushed reading
Rushed reading appears when the arithmetic is clean but the answer addresses the wrong output. Underline the requested unit and the condition that changes the method. A prompt-first habit is the next drill.
Second-guessing
Second-guessing appears when the first method was complete but you replace it without a new fact. Write one reason for the original answer and one reason that would justify changing it. If no new fact exists, flag the item and move on during the next timed set.
Accounting gap
An accounting gap remains after the wording and time use are clear. Route it to the matching workpaper: an equity timeline, an EPS numerator or dilution bridge, or a lease payment schedule and term-evidence note.
Use a second round without repeating the same set
Do not immediately retake the five cases from memory. Change one fact in the lane that failed. Move the equity issuance date, change the preferred-dividend amount, alter the potential-share assumption, shift lease payment timing, or remove one fact supporting reasonable certainty. The purpose is to test whether the method transfers.
Keep the second round smaller. One changed-fact case plus one maintenance case is enough when the original miss was conceptual. Three changed-fact cases may be useful when the accounting method was stable but the clock caused a rushed finish. Match the retest size to the diagnosis.
Route each timed miss to the next drill
Use the timer log to choose the next session. When the miss came from slow setup, use a blank workpaper template and keep the topic constant. For rushed reading, solve a short prompt-first set without increasing difficulty. If second-guessing caused the miss, record a stop rule. Finally, when accounting caused it, return to the exact Equity, EPS, or Lease lane.

Timed FAR equity practice: what to record next
Use the timed FAR equity practice log to record case number, minutes used, answer confidence, first broken field, and next drill. The total is useful only when it points to an action. A learner who finished four cases correctly but ran out of time may need pacing practice. A learner who finished quickly with repeated denominator errors needs an EPS bridge, not a faster timer.
For the broader section route, use the site’s FAR review hub. Use the official AICPA and FASB resources below for scope and technical research. This page does not convert the result into an official score or pass prediction.
FAQ about a timed FAR practice set
Should I use the same time limit as the official exam?
No. This is an original study drill. Use a repeatable local time box first, then adjust it as your workpaper setup improves. Do not treat it as an official exam simulation.
What if I cannot finish all five cases?
Record the case where the clock stopped and why. Review that case first, then run a smaller two-case retest with one changed fact.
Should I read the rationale after every question?
Attempt the full set or the planned block first. Delayed rationales make it easier to see whether pacing or answer exposure changed the result.
Which topic should I retest first?
Retest the first broken field that repeated or consumed disproportionate time. Keep stable topics in a short maintenance item.
Sources and scope boundary
Use the AICPA CPA Exam Blueprints to confirm the current FAR boundary, task statements, skill levels, and references. Use the FASB Standards page and the current Topic 260 and Topic 842 Codification routes for technical research. Use the NASBA CPA Exam FAQ for administration questions.
Before reuse, reopen the official sources, verify the applicable facts and dates, and recheck every simplified calculation. This is an original practice set, not official, recalled, leaked, or score-predictive exam content.