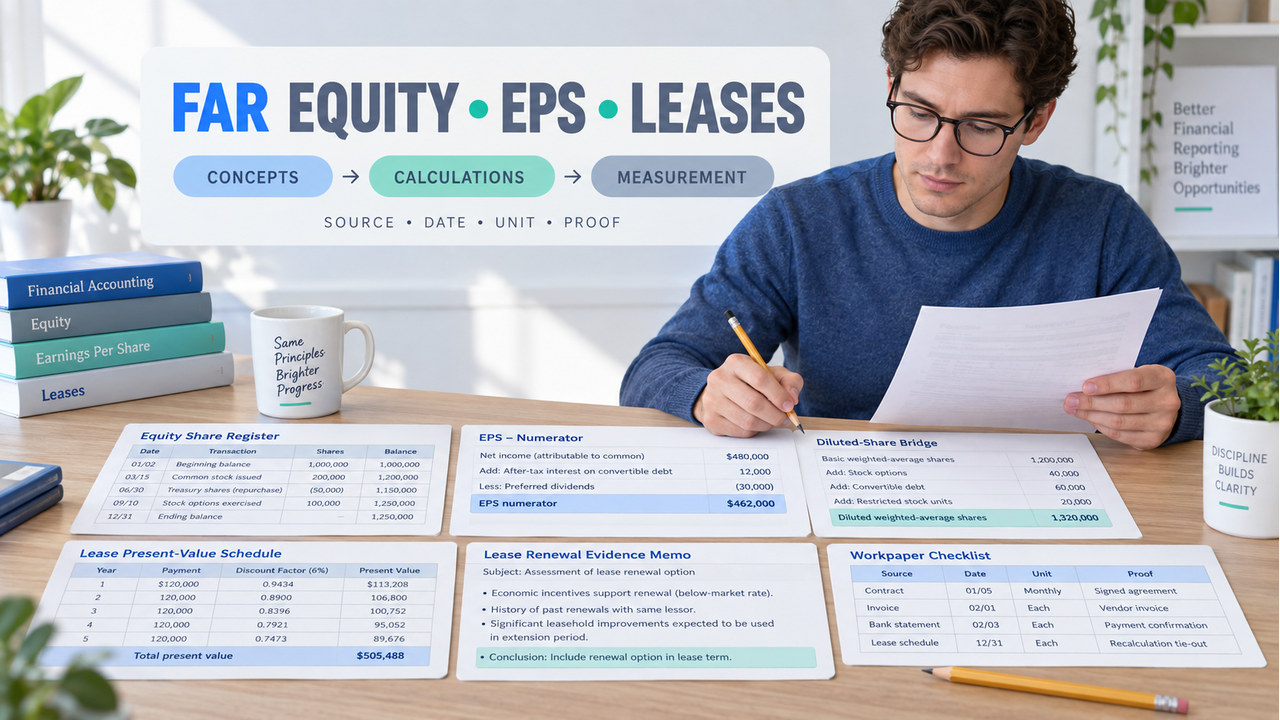

Direct answer: You can understand FAR equity EPS lease accounting explained as three linked evidence lanes. Equity starts with share records and dates. EPS turns income and shares into a per-share measure. Lease accounting turns payment, term, and renewal evidence into a present-value measurement. Across all three, use the same routine: identify the source, mark the date or term, name the requested unit, and write one proof sentence.
Scope note: The CPA Exam Prep editorial team checked the topic boundary against the current AICPA Blueprint and saved a research checkpoint on October 2, 2026. The team independently authored the amounts, documents, options, rationales, visual labels, and study actions. A real reporting conclusion still requires current research and complete facts.
First, for exam scope, reopen the AICPA CPA Exam Blueprint. Next, for technical accounting, use the current FASB Accounting Standards Codification, including Topic 260 for EPS and Topic 842 for leases. The NASBA CPA Exam FAQ covers administration separately. Finally, the AICPA sample-test resource can orient you to software and format, but it does not predict an official result.
How FAR equity EPS lease accounting explained fits together
Equity, EPS, and leases use different calculations, but the reasoning pattern is shared. First, an equity question asks which shares existed during which part of the period. Next, an EPS question asks which income belongs in the numerator and which shares belong in the denominator. Finally, a lease question asks which payments and term evidence belong in the commencement measurement. The calculation changes by lane; the evidence discipline does not.
Use four fields before touching a formula: source, date or term, unit, and proof. A share register controls transaction timing. An income bridge controls the basic numerator. Instrument terms control dilution. A lease schedule controls payment timing and present value. A renewal memo controls the lease term only when the facts support the judgment.
Which record controls?
Which period or option applies?
What must you return?
Why does the result follow?
Map the FAR equity EPS lease accounting explained framework
Start with the record, not the number that looks familiar. First, for equity, copy every issuance and repurchase date into a short timeline. Next, for EPS, separate net income, preferred dividends, and weighted-average shares before dividing. After that, for dilution, list each potential share and the assumption that makes it incremental. Finally, for leases, separate payment timing, discounting, and the evidence supporting any renewal period.
Next, write the requested output in words. The prompt may ask for weighted-average shares, basic EPS, diluted EPS, the initial lease liability, the lease term, or a next review action. One fact pattern can contain all of those numbers. Therefore, the requested unit tells you which one belongs in the final answer.

Original worked example: equity, EPS, and lease evidence
For context, the following example uses simplified facts so the bridge is visible. It is original study material, not an official, recalled, leaked, or score-predictive question. Keep the source field beside each calculation and write a proof sentence after the arithmetic.
| Lane | Controlling source | Core calculation | Requested output |
|---|---|---|---|
| Equity | Share register and transaction dates | Weight each balance by time outstanding | Weighted-average shares |
| EPS | Income statement, preferred terms, instrument terms | Numerator divided by basic or diluted denominator | Basic or diluted EPS |
| Lease | Contract, payment schedule, renewal evidence | Discount payments for the supported term | Initial liability or lease term |
Equity: weighting the share register
First, the register starts with 100,000 common shares on January 1. Next, the company issues 20,000 shares on April 1 and repurchases 10,000 on October 1. Ignore splits and other adjustments for this simplified example. Therefore, the annual weights are 100,000 × 3/12, 120,000 × 6/12, and 110,000 × 3/12. The total is 25,000 + 60,000 + 27,500, or 112,500 weighted-average shares. Finally, write this proof sentence: “The share register controls because each balance applies only after its transaction date.”
EPS: building the numerator and denominator
Next, assume net income is $480,000, cumulative preferred dividends are $30,000, basic weighted-average shares are 225,000, and a stated instrument adds 25,000 incremental shares when dilutive. Income available to common is $450,000. Consequently, basic EPS is $450,000 ÷ 225,000, or $2.00. Diluted EPS is $450,000 ÷ 250,000, or $1.80. Finally, write this proof sentence: “The numerator bridge removes the preferred claim, and the denominator adds only the tested incremental shares.”
Lease: separating cash from present value
For lease measurement, assume four annual payments of $100,000 at each year-end. The undiscounted total is $400,000, but the supplied present-value schedule gives $354,600 at commencement. Therefore, if the prompt asks for the initial lease liability, return $354,600, not the total cash. The proof sentence is: “Payment timing and discounting control the commencement measurement.”
Lease term: keeping renewal evidence visible
Finally, assume a five-year base term and a two-year option. Specialized improvements, replacement-site cost, and operating plans may support a reasonable-certainty conclusion in a simplified exercise. Do not include the option automatically. Write the evidence beside the term decision, then change one fact and retry. The proof sentence is: “The term follows the supported judgment, not the existence of an option alone.”
Practice the equity, EPS, and lease links
Attempt each question before opening its explanation. First, state the tested skill, assumptions, and difficulty. Next, reject the nearest distractor in one sentence. As a result, the sequence tests whether you connected the concept, rather than whether you memorized one number.
1. Which equity number belongs in the EPS denominator?
Tested skill: time-weight common shares. Assumptions: no stock split or preferred adjustment. Difficulty: foundational. For this check, the register contains the same January 1, April 1, and October 1 transactions shown above.
Question: Which amount should the simplified calculation use?
- A. 100,000
- B. 110,000
- C. 112,500
- D. 120,000
Reveal the answer and reasoning
Answer: C. Weighting by time produces 112,500. Option A uses only the opening balance, B uses the later balance without the full timeline, and D ignores the repurchase. Next action: draw the three date segments before retrying.
2. Which EPS numerator is available to common?
Tested skill: distinguish reported income from income available to common. Assumptions: preferred dividends are cumulative and no other adjustments apply. Difficulty: calculation setup. In this check, net income is $480,000 and preferred dividends are $30,000.
Question: Which numerator should be divided by common shares?
- A. $30,000
- B. $450,000
- C. $480,000
- D. $510,000
Reveal the answer and reasoning
Answer: B. Subtract the preferred claim: $480,000 − $30,000 = $450,000. Option C copies net income without the ownership adjustment. Next action: write the numerator bridge before entering the denominator.
3. Which lease amount answers the commencement question?
Tested skill: distinguish total cash from present value. Assumptions: the payment schedule supplies a present value of $354,600 and the prompt asks for the initial liability. Difficulty: measurement. For this check, use the commencement schedule only.
Question: Which amount should be returned?
- A. $100,000
- B. $354,600
- C. $400,000
- D. $454,600
Reveal the answer and reasoning
Answer: B. The commencement amount uses the supplied present value. Option C is undiscounted cash, while A is only one payment. Next action: label payment timing and present value as separate fields.
4. What changes when a diluted instrument is included?
Tested skill: keep the numerator and denominator roles separate. Assumptions: the prompt states that the instrument is dilutive and creates 25,000 incremental shares with no numerator adjustment. Difficulty: denominator control. For this check, use income available to common of $450,000 and basic shares of 225,000.
Question: Which diluted EPS amount is closest?
- A. $1.50
- B. $1.80
- C. $2.00
- D. $2.25
Reveal the answer and reasoning
Answer: B. Add the 25,000 incremental shares to the basic denominator: $450,000 ÷ 250,000 = $1.80. Option C is basic EPS. Next action: name the tested instrument and its incremental effect before calculating.
Route the FAR equity EPS lease accounting explained result to a next drill
Afterward, count a point only when the answer, controlling source, date or term, requested unit, and rejected distractor are visible. If an option is right for the wrong reason, route it to repair. A local result is a study-routing signal, not an official score or pass prediction.

For 0–2, rebuild the four-field model with one equity and one lease example. Next, for 3–4, target the first weak lane and complete two changed-fact questions. Finally, for 5–6, transfer the model to a new source packet and explain which field controls the result.
Log the first FAR equity EPS lease accounting explained break
Classify the earliest broken field, not the last arithmetic error. First, a source break means you used the wrong record. Next, a date break means you skipped a transaction or payment period. Then, a numerator break means you failed to separate the ownership claim from income. After that, a denominator break means you handled the incremental instrument incorrectly. Meanwhile, a measurement break means you used cash instead of present value. Finally, a term break means you assumed or ignored renewal evidence. As a result, a unit break means your response answered a different question.
Write the break as “I used ___, but the prompt asked for ___.” Then preserve the correct fields and change only one fact. For example, move the share issue to July 1, change preferred dividends to $20,000, remove the dilutive instrument, move lease payments to the beginning of each year, or remove the specialized improvements. A controlled change tests transfer.
Retry FAR equity EPS lease accounting explained with one changed fact
For the judgment retry, keep the five-year base term but remove the specialized improvements. Ask whether the evidence still supports the two-year option. Do not reuse the old conclusion automatically. Instead, separate the lease-term evidence from the present-value calculation.
Next, choose the lane with the weakest proof sentence. For example, if you reached $2.00 but omitted the preferred-dividend bridge, do a numerator drill. Likewise, if you reached 112,500 but left the dates unlabeled, redo the equity timeline. Finally, if your $354,600 answer lacked a payment schedule, rebuild the lease measurement exhibit.
Refresh FAR equity EPS lease accounting explained before reuse
Before reusing this FAR equity EPS lease accounting explained guide, reopen the AICPA CPA Exam Blueprints for scope and the FASB Codification for the technical boundary. Next, use Topic 260 for EPS research and Topic 842 for lease research. These links set boundaries; they do not turn the original simplified facts into universal conclusions.
Finally, recheck every number, date, assumption, image label, and answer reveal. If a real prompt supplies a different standard, jurisdiction, reporting date, contract term, or ownership class, stop the shortcut and research the current source.
FAR equity EPS lease accounting explained FAQ
Are these official CPA Exam questions?
No. They are original simplified study questions built to explain the evidence handoff.
Why connect equity and EPS?
Equity records supply the share timing and ownership facts that can feed an EPS denominator.
Why is lease cash different from lease present value?
The initial measurement uses supported payment timing and discounting, not the undiscounted total alone.
What should I review after a wrong answer?
Review the first broken field, then retry the same lane with one changed fact.