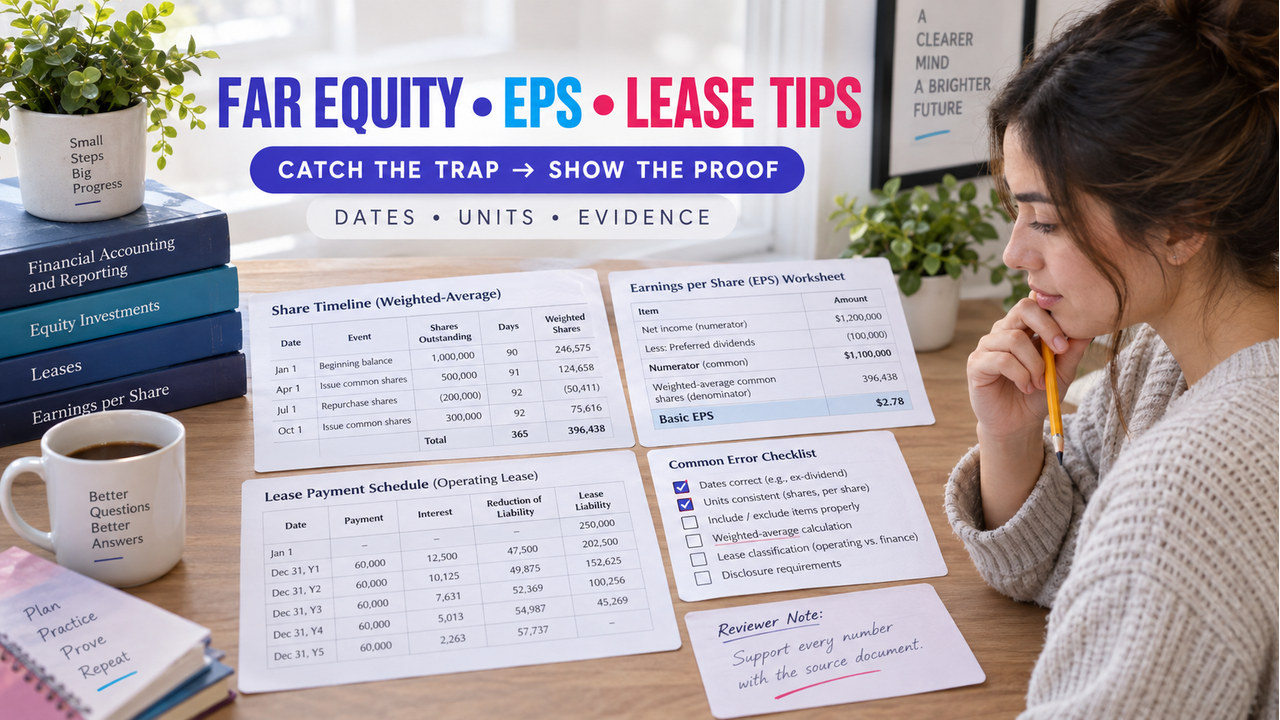

Direct answer: The best FAR equity EPS lease tips are small controls that stop a large mistake. Mark the transaction date before weighting shares. Build the EPS numerator before dividing. Add only the tested incremental shares. Mark payment timing before using present value. Treat a renewal option as an evidence question. Finally, write the requested unit in the margin before you calculate.
Scope note: The CPA Exam Prep editorial team checked this topic boundary against the current AICPA Blueprint and saved a research checkpoint on October 2, 2026. The team independently authored the amounts, documents, options, rationales, visual labels, and study actions. A real reporting conclusion still requires current research and complete facts.
For scope, reopen the AICPA CPA Exam Blueprint. For technical research, use the current FASB Accounting Standards Codification, including Topic 260 for EPS and Topic 842 for leases. The NASBA CPA Exam FAQ covers administration separately. The FAR review hub can help you choose a broader study path.
How FAR equity EPS lease tips fit a fast review
First, separate the calculation lane from the error lane. Equity questions usually break at transaction timing. EPS questions often break at ownership claims or potential shares. Lease questions often break at payment timing, discounting, or the support for a renewal period. Therefore, do not reread the whole chapter after one wrong answer. Name the first field that failed.
Next, use a five-field margin check: source, date or term, requested unit, calculation or evidence trigger, and proof sentence. That source tells you which record controls. The date or term limits the fact. Your unit tells you which number belongs in the response. This trigger tells you which rule to apply. The proof sentence explains why the result follows.
Then, apply the same sequence under time pressure. Read the final question phrase first. Write the unit. Circle dates, payment timing, and ownership terms. Complete one bridge. Reject the nearest distractor. Finally, spend the last few seconds asking whether your answer uses the same unit the prompt requested.

Build a five-field FAR equity EPS lease tips checklist
Use the checklist below before doing arithmetic. It is not a substitute for the applicable standard. Instead, it keeps a simplified practice fact pattern from changing lanes halfway through your work.
| Break point | Write first | Correction cue | Proof sentence |
|---|---|---|---|
| Equity timing | Transaction date | Weight only after the change | The register controls the period weight. |
| EPS numerator | Income available to common | Remove the stated preferred claim | The ownership claim changes the numerator. |
| EPS denominator | Incremental-share condition | Add only tested dilutive shares | The instrument changes the denominator only when the condition is met. |
| Lease measurement | Payment timing and term | Discount the supported cash flows | Cash total and present value answer different questions. |
| Lease term | Renewal evidence | Do not assume the option | The supported judgment controls the term. |
After that, use the nearest distractor as a diagnostic. A raw opening share balance points to a timing error. Net income without the ownership adjustment points to a numerator error. Basic EPS when the question asks for diluted EPS points to a denominator error. Total undiscounted payments when the question asks for a liability points to a measurement error. An automatic renewal period points to a term-evidence error.
Practice FAR equity EPS lease tips with original traps
Attempt each check before opening the explanation. These are original simplified study questions, not official, recalled, leaked, or score-predictive questions. Before choosing an answer, state the tested skill, assumptions, and difficulty. Then write the requested unit.
1. Catch the equity-date trap
Tested skill: weighted-average common shares. Assumptions: no stock split or other adjustment applies. Difficulty: foundational. The register shows 60,000 common shares on January 1, an issue of 12,000 on May 1, and a repurchase of 6,000 on November 1.
Question: Which simplified weighted-average balance fits the three date segments?
- A. 60,000
- B. 66,000
- C. 67,000
- D. 72,000
Reveal the answer and reasoning
Answer: C. Use 60,000 for four months, 72,000 for six months, and 66,000 for two months: 20,000 + 36,000 + 11,000 = 67,000. A ignores the issue, B ignores the timing structure, and D ignores the repurchase. Next action: draw the dates before touching the calculator.
2. Catch the EPS-numerator trap
Tested skill: income available to common. Assumptions: net income is $300,000, cumulative preferred dividends are $18,000, and no other adjustment applies. Difficulty: setup. However, the question asks for the numerator, not EPS.
Question: Which amount belongs in the numerator?
- A. $18,000
- B. $282,000
- C. $300,000
- D. $318,000
Reveal the answer and reasoning
Answer: B. Subtract the preferred claim: $300,000 − $18,000 = $282,000. Option C copies reported net income without the ownership adjustment. Next action: write “available to common” beside the numerator before dividing.
3. Catch the dilution-denominator trap
Tested skill: incremental shares. Assumptions: income available to common is $282,000, basic weighted-average shares are 141,000, and a stated instrument adds 16,000 shares when dilutive. Difficulty: intermediate.
Question: Which diluted EPS is closest when the prompt confirms the instrument is dilutive?
- A. $1.78
- B. $1.80
- C. $2.00
- D. $2.24
Reveal the answer and reasoning
Answer: B. Add the incremental shares: $282,000 ÷ (141,000 + 16,000) = about $1.80. Option C is basic EPS. Option A can result from rounding the denominator incorrectly, while D moves in the wrong direction. Next action: label the instrument and its incremental condition before the division.
4. Catch the lease-payment-timing trap
Tested skill: distinguish cash total from initial present value. Assumptions: a simplified schedule lists three annual payments of $90,000 at year-end and supplies an initial present value of $245,000. Difficulty: measurement.
Question: Which amount answers an initial-liability question?
- A. $90,000
- B. $180,000
- C. $245,000
- D. $270,000
Reveal the answer and reasoning
Answer: C. The supplied present-value schedule answers the initial-liability question. Option D is the undiscounted cash total, and A is only one payment. Next action: circle the words “initial liability” or “present value” before reviewing any cash total.
5. Catch the lease-term evidence trap
Tested skill: renewal-term judgment. Assumptions: a four-year base lease includes a two-year option. However, the fact pattern gives specialized improvements and a costly replacement site, but the question asks you to explain the evidence rather than assume the option. Difficulty: judgment.
Question: What should your answer show first?
- A. The option exists, so include two years automatically.
- B. The option is irrelevant because it is not in the base term.
- C. The evidence supporting or rejecting reasonable certainty.
- D. The total cash payment with no term discussion.
Reveal the answer and reasoning
Answer: C. The option’s existence does not end the analysis. The workpaper should connect the facts to the supported term conclusion. Next action: write one sentence naming the evidence before you carry the term into measurement.
Run the two-minute FAR equity EPS lease tips checkpoint
Now score only the five checks you just attempted. Count a point when the answer, controlling source, date or term, requested unit, and distractor explanation are all visible. If you picked the correct letter for the wrong reason, route the item to repair. Therefore, this local result changes your study action; it is not an official score or pass prediction.

For 0–2, rebuild the five-field margin check with one equity and one lease example. Next, for 3–4, target the first weak lane and complete two new changed-fact questions. Finally, for 5, transfer the routine to a fresh fact pattern and explain the proof sentence without looking at the answer.
Log the first FAR equity EPS lease tips break
Classify the earliest broken field, not the last arithmetic slip. Use a source break when you used the wrong record. A date break means you skipped a transaction period. With a numerator break, you left an ownership claim in income available to common. For a denominator break, you added or omitted potential shares without checking the condition. During a payment-timing break, you used the cash total instead of the supplied present value. With a term break, you assumed a renewal period without writing the evidence. Finally, a unit break means your response answered a different question.
Write the error in one sentence: “I used ___, but the prompt asked for ___.” Then preserve every correct field and change only one fact. For example, move the share issue to July 1, change the preferred dividend, remove the dilutive instrument, move payments to the beginning of each year, or remove the specialized improvements. One changed fact makes the repair testable.
Retry FAR equity EPS lease tips with one changed fact
Start with the lane that produced the first broken field. If your equity answer used 72,000, keep the issue and repurchase but move the issue to July 1. Rebuild only the date weights. If your EPS answer used $300,000, keep the shares but change the preferred claim to $12,000. Rebuild only the numerator. If your lease answer used $270,000, keep the payments but change them from year-end to beginning-of-year. Recheck the payment timing before using the schedule.
Next, write a proof sentence that would survive a fact change. “The register controls the weight after each transaction date.” “The preferred claim reduces income available to common.” “The supported payment timing controls the present value.” “The renewal conclusion follows the evidence.” These sentences are short, but they expose whether your method can transfer.
Refresh FAR equity EPS lease tips before reuse
Before reusing this FAR equity EPS lease tips guide, reopen the AICPA CPA Exam Blueprint for scope and the FASB Codification for the technical boundary. Next, use Topic 260 for EPS research and Topic 842 for lease research. These links establish research routes; they do not turn the simplified facts into universal conclusions.
Finally, recheck every number, date, assumption, image label, and answer reveal. If a live question supplies another reporting date, ownership class, instrument, payment pattern, jurisdiction, or contract term, stop the shortcut and research the current source.
FAR equity EPS lease tips FAQ
Are these official CPA Exam questions?
No. They are original simplified study questions built to diagnose five common evidence breaks.
What should I write before calculating weighted-average shares?
Write every transaction date and the share balance that applies after that date.
Why can a lease cash total be the wrong answer?
An initial-liability question may require the supplied present value, not the undiscounted total of payments.
What is the fastest response to a wrong answer?
Find the first broken field, change one fact, and retry only that lane with a proof sentence.