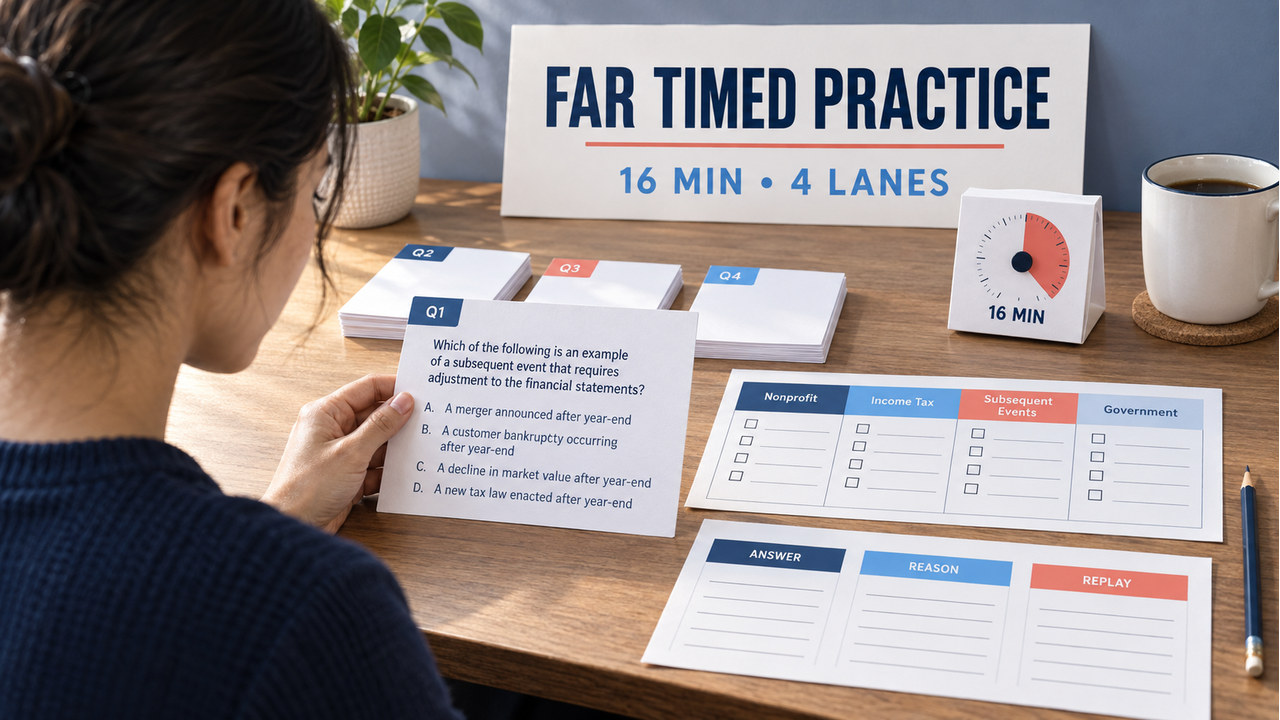

Direct answer: A useful timed FAR nonprofit accounting practice session needs a fixed clock, original items, delayed answer reveals, and a review action for every miss. Use four four-minute lanes for a 16-minute first pass: nonprofit donor purpose, income-tax basis, subsequent-event timing, and government reporting perspective. Score the process from 0–12 for study routing only. The number is not an exam score or a result prediction.
Scope and originality note: This set is for US CPA candidates. It uses the AICPA Blueprint as its October 3, 2026 scope checkpoint. Every question, amount, answer choice, rationale, and changed-fact retry is independently authored. The set is not an official exam form. The editorial review role is scope mapping and source QA, not a personal licensure claim.
Reopen the AICPA CPA Exam Blueprint for tested scope. Use current FASB Topic 740, Topic 855, and Topic 958 for the relevant research routes. Government-accounting questions need current GASB guidance. The AICPA sample tests can help with interface familiarity, while the NASBA CPA Exam FAQ covers administration.
Timed FAR nonprofit accounting practice
This timed FAR nonprofit accounting set tests the first move, not endurance alone. Each lane gives you a skill, assumptions, difficulty, and four minutes. Read the stem, select an answer, and write one sentence naming the controlling trigger before opening the rationale.
The four lanes deliberately cross topic boundaries. A donor-purpose item asks what wording controls classification. An income-tax item asks what basis comparison comes before the rate. A subsequent-event item asks what condition existed at the reporting date. A government item asks which reporting perspective the prompt names. The fifth transfer item checks whether you repair the first broken field before repeating a stable calculation.
Set the 16-minute run
- Minute 0: write the four lane names and keep the source links closed.
- Minutes 0–4: attempt the nonprofit item.
- Minutes 4–8: attempt the income-tax item.
- Minutes 8–12: attempt the subsequent-event item.
- Minutes 12–16: attempt the government item.
Do not open a rationale between lanes. Mark a guessed answer with a question mark. That mark distinguishes recognition from a defensible route. After the clock, use the fifth transfer item without a timer to see whether the reasoning carries to a changed fact.
A short set is not a complete FAR diagnosis. It is a repeatable sample. Run it again after a repair block, but change at least one fact so that memorized letters cannot carry the result.
Use the four-lane process
Give every answer three fields. Start with the choice. Next record the trigger or calculation. Finish with the next action. A correct choice with no trigger earns only the choice point. A wrong choice with a precise trigger still tells you where to begin repair.
- Nonprofit: write the donor phrase that controls the classification.
- Income tax: write the carrying amount, tax basis, difference, and stated rate in that order.
- Subsequent events: write the reporting date and the condition date separately.
- Government: write the requested statement level or named fund before analyzing the transaction.
This process prevents answer-only review. It also makes the next block narrow enough to complete. If you cannot write the trigger in one sentence, do not add more questions yet.
Original practice item 1 — Donor purpose
Skill: identify the classification trigger. Assumptions: no additional donor agreement exists. Difficulty: foundational. A nonprofit receives $84,000. The donor states that $24,000 supports a youth program. What should you identify first?
- Classify the entire receipt from cash evidence alone.
- Separate the stated purpose from the amount with no donor-purpose direction.
- Apply the income-tax rate used in the next item.
- Move the receipt to the government lane.
Reveal the answer and rationale
Answer: B. Donor wording is the first trigger. In this simplified item, the stated purpose attaches to $24,000 and the remainder has no stated donor-purpose direction. The cash amount cannot replace the restriction. Choice C uses an unrelated calculation. The final option changes the topic. Next action: remove the youth-program phrase and restate which portion changes. Reopen Topic 958 before using the shortcut with complete facts.
Original practice item 2 — Tax basis
Skill: sequence a temporary-difference calculation. Assumptions: apply the stated 25% rate only after finding the difference. Difficulty: moderate. An asset has a $132,000 carrying amount and a $92,000 tax basis. Which calculation comes first?
- $132,000 × 25%.
- $92,000 × 25%.
- $132,000 − $92,000.
- $132,000 + $92,000.
Reveal the answer and rationale
Answer: C. First calculate the $40,000 book-versus-tax difference. Applying 25% afterward produces $10,000 in this bounded example. Applying the rate to the carrying amount creates the first error. Choice B applies it to the tax basis. The final option never establishes the difference. Next action: change the tax basis to $102,000 and recalculate before applying the rate. Reopen Topic 740 for the complete recognition and measurement analysis.
Original practice item 3 — Subsequent event
Skill: separate a later discovery from the reporting-date condition. Assumptions: a customer enters bankruptcy after year-end, and evidence shows financial difficulty before year-end. Difficulty: moderate. What is the first question?
- Whether the later event provides evidence about the reporting-date condition.
- Whether every later event is ignored.
- Whether donor wording controls the customer balance.
- Whether a governmental fund perspective controls the timing.
Reveal the answer and rationale
Answer: A. Start with the condition at the reporting date. Later information may provide evidence about that earlier condition. Choice B treats every later event identically. Choices C and D route the fact into other lanes. Next action: move the financial difficulty to after year-end and write the changed research question. Reopen Topic 855 for the live conclusion.
Original practice item 4 — Government perspective
Skill: select the requested reporting perspective. Assumptions: the prompt names a governmental fund and does not request government-wide statements. Difficulty: foundational. What should you do before analyzing the transaction?
- Use the named governmental-fund perspective.
- Switch automatically to government-wide statements.
- Apply the nonprofit donor-purpose rule.
- Calculate the temporary difference from item 2.
Reveal the answer and rationale
Answer: A. The named fund is the first routing fact. Choice B changes the requested reporting level. Choices C and D are unrelated topic moves. Next action: rewrite the question to request government-wide statements, then name the new perspective before researching. Reopen current GASB guidance for a complete conclusion.
Original practice item 5 — Transfer repair
Skill: choose the first repair when a calculation is stable but the reporting route is wrong. Assumptions: a learner correctly finds a $40,000 difference but analyzes a governmental-fund prompt using the government-wide perspective. Difficulty: transfer. Which action comes first?
- Repeat the $40,000 subtraction without changing the prompt.
- Rebuild the named reporting perspective, then rerun the analysis.
- Read every FAR topic before attempting another item.
- Convert the result into a predicted exam score.
Reveal the answer and rationale
Answer: B. The arithmetic is stable. The perspective error can change which facts matter, so repair the route before repeating the subtraction. Repeating the subtraction rehearses a sound step. Choice C is too broad to guide a session. A predicted result is not a study measure. Next action: hold the amount constant, change only the requested statement level, and state which analysis step changes.
Use the 16-minute scorecard
Score each of the four timed items with three process points. Award one point for the selected choice. A second point records a correct trigger or calculation. A third point records a specific next action. The maximum is 12 points for study routing only. The fifth transfer item is a separate check and does not need to inflate the total.
Use the result as a queue. A low choice point with no trigger calls for a rebuild. A correct choice with a weak calculation or date explanation calls for targeted repair. When the first pass is strong but the changed-fact transfer is weak, choose replay. The useful question is “What field broke first?” rather than “What score did I get?”

Move each miss into a review queue
Write one row per miss. Name the lane, the first broken field, the source route, the fact you will change, and the first retry action. Keep the retry bounded. One donor-wording rewrite, one basis recomputation, one date shift, or one statement-level change is enough for the next block.
A queue protects the next session from becoming a second timed test. If the same field breaks twice, keep the lane. If the field stabilizes after one changed fact, mix it with a neighboring lane. The route should respond to evidence from this set.

Run a second timed attempt
Wait until the repair block is complete, then rerun the four-lane clock. Change one fact in every item. Change the donor purpose wording, move the tax basis, move the financial difficulty across the reporting date, or change the requested statement level.
Compare three results: choice, reasoning, and transfer. A repeated letter is not enough. The explanation should name the controlling fact, and the changed-fact answer should show whether the route moves. Record one sentence for each comparison.
This second pass is where a timed FAR nonprofit accounting routine becomes useful. The clock stays fixed, while the evidence changes. That combination separates speed from memorization.
Keep the set source-aware
The Blueprint controls scope. FASB Topics 740, 855, and 958 provide research routes for the three accounting lanes. Current GASB material controls the government lane. The items here simplify facts for practice and do not replace current literature.
Before reuse after a scope or standards change, reopen the AICPA Blueprint, Topic 740, Topic 855, Topic 958, and GASB. Use the AICPA sample tests for interface familiarity, and send administration questions to NASBA.
For a repeatable timed FAR nonprofit accounting session, preserve the same order: attempt, trigger, rationale, next action, changed fact. This is a review method, not a promise about an exam outcome.
Timed FAR nonprofit accounting FAQ
How long should the first attempt take?
Use four minutes per lane for a 16-minute first pass, then reveal the rationales after the clock.
What does the 0–12 total mean?
It routes study work through choice, trigger or calculation, and next-action fields. It is not an exam score.
What should I change on the second attempt?
Change one fact in each lane: donor wording, tax basis, condition date, or requested statement level.
How should I review a missed item?
Record the lane, first broken field, source route, changed fact, and one bounded retry.