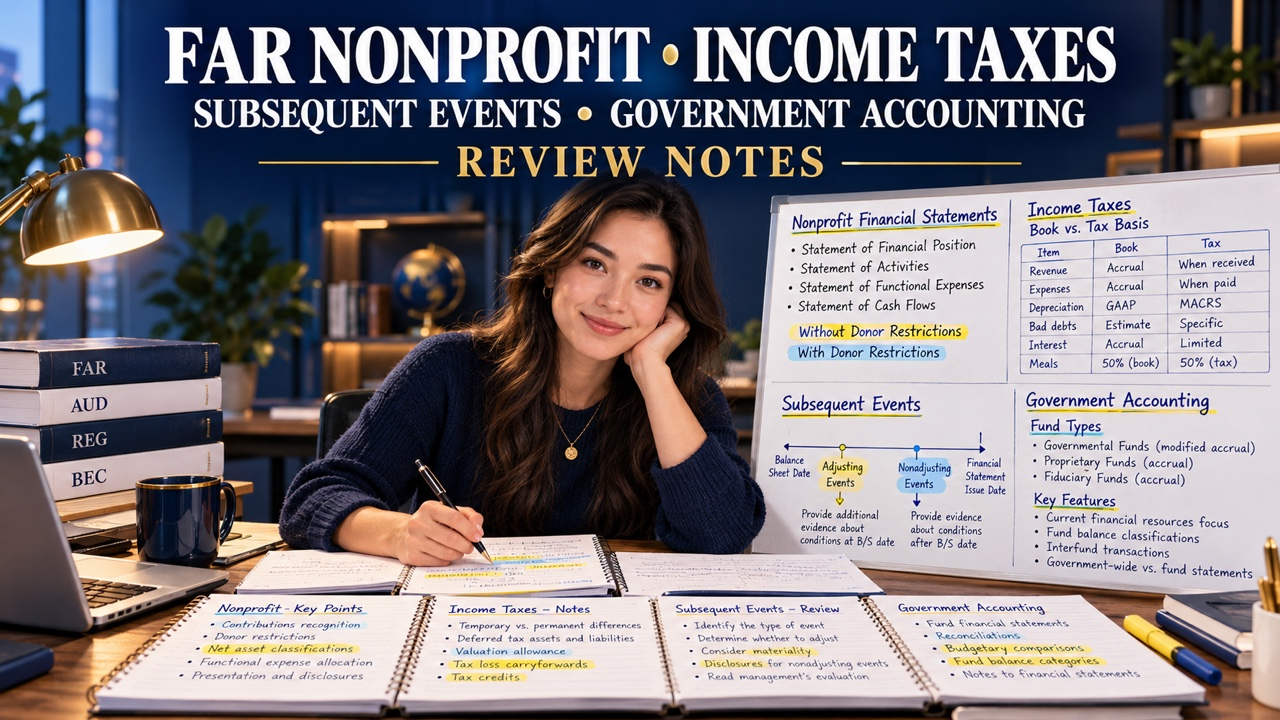

Direct answer: Use nonprofit taxes subsequent review as an evidence notebook, not as a list of loose reminders. For every item, write the requested verb, the reporting lane, the date that controls the analysis, the fact that could redirect it, and the record that would settle the point. Then change one fact and explain whether the conclusion moves. These are original editorial examples for FAR learners.
Scope checkpoint: Recheck the AICPA CPA Exam Blueprints for current task language and topic boundaries. Use the NASBA CPA Exam FAQ for eligibility, jurisdiction, scheduling, and score administration. The amounts below are simplified learning facts.
For section orientation, open the FAR review hub. The CPA study guide helps with sequencing, the Blueprint format guide clarifies task verbs, and the topic MCQ page or TBS practice guide gives you a different retrieval mode.
Nonprofit taxes subsequent review: build the note around the verb
Begin with the task word rather than the loudest number in the stem. First, a classification request needs an entity boundary and a restriction record. Next, a measurement request needs a dated amount, a basis, or a reversal path. Meanwhile, an assessment request needs the underlying condition and the rights attached to it. Finally, a disclosure request needs the information available before issuance plus the context a reader needs.
Write that verb in the margin. Then, beside it, write the lane: nonprofit resources, income taxes, subsequent events, or government accounting. However, if an option borrows vocabulary from another lane, the margin note makes the switch visible before it becomes a mistake.
Nonprofit taxes subsequent review five-line note
Give each item five lines: requested verb, controlling date, redirecting fact, proof limit, and next record. In practice, the redirecting fact answers “what could change the route?” The proof limit answers “what does this fact fail to prove?” Finally, the last line names the agreement, reconciliation, chronology, budget document, or other exhibit you would inspect.
For instance, a donor purpose can show why funds are restricted, but it cannot show that a purchase occurred. A tax schedule can show a temporary difference, but it cannot by itself prove the recovery pattern. A later engineer report can describe damage, but it does not settle whether the condition existed at the reporting date.
Set the nonprofit taxes subsequent review boundary
Write the reporting date at the top of the page. Next, under it, copy the task verb and select one lane for the round. Afterward, list the minimum evidence you would accept before choosing an answer. Finally, add a stop rule: if the fact depends on a purpose clause, basis reconciliation, event chronology, or legal budget authority, pause and open that record.
For nonprofit taxes subsequent review, keep the four lanes in separate columns. First, in the nonprofit column, track purpose, availability, spending, and release. Next, in the tax column, track carrying value, tax basis, temporary difference, and expected reversal. Meanwhile, in the subsequent-event column, track condition date, discovery date, and issuance date. Finally, in the government column, track activity, resource flow, and legal boundary.

Use an evidence ledger, not a score log
Write the stem in one sentence. Next, write the movable fact and the fact that stays fixed. Then, name the document that would confirm each one. As a result, this ledger tells you whether a missed answer came from scope, timing, measurement, or evidence rather than reducing every miss to “review more.”
A short comparison pass
First, spend one minute extracting the verb, one minute marking the lane, two minutes testing the controlling fact, and one minute naming the record. Afterward, state the conclusion in one sentence and state its limit in a second. Therefore, this rhythm keeps a review note useful after the first reading.
Read three original nonprofit taxes subsequent review cases
First, attempt the cases cold. However, do not open the rationale until you have written the verb, lane, controlling date, and record. Meanwhile, the scenarios are original and simplified; they are not official, recalled, leaked, or exam-memory questions.
Reveal the review reasoning
Attempt each original case, write the five-line note, then reveal the rationale and mark one missing record.
Reveal the answer
Answer: The strongest route names the verb, lane, controlling date, proof limit, and record to inspect.
Compare your process with the reasoning shown above.
Case 1: a grant with a service condition
Facts: Harbor Youth Services receives $68,000 for a two-year nutrition program. For this case, the agreement permits spending through the following June if the program continues. Next, at year-end, $21,000 remains, and the ledger shows $47,000 of eligible meals and supplies. Therefore, the question asks which evidence supports the classification of the balance.
Options: A. Call the balance unrestricted because the spending window is long. B. Read the service condition and extension clause, trace the ledger, and classify the balance in the correct lane. C. Treat the balance as a tax basis. D. Place it in a governmental fund.
Answer and rationale: As a result, B follows the agreement and the ledger. The extension changes the timing of allowable use; it does not erase the service condition. Save both records before deciding the presentation.
Case 2: a tax basis that reverses through use
Facts: Meridian Arts reports equipment at $184,000. Meanwhile, tax depreciation has been faster, so the tax basis is $139,000. Therefore, the difference is expected to unwind as the equipment is used. Next, the task asks which analysis comes first.
Options: A. Use the financial-statement amount alone. B. Reconcile carrying value to tax basis, identify the reversal pattern, and assess the deferred-tax route. C. Treat the difference as a later event. D. Classify it as donor-restricted support.
Answer and rationale: As a result, B connects the recorded amount, tax basis, and expected recovery. The reconciliation and depreciation schedule provide a stronger trail than a single balance. The other answers move the fact into the wrong lane.
Case 3: information received before issuance
Facts: First, Silver Creek County closes on September 30. Next, on October 18, an engineer confirms that a retaining wall failure observed in October began before September 30. Afterward, the statements will be issued in December. The task asks which timing question starts the review.
Options: A. Ignore the report because it arrived after close. B. Ask whether the report confirms a condition that existed at September 30, then route recognition or disclosure. C. Treat it as restricted nonprofit support. D. Record every October report as a new fund.
Answer and rationale: Therefore, B starts with the reporting-date condition and information available before issuance. The arrival date alone is not the rule. Keep the inspection chronology, engineer report, and board review together.
Separate restriction evidence from tax evidence
First, recognition, presentation, and disclosure are different verbs. First, recognition asks whether a reporting-date condition qualifies and can be measured. Next, presentation asks where the amount belongs. Finally, disclosure asks what a user needs to understand about uncertainty or commitments. Therefore, mark the verb before reading the distractors.
Nonprofit taxes subsequent review restriction trail
First, for a nonprofit resource, walk from purpose to availability to spending to release. Next, put one record beside each step. However, an agreement may establish purpose and an extension; a spending ledger may establish use. Therefore, neither document automatically proves the other step.
Nonprofit taxes subsequent review tax bridge
Meanwhile, for income taxes, write the carrying amount on the left, the tax basis in the center, and the expected reversal on the right. Then, under the bridge, add the task verb. However, if the question asks for a tax route, do not let a familiar restriction shortcut replace the basis analysis.
Next, perturb one input. Then, change the recovery period, change the basis, or change the permitted use. Record which conclusion moves and which records remain fixed. As a result, that single replay is more informative than another page of undifferentiated notes.
Trace later information and government boundaries
First, draw three dates in order: condition, discovery, and issuance. Next, ask whether the later document confirms an earlier condition, creates a new one, or supplies context. Finally, connect the answer to the exact task verb. However, a later signature is evidence, but it is not a substitute for the condition test.
Government activity check
First, start with the service, resource flow, and legal authority. Next, ask whether the question concerns fund reporting, government-wide presentation, a budget comparison, or event timing. Therefore, a familiar fund label does not decide the measurement focus.
For nonprofit taxes subsequent review, keep the transfer explicit: change the budget authority, move the condition after year-end, or change the donor purpose. Meanwhile, hold the other facts steady. Finally, name the document that would prove the new route.
Choose one review repair
First, after the cold attempt, classify the first gap as scope, fact, rule, evidence, or transfer. Next, pick one repair and set a boundary around it: annotate one agreement, rebuild one tax bridge, redraw one chronology, or map one government activity. Finally, replay one case after changing one material input.

Transfer ledger
First, use three columns: changed input, held-steady facts, and record to inspect. Next, try a new service purpose while holding spending fixed; change the tax recovery pattern while holding carrying value fixed; move the discovery date while holding issuance fixed. As a result, the ledger shows why the route changed.
Close the nonprofit taxes subsequent review notebook
First, end with the Blueprint checkpoint, task verb, controlling fact, rejected shortcut, and next record. Next, keep official scope statements separate from these original cases. Finally, recheck AICPA material when task language changes and NASBA material when administration details change.
Ten-minute close
First, minute one copies the verb. Next, minutes two and three mark the lane and controlling date. Then, minutes four through six test the proof limit. Afterward, minutes seven and eight run the changed-input replay. Finally, the final two minutes schedule the document check. As a result, the next session begins with a concrete question.
For the next route, when a document drives the decision, switch to the TBS practice guide. When narrow recall is the problem, use the topic MCQ page. Each route changes the next action while the notebook preserves the reasoning.
nonprofit taxes subsequent review checklist
- Copy the checkpoint date and requested verb.
- Circle one lane: nonprofit, tax, subsequent event, or government activity.
- Mark the fact that could redirect the route.
- Write what that fact cannot prove.
- Name the agreement, reconciliation, chronology, or budget document to inspect.
- Explain why the closest shortcut fails.
- Change one material input and replay the case.
- Schedule the next record check.
Overall, strong nonprofit taxes subsequent review leaves a replayable notebook. The learner can show what was asked, what moved the route, which record supports it, and what changes after one transfer.
nonprofit taxes subsequent review FAQ
Are these official exam questions?
No. The cases and explanations are original editorial practice. Use current AICPA material for authoritative scope and terminology.
Does an extension erase a service condition?
No. Read the agreement and the spending trail; an extension changes timing but does not erase a named condition.
Does a later report always change the prior period?
No. First ask whether the underlying condition existed at the reporting date and what was known before issuance.
What follows a missed review case?
Name the missing record, inspect one document, and replay one case after changing one material input.
Sources and scope
Reopen official sources before publication or reuse because testing boundaries and administration details can change. This page uses simplified amounts and original examples; it is not a live engagement conclusion or a score promise.