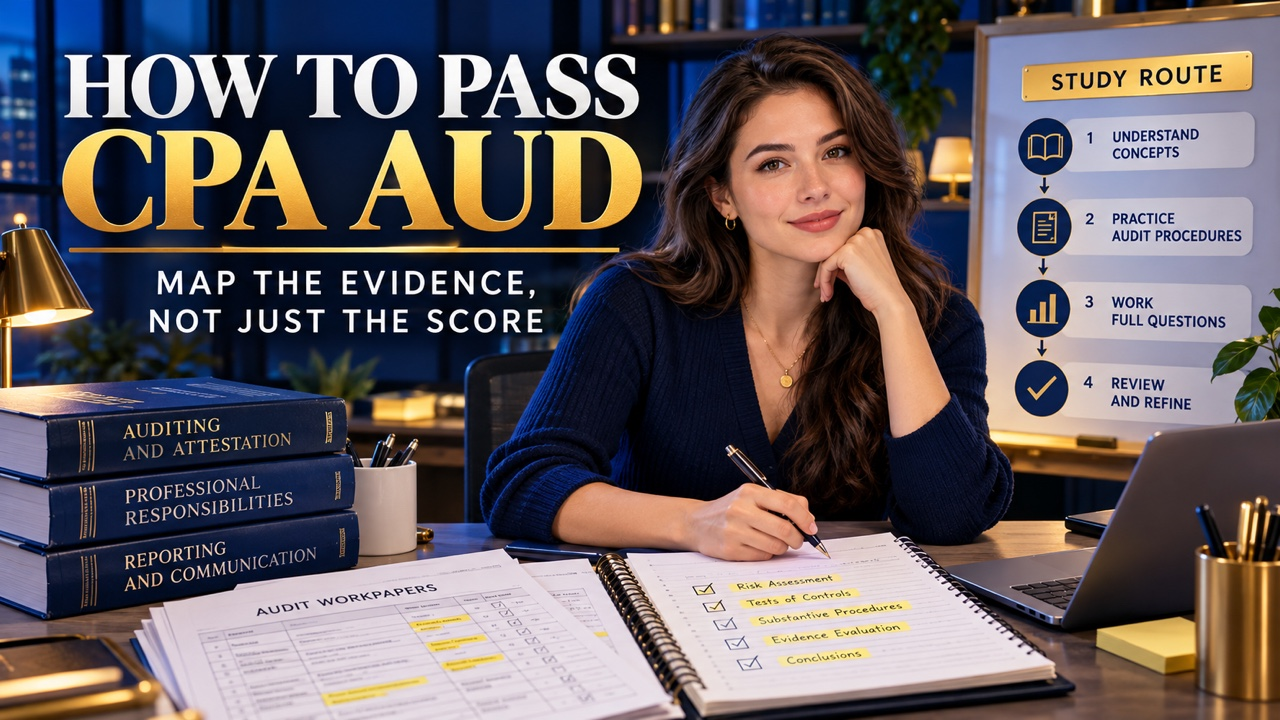

Direct answer: To learn how to pass cpa aud, stop treating AUD as a stack of chapters. Run a short evidence-first loop: choose one task from the current Blueprint, predict the auditor’s judgment, solve a bounded question, explain which fact or procedure carried the answer, change one fact, and schedule the next repair. The loop tells you what to study next because every miss leaves a visible proof gap.
Scope and freshness: This is original study guidance for US CPA candidates. It is not an AICPA or NASBA publication, an audit opinion, a client conclusion, a score forecast, or jurisdiction-specific advice. Reopen the AICPA CPA Exam Blueprints, AICPA AUD resources, and the NASBA CPA Exam FAQ before relying on a changing boundary.
Use the AUD review hub to see the section’s lanes. Open the Blueprint format guide when a task statement is hard to parse. Choose the MCQ-by-topic route for recognition and discrimination. Choose the TBS practice route when the work requires exhibits, calculations, or a constructed response.
how to pass cpa aud: use an evidence-first loop
AUD rewards disciplined judgment more than heroic reading hours. Begin each block by writing four items: the engagement or topic, the task verb, the fact that could change the result, and the evidence you would need to defend the result. Then select a small set that tests that exact judgment. Afterward, write the reason the best alternative fails. That explanation is the useful output; a percentage alone cannot show it.
This method also keeps a section page in its proper role. It points you toward the right kind of practice without pretending to reproduce official questions. The Blueprint supplies scope and task language. Your notes supply the reasoning trail. Your next practice item supplies the transfer check.
Start with the AUD verb, not the chapter label
Chapter names are broad. The verb in the task statement is narrower and tells you what a response must do. Translate the next task into one of these working prompts before you study:
- Identify: name the condition, assertion, control, or report element that fits the facts.
- Evaluate: compare evidence or risk against a stated criterion and explain the difference.
- Determine: apply a threshold, responsibility, or procedure to a specific situation.
- Calculate: show the inputs, method, and unit before selecting a result.
- Explain: connect a conclusion to evidence, limitation, and professional judgment.
- Recommend: choose the next procedure or communication while stating the reason and boundary.
For example, “controls” is not one study task. A question may ask you to identify a control deficiency, evaluate a test of operating effectiveness, or recommend a response to a risk. Those verbs require different evidence. Put the verb in the margin of your note so you do not practice recognition when the target is evaluation.
Build a one-page AUD working paper
Before opening a large question bank, make a one-page working paper. Leave a blank line after each field so the page records uncertainty rather than hiding it.
- Scope: copy the Area, topic, task statement, skill level, and item type from the current Blueprint release.
- Trigger: write the role, date, service, assertion, criterion, amount, or system fact that can move the answer.
- Expected output: state whether you must classify, calculate, evaluate, identify, explain, or recommend.
- Evidence: name the document, procedure, control, exhibit, or reporting language that would support the output.
- Boundary: record what the note does not establish, such as a client conclusion, official score, or state rule.
Keep the paper beside the practice item. If you cannot fill one field, do not cover the gap with another mixed set. The blank field tells you whether to reread scope, review a concept, or practice an evidence assembly task.
Run the AUD study loop in four passes
Use the following sequence for a 30–45 minute block. The order matters because it separates understanding from speed.
- Frame: select one task and underline the verb. Write the trigger that would make the conclusion different.
- Attempt: solve one or a few items with the reference material closed. Record the evidence you used, not only the letter you selected.
- Explain: state why the strongest distractor fails. If your explanation names a rule but not the fact that activates it, mark that as an incomplete proof.
- Vary: change one material fact and decide whether the procedure, conclusion, report, or next step changes. Schedule the first unchecked field for the next block.

The route is deliberately small. A compact trace that another learner can follow is more valuable than a long page of highlighted definitions. When the same trigger produces different answers, place the two facts side by side and ask which evidence moved the judgment.
Use the evidence-first checklist
At the end of the block, mark only the decisions you can defend from the task record. The first blank chooses the next repair; it is not a score.
Choose practice by the output you must produce
Use MCQ practice when the target is a clean distinction: two plausible rules, two evidence types, or two responsibility lines. After answering, write one sentence about the distractor that almost worked. That sentence reveals whether you misread the stem or confused a boundary.
Use a TBS-style exercise when the target requires several fields to work together. Build a small workpaper with the exhibit, calculation, reconciliation, or report wording in view. AUD TBS practice is useful when you can recite a definition but cannot connect evidence to a conclusion. The goal is not to simulate an official exam form; it is to make the missing handoff visible.
how to pass cpa aud: match the proof format to the gap
If the gap is vocabulary, make a short identification set. For a risk-response gap, compare two procedures and state which risk each addresses. When report wording is the issue, draft the conclusion and cite the condition that changes the paragraph. For evidence assembly, use a workpaper or exhibit-based task. Therefore, a larger set in the wrong format only creates a larger, less useful log.
Diagnose a miss without chasing a score
Label every miss with one cause before moving on:
- Scope miss: you studied a neighboring topic or misread the task statement.
- Trigger miss: you saw the right topic but ignored the fact that activated a different response.
- Evidence miss: you chose a conclusion without identifying the procedure, document, or criterion that supports it.
- Transfer miss: you knew the rule but could not assemble the requested output under a changed fact.
- Communication miss: your conclusion was plausible, but the explanation omitted the limitation or responsibility boundary.
Write the label next to the item and save the first missing proof point. A local accuracy rate can be useful for pacing, but it is not an official CPA score or a readiness determination. The explanation and changed-fact retry are stronger evidence of what to do next.
how to pass cpa aud: plan the next repair block
Turn the first missing proof point into a narrow appointment. “Review controls” is too broad. “At 7 p.m., compare design versus operating effectiveness for one current Blueprint task, then explain why one alternative procedure would not address the stated risk” is specific enough to complete and check.
Use a two-day rhythm when a topic keeps recurring. On day one, reopen the relevant source and create the working paper. On day two, run a short MCQ or TBS task with one changed fact. Keep the source checkpoint and the unresolved question in the margin. This prevents a remembered summary from silently becoming a current professional conclusion.
If your block ends with several blanks, repair only the earliest handoff. Once the trigger is clear, the correct practice format is usually easier to choose. Once the proof format is clear, speed can be measured without confusing speed with certainty.
how to pass cpa aud: keep the AUD record usable
Use plain labels in your record: topic, verb, trigger, evidence, conclusion, and next action. Avoid a page of shorthand that only makes sense while the item is open. At the end of the week, skim the records and circle the trigger that appears most often in your misses. That circle gives you a better revision target than a long list of chapter names.
When timing is the problem, preserve the same record and shorten the item set. If explanation is the problem, leave the clock off and require a complete evidence sentence. When the source is unclear, stop the set and verify the boundary. Meanwhile, changing one variable at a time keeps the repair measurable.
how to pass cpa aud: route to the next CPA resource
Let the first blank on your working paper choose the next page. Open the AUD review hub when you need the section map. Next, read the Blueprint format guide when the task or skill level is unclear. For rule boundaries and distractor reasoning, choose CPA MCQ by topic. For exhibits and constructed outputs, choose CPA TBS practice. Finally, the CPA study guide can hold the broader schedule after the immediate gap is named.
Close the block by writing one row, one output, one fact to vary, and one artifact to save. That is a useful answer to how to pass cpa aud: the next action is visible, bounded, and easy to audit.
how to pass cpa aud FAQ
Should I read the entire AUD section before practicing?
No. Start with one task statement and a bounded evidence question. Expand only after the working paper shows which neighboring topic matters.
How many questions should one study block contain?
Use enough items to test the same judgment and explain a distractor. A small, well-labeled set is more useful than a mixed count that hides the cause of a miss.
When is a TBS-style task the better choice?
Choose it when the requested answer needs multiple exhibits, a calculation, a reconciliation, or a constructed communication. Use MCQ when a single distinction is the missing proof.
Does a high practice percentage mean I will pass?
No. A practice percentage is local evidence, not an official score or readiness decision. Save the reasoning, the strongest distractor, and one changed-fact result.