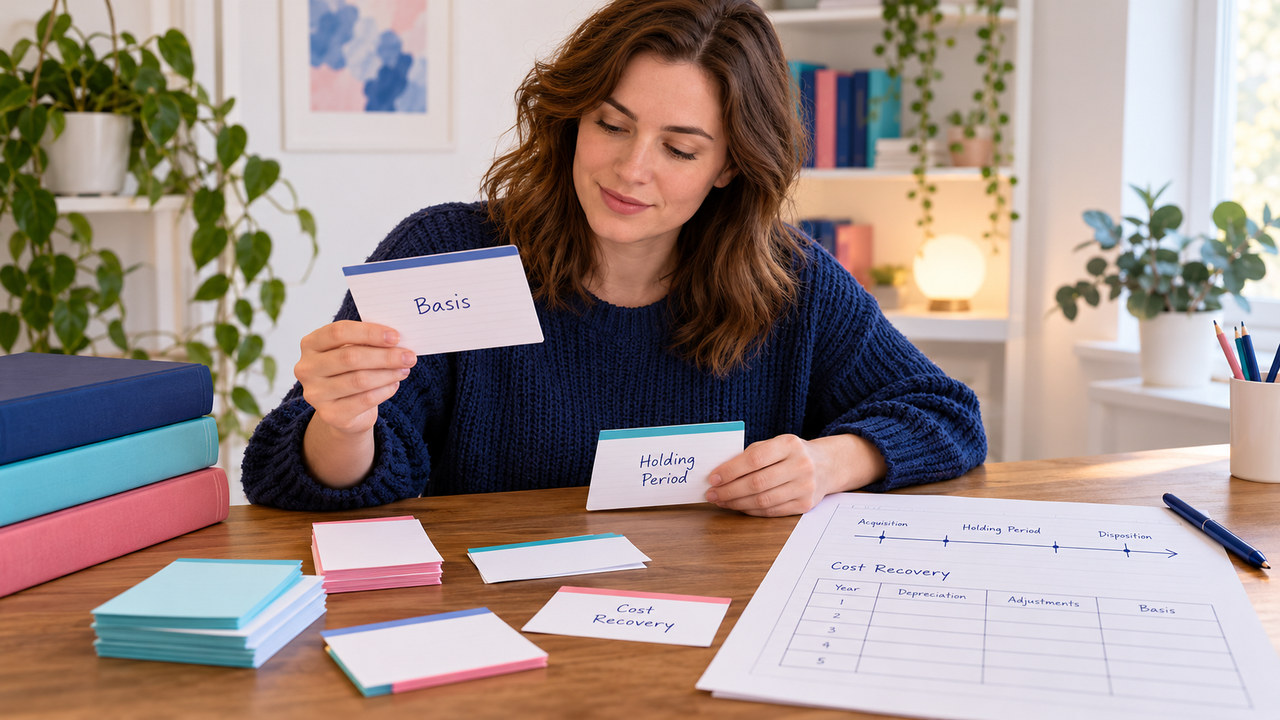

Direct answer: Use basis holding period flashcards as a three-part tax fact drill. Put the amount on a basis ledger, put dates on a holding-period line, and mark the placed-in-service or recovery fact before you choose a tax result. Then explain the strongest distractor and retry after changing one fact. The page is original study material, not an official or recalled exam set.
Scope note: The AICPA CPA Exam Blueprints identify tested content, task statements, skill levels, references, and item types. Reopen the AICPA CPA Exam resources for the current testing window. Use the NASBA CPA Exam FAQ for jurisdiction, eligibility, scheduling, and score administration. The examples below simplify facts so the reasoning signal stays visible.
Start with the REG review hub when you need section orientation. Use the CPA study guide for a broad plan, the Blueprint format guide for task boundaries, and the topic MCQ page or TBS practice guide when the next weak signal is retrieval or exhibits.
For a broader preparation path, continue with our related CPA study resources.
REG basis holding period flashcards: a three-clock method for cost recovery
The title skill is a classification-and-explanation task. A prompt may mention a sale, an improvement, a pass-through, or a deduction, yet the controlling fact can sit in a different lane. Before touching an answer choice, ask three questions: What number belongs in the basis ledger? Which date starts or ends the holding period? Which event puts property into service or changes the recovery treatment?
Keep the practice facts deliberately narrow. A ledger is a record of cost and adjustments; a clock is a record of dates; a recovery lane is a record of the tax treatment triggered by the asset or activity. Do not let a familiar word such as “sale” substitute for the actual fact the item tests.
Difficulty and working assumptions
Begin at moderate difficulty with one material twist per item. The figures below are teaching numbers, not a substitute for current law, a return position, or professional advice. Where the prompt would normally require a convention, limitation, jurisdiction, or current threshold, the scenario says so. Your job is to identify the missing proof point and state what source or exhibit you would reopen.
For a clean attempt, use a four-line note: ledger, clock, recovery trigger, and tax effect. If one line is blank, that blank is the next review action. That simple rule is the operating system for reg basis holding period and cost recovery flashcards.
Build the tax fact strip for basis holding period flashcards
Write the transaction in plain language first. “A taxpayer sold an improved asset” is a starting sentence, not an answer. Add the original cost, later capitalized work, prior recovery, ownership or entity, relevant dates, and the requested output. Then circle the one fact that would change the result if it moved.
- Ledger: start with cost, add qualifying capital items, and subtract the simplified recovery amount stated in the prompt.
- Clock: record acquisition, placed-in-service, transfer, and disposition dates separately; do not merge them into one “purchase date.”
- Recovery trigger: identify the event that begins the recovery period and the class or convention the question gives you.
- Tax effect: state whether the requested output is basis, gain or loss, timing, deduction, credit, or an entity-level responsibility.
That strip lets you see why two answer choices can sound plausible. One may use the right number with the wrong date. Another may use the right date but skip an adjustment. The explanation should expose that mismatch rather than merely announce a letter.

Run basis holding period flashcards as original prompts
Attempt each prompt before revealing the rationale. Write the four-line fact strip, select the controlling lane, and name the distractor you almost chose. These are original practice items for the page; they are not official, recalled, leaked, or exam-memory questions.
Reveal the reasoning
Attempt the original item first. Write the controlling fact, the boundary or evidence check, and the reason you would save before opening the explanation.
Reveal the answer
Answer: Compare your note with the rationale, mark the first missing proof point, and change one fact before retrying. Do not use a raw answer letter as the study record.
Compare your process with the reasoning shown above.
Prompt 1: the improvement belongs in the ledger
Front: Under a simplified fact pattern, a taxpayer buys an asset for $100,000, adds a qualifying improvement for $20,000, and has $10,000 of stated prior recovery before the sale. Which figure should the learner carry into the adjusted-basis comparison?
- $100,000, because the purchase invoice is the only original document.
- $110,000, because the improvement increases the ledger and the stated recovery reduces it.
- $120,000, because recovery never changes basis.
- $90,000, because the improvement is ignored after the asset is placed in service.
Pause here: write the ledger expression and the fact that would make the improvement nonqualifying. Do not use an answer letter as the study record.
Prompt 2: the clock needs two dates
Front: A property file lists an acquisition date, an in-service date after a later improvement, and a sale date. The question asks for a holding-period conclusion under a stated threshold. Which first move produces the most reliable review note?
- Use the month names and assume the clock ran from the first invoice.
- Choose the longest date range so the result feels conservative.
- Lay out the relevant start and end dates, then compare the stated threshold to the date pair the question actually asks about.
- Ignore the improvement date because only the sale date is visible.
Pause here: identify which date pair the requested tax result uses and why the other dates remain relevant evidence.
Prompt 3: placed in service controls the recovery lane
Front: A business orders equipment in March, receives it in April, and begins using it in June. The prompt asks when the recovery period begins under a simplified convention supplied in the stem. What should the learner anchor?
- The order date, because it proves intent.
- The payment date, because cash left the account.
- The event the stem identifies as the placed-in-service trigger, then the given convention or class.
- The first tax return filing date, because that is when the deduction is claimed.
Pause here: write the trigger in your own words and state which fact would move the start date.
Reveal the answer: ledger, clock, recovery lane
Now compare your notes with the reasoning. A useful reveal names the controlling fact, the boundary that gives it meaning, and the shortcut that fails. That order is the heart of reg basis holding period and cost recovery flashcards: front-side cue, back-side proof, then one changed-detail retry.
Prompt 1 answer and distractors
Best answer: 2. Under the simplified facts, adjusted basis is $100,000 + $20,000 − $10,000 = $110,000. Choice 1 freezes the ledger at original cost. Choice 3 adds the improvement but forgets the stated recovery. The final distractor subtracts recovery while discarding the improvement. The saved proof point is the improvement document plus the recovery amount, not the answer letter.
Prompt 2 answer and distractors
Best answer: 3. The dates must be placed on a line before the threshold is compared. Choice 1 treats an invoice month as a legal conclusion; choice 2 changes the question; choice 4 discards evidence that may explain a separate holding or recovery issue. The saved note should state the exact date pair used for the requested conclusion and the date that remains a possible changed fact.
Prompt 3 answer and distractors
Best answer: 3. The stem’s placed-in-service trigger and supplied convention control this simplified recovery exercise. Ordering, payment, and filing can be relevant records, but they do not replace the trigger stated in the question. The saved note should say “trigger first, convention second,” then flag the event that would change the start.
Notice the pattern: the correct response is a sequence, not a memorized slogan. A basis error lives in the ledger; a holding-period error lives in the clock; a cost-recovery error lives in the trigger. If the three lanes are mixed, the explanation should tell you which lane to reopen.
Change one fact in basis holding period flashcards
A flashcard becomes useful when the back side survives a controlled change. Keep all facts fixed except one, predict whether the answer changes, and explain the reason. Use the second visual as a compact evidence board: the fact strip, the changed field, the new decision, and the repair action should remain visible in one frame.

Try these transfer checks after the three reveals:
- Keep cost and recovery fixed but remove the qualifying improvement. The ledger changes; the clock does not. State which answer lane moves.
- Keep the dates fixed but change the question from holding period to placed-in-service timing. The date line remains evidence, yet the controlling trigger changes.
- Keep the asset facts fixed but move the taxpayer into a different entity context. Reclassify who reports the item before discussing a deduction or credit.
When your prediction is wrong, do not restart the whole REG chapter. Tag the first broken lane as ledger, clock, trigger, or entity. Then reopen one authoritative scope source or one worked exhibit and write a fresh sentence before trying another item.
Choose the next repair from basis holding period flashcards
Use a bounded repair: one source check, one rewritten rule sentence, and one new prompt with one changed fact. For example, if the clock was blank, draw the three dates again and answer a date-pair question. If the ledger was wrong, rebuild the additions and subtractions without changing the taxpayer. If the trigger was unclear, write the event that begins recovery and the convention supplied by the stem.
This is where reg basis holding period and cost recovery flashcards earn their place in a study plan. They make the next action observable. A correct answer with no explanation is a weak record; a wrong answer with a precise first-gap tag can produce a strong review block.
Make basis holding period flashcards repeatable
At the end of a session, keep one compact log rather than a long narrative. Record the prompt label, the four-line fact strip, the selected option, the nearest distractor, the source or exhibit checked, and the changed fact used for transfer. Add a date when the source boundary may change. The log should make tomorrow’s first question obvious.
- Choose one narrow basis, holding-period, or cost-recovery skill.
- Write the taxpayer, asset or item, dates, and requested tax effect.
- Complete ledger, clock, trigger, and entity lines before the reveal.
- Explain why the strongest distractor fails.
- Change one material fact and predict the new result.
- Schedule one repair that matches the first blank line.
Keep official scope separate from original practice. The AICPA and NASBA links set boundaries and administration routes; the examples, rationales, visual boards, and repair method here are editorial study aids. Reopen the live sources before relying on a current rule, threshold, or jurisdiction detail.
basis holding period flashcards checklist
- Did I write the requested output before calculating?
- Did I separate original cost, later capitalized work, and stated recovery?
- Did I place acquisition, in-service, transfer, and sale dates on a line?
- Did I identify the trigger and convention named by the prompt?
- Did I explain the strongest distractor in a complete sentence?
- Did one changed fact produce a new answer or a defensible unchanged result?
- Did I record the next source check and retry?
A dependable reg basis holding period and cost recovery flashcards session ends with a repair, not a larger pile of unanswered items. Keep the scope current, keep the facts visible, and let the first blank line choose the next block.
basis holding period flashcards FAQ
Are these official exam questions?
No. The prompts and explanations are original editorial practice. Use the current AICPA resources for authoritative scope and terminology.
What should I record after a miss?
Record the first blank line—ledger, clock, trigger, or entity—the boundary you would verify, the distractor you rejected, and one changed-fact retry.
Should I add more questions immediately?
Only after the first missing proof point has a repair. More volume before that repair can hide the same classification error.
Does this method promise a passing result?
No. It produces visible study evidence and a focused next action; current rules, preparation, and performance determine the actual result.
Sources
- AICPA CPA Exam Blueprints
- AICPA CPA Exam resources
- NASBA CPA Exam FAQ
- REG review hub