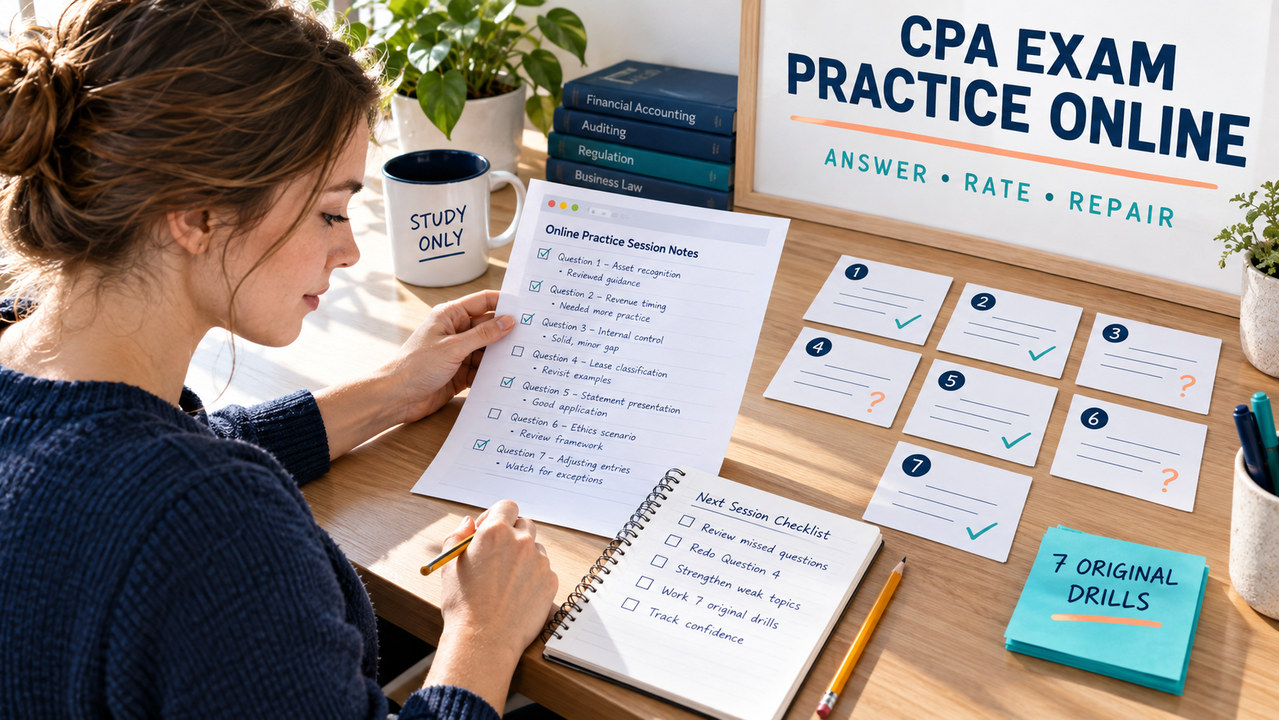

Quick answer: useful cpa exam practice online should let you attempt original items in a low-friction session, rate confidence before feedback, inspect why the right answer works and the distractor fails, and choose the next review mode. This page gives seven original drills across AUD, FAR, REG, BAR, ISC, and TCP. It is independent study material, not an official score or readiness prediction.
However, “online” does not automatically mean “official” or “scored.” Moreover, the AICPA sample test is a separate tool for exam-software familiarity. These drills teach content and review habits; they do not reproduce official questions or promise a result.
CPA Exam Practice Online: What This Set Does
In short, this is a seven-item mixed set for a browser session or printed study log. Also, each item states the skill, assumptions, and difficulty before the answer. Next, write your response, mark high, medium, or low confidence, then open the reveal. In other words, a supported answer needs both a defensible answer and reason.
For example, a correct answer with low confidence still needs a review action, while a confident miss needs a closer look at the rule or evidence.
- Original practice: all seven fact patterns, values, assumptions, and explanations are independently authored.
- Browser-ready: use a quick drill, focused block, or full review session; no account or official score is required.
- Confidence before feedback: a correct answer with low confidence is a different repair task from a confident answer with a weak reason.
- Next-session focus: carry one changed amount, date, role, or condition into the next drill.
How to Use This CPA Exam Practice Online Set
First, choose a session mode: quick for two items, focused for one section or error type, or full for all seven plus review. These are editorial study modes, not AICPA timing rules.
- Set mode: decide whether the goal is exposure, repair, or a mixed check.
- Read: underline the requested verb, unit, evidence, or control response.
- Answer: write the option, conclusion, or calculation with one reason.
- Rate: record high, medium, or low confidence before opening the reveal.
- Reveal: compare why the correct path works and why the tempting distractor fails.
- Repair: classify the first weak step and book a changed-fact retry.
Therefore, record the item, answer, confidence, first miss, repair sentence, and next mode. As a result, the next session can target a real weakness instead of chasing a percentage. For that reason, a tab, timer, or percentage is not proof of official readiness. Finally, the AICPA Blueprints remain the authority for tested areas, task statements, item types, and weighting.

CPA Exam Practice Online: 7 Original Drills
Next, attempt each item without searching. In addition, every scenario is original practice with deliberately bounded facts. Afterward, open the reveal and record the distractor that first attracted you.
1. AUD: Use Receiving Evidence for Inventory Cutoff
Tested skill: connect receiving evidence and delivery date to an inventory cutoff. Assumptions: goods arrive and are signed for December 31; the invoice is dated January 3; terms are FOB destination; goods are accepted on arrival. Ignore returns, consignment, and other inventory. Difficulty: foundational application.
Original practice item: should the goods be included in the December 31 inventory count, and what evidence should the reviewer connect first? Write your conclusion and confidence.
Reveal answer and reasoning
Answer: include the goods in December 31 inventory because delivery and acceptance occurred that day under the stated FOB-destination assumption. Connect the signed receiving report, delivery date, purchase order, and later invoice. Using January 3 as the cutoff is the distractor; invoice dating can lag delivery evidence. Next action: change the delivery date while holding the invoice date constant.
2. FAR: Apply a Stated Lower-of-Cost-and-NRV Write-Down
Tested skill: calculate a stated inventory write-down from cost and NRV. Assumptions: cost is $48,000 and stated NRV is $45,000. Ignore replacement cost, pools, tax effects, and other measurement rules. Difficulty: foundational calculation.
Original practice item: what carrying amount and write-down should the item receive under the stated assumptions? Show the subtraction before checking.
Reveal answer and reasoning
Answer: carrying amount is $45,000 and write-down is $3,000, calculated as $48,000 − $45,000. Carrying $48,000 ignores the stated lower value. Another distractor reports $45,000 as the loss rather than the carrying amount. Next action: label the requested output before calculating.
3. REG: Apply a Stated Dual-Basis Gift Rule
Tested skill: separate donor basis, fair-market value, and sale price in a bounded gift scenario. Assumptions: donor basis is $18,000, gift-date fair-market value is $25,000, no gift tax is added, and the recipient sells for $22,000. Ignore holding period, improvements, and other tax facts. Difficulty: foundational application.
Original practice item: under the stated dual-basis rule, should the recipient report a gain, a loss, or neither on the $22,000 sale?
Reveal answer and reasoning
Answer: neither gain nor loss because $22,000 falls between the $18,000 donor basis and $25,000 gift-date value. One basis would support gain and the other loss, so the bounded price sits in the no-gain/no-loss range. Using $25,000 automatically and reporting a loss is the distractor. Next action: move the sale price below $18,000 or above $25,000.
4. BAR: Evaluate a Special Order with Relevant Costs
Tested skill: use incremental revenue and avoidable variable costs for a special-order decision. Assumptions: a customer offers $52 per unit for 300 units; spare capacity exists; variable production cost is $46; incremental shipping is $3; fixed costs do not change. Ignore taxes, quality effects, and long-term pricing. Difficulty: foundational calculation.
Original practice item: should the company accept the order under the stated assumptions, and what is the total incremental contribution?
Reveal answer and reasoning
Answer: accept because incremental contribution is ($52 − $46 − $3) × 300 = $900. Spare capacity makes regular price irrelevant, and fixed costs do not change. Rejecting because $52 is below a regular $80 price uses the wrong comparison. Next action: change capacity to “fully used” and list opportunity cost.
5. ISC: Strengthen Authentication After a Password Compromise
Tested skill: choose an authentication response after a password compromise. Assumptions: a privileged administrator account uses a password plus push approval; the password is exposed; the organization can deploy a phishing-resistant hardware security key. Ignore downtime and procurement cost. Difficulty: foundational control judgment.
Original practice item: which immediate design change most directly reduces the stated credential risk?
Reveal answer and reasoning
Answer: reset the exposed password and require the phishing-resistant key for the privileged account, while preserving evidence and reviewing active sessions. A second push approval leaves the compromised password in the path; a longer-password reminder does not contain the known exposure. Next action: separate containment, credential replacement, session review, and monitoring.
6. TCP: Compare Tax Timing Under a Stated Retirement Assumption
Tested skill: compare tax timing when future and current marginal rates differ. Assumptions: a taxpayer may choose a permitted pre-tax or after-tax contribution of the same amount; current marginal rate is 22%; expected retirement rate is 32%; returns match; eligibility and distribution conditions are satisfied. Ignore limits, credits, penalties, and state tax. Difficulty: foundational planning judgment.
Original practice item: which tax-timing direction is favored by the stated assumptions, and why is this not a universal recommendation?
Reveal answer and reasoning
Answer: the after-tax option is favored because tax is paid at the lower current rate rather than the higher expected retirement rate, assuming the conditions hold. It is not universal: rates, eligibility, limits, distribution rules, and taxpayer facts can change the comparison. The distractor treats a hypothetical rate path as permanent. Next action: make the expected retirement rate lower and reverse the comparison.
7. AUD: Evaluate an Online Confirmation Exception
Tested skill: investigate an online confirmation response before concluding a balance is misstated. Assumptions: the ledger shows a $60,000 receivable; the customer portal shows $0; there is no invoice reference; the customer says the portal was migrated; a signed statement and later cash can be obtained. Ignore fraud conclusions until evidence is evaluated. Difficulty: foundational evidence judgment.
Original practice item: what should the reviewer do first?
Reveal answer and reasoning
Answer: investigate the exception and validate the source by reconciling the migration, invoice detail, customer contact, and later cash before concluding. The $0 response is a signal, not a complete conclusion, because migration may explain the mismatch. Accepting the ledger ignores contradictory evidence; calling the receivable fictitious overstates one unreferenced portal view. Next action: change it to a signed invoice-level confirmation and identify the remaining gap.
CPA Exam Practice Online: Read Your Result
Therefore, use “supported answers,” not raw correct answers. Count an item only when both answer and reason survive the reveal. For that reason, use confidence to choose concept, evidence, or speed review. This is not an AICPA score, passing standard, readiness prediction, or exam result.
- 0–2 supported: choose focused mode, review one governing rule, and retry two items with changed facts.
- 3–5 supported: classify the first miss, then complete a focused block on that error category before another mixed set.
- 6–7 supported: use full mode with unseen facts; do not convert this small set into a pass claim.
CPA Exam Practice Online: Sort Your First Miss
Instead, diagnose the first weak step. A reading miss answers the wrong verb or unit; a knowledge miss lacks the rule; an evidence miss uses a true but unhelpful fact; a calculation miss reverses a sign, unit, or order; a format miss ignores the requested shape. On the other hand, a supported answer with low confidence still deserves a brief verification.
- Rewrite the requested output in your own words.
- Then choose one rule, Blueprint topic, worked example, or control principle.
- Write a repair sentence, such as “Label carrying amount before reporting the loss.”
- Schedule a new online session that changes one fact but preserves the same skill.
In addition, confidence changes the repair: low confidence usually needs concept review, while high confidence may need an evidence, distractor, or source check. A correct answer without a reason is not supported.

CPA Exam Practice Online vs. the AICPA Sample Test
In contrast, the AICPA sample test is an official preparation resource for exam-software format and functionality. AICPA says learners can see correct answers and that it is not scored or a readiness determination. Use it for software familiarity.
Meanwhile, this page provides independent content practice, confidence tracking, distractor review, and a repair plan. It does not reproduce official items, simulate Prometric, or calculate a prediction. As a result, use it for review habits rather than a readiness claim. See the free CPA practice test guide for another independent set.
After CPA Exam Practice Online
First, start with the first unsupported or high-confidence answer: rewrite the output for a reading miss, review one rule for knowledge, map fact to conclusion for evidence, write formula/sign/unit for calculation, or copy the requested shape for format.
Then schedule a changed-fact retry within two study sessions. Keep the skill constant while changing one amount, date, role, source, or condition. If supported, switch from focused to mixed mode; if not, return to the rule instead of increasing the timer. Consequently, the retry tests transfer rather than memory of the original wording.
FAQ: CPA Exam Practice Online
Are these official CPA Exam questions?
In short, no. The seven drills are independently authored. AICPA and NASBA pages provide scope and process boundaries only; this page does not reproduce or imply access to restricted questions.
Does this online result predict whether I will pass?
However, it does not. The supported-answer bands choose the next session; they are not an official score, passing standard, readiness prediction, or exam result.
Do I need a laptop to use this practice set?
No. Instead, use a browser, printed copy, or study log; the practice loop does not depend on a specific device or operating system.
How long should an online session take?
For example, use quick mode for two items, focused mode for a repair block, or full mode for all seven plus review. These are study choices, not official timing rules.
Where can I verify current CPA Exam scope?
Finally, use the current AICPA Blueprints for areas, task statements, skills, item types, and weighting. Use the official AICPA sample-test resource for software familiarity, and use NASBA or the applicable jurisdiction for process questions.
Sources and Originality Note
Checked September 16, 2026. The official pages below establish scope, software-familiarity, and process boundaries. The seven questions, assumptions, values, answer logic, distractors, confidence rules, error categories, and retry workflow are independently authored practice.
- AICPA: Learn what to study for the CPA Exam and current Blueprints
- AICPA: Practice for the CPA Exam with Sample Tests
- AICPA: CPA Exam FAQ
- NASBA: CPA Exam process and candidate resources
Semrush US volume, difficulty, and intent were not individually refreshed. Keep this article in draft until the row-level refresh and remaining workflow gates are complete.