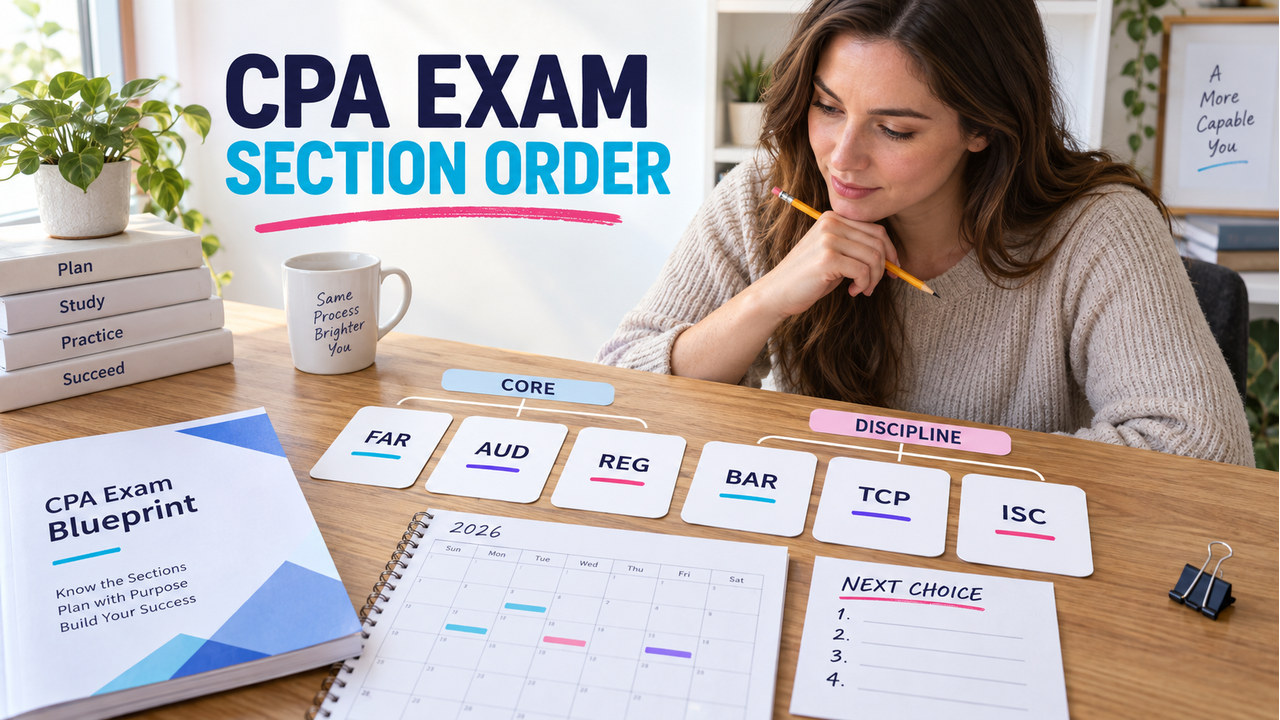

Verified September 15, 2026: the cpa exam section order is flexible under the current NASBA Candidate Guide. You may take the four required sections in any order. The current model is three Core sections—AUD, FAR, and REG—plus one Discipline chosen from BAR, ISC, or TCP. No official national rule says that every candidate must start with one particular section.
However, that answer is only the starting point. Your state or territory controls the examination credit rule, your current Blueprint controls what you need to practice, and your real schedule controls what you can finish. A commercial FAR-first recommendation can be a useful hypothesis, but it is not a substitute for checking those constraints.
This guide separates confirmed policy from planning judgment. It then gives you a short Section-Order Scorecard so you can choose the next section with a written reason, a verification date, and a plan for what would make you change the order.
For a broader preparation path, continue with our CPA Exam Study Guide.
cpa exam section order: what the current rule says
The confirmed rule is simple: the four sections may be taken in any order. Each section is four hours, and the exam has three Core sections plus one Discipline section of your choice. You take one section at a time, and you must pass all four under the examination credit rule that applies to your jurisdiction.
Confirmed for the current 2026 planning boundary
- Core: AUD, FAR, and REG are required for every candidate.
- Discipline: you choose one of BAR, ISC, or TCP.
- Passing standard: each section requires at least 75 on the reported 0–99 scaled-score system.
- Content boundary: the AICPA resource currently links Blueprints effective January 1, 2026.
What the official rule does not decide
In practice, it does not decide which section fits your background, which Discipline you should choose, how much study time you need, or how your credit window interacts with your dates. Those are planning decisions. Treat them as testable hypotheses and verify them against your own Board, Blueprint, practice evidence, and calendar.
CPA Exam Section Order: Know the Six Sections Before You Build a Sequence
Before comparing sequences, define what each slot in the sequence is doing. The descriptions below follow the current Core + Discipline model. The last column is a planning prompt created for this guide, not an official recommendation.
| Section | Current role | Planning prompt, not policy |
|---|---|---|
| AUD | Core: auditing, attestation, ethics, and professional responsibilities. | Could your current study materials support rule-based reading and evidence evaluation next? |
| FAR | Core: financial reporting, transactions, and not-for-profit topics. | Do you have the uninterrupted runway to map a broad Blueprint and practice calculations? |
| REG | Core: taxation, business law, and professional responsibilities. | Can you keep changing rules, fact patterns, and application practice in one feedback loop? |
| BAR | Discipline: business analysis and reporting. | Does the current Blueprint match your reporting, analysis, and technical-accounting preparation? |
| ISC | Discipline: information systems and controls. | Do your materials and practice set cover the technology, controls, and assurance tasks named in the Blueprint? |
| TCP | Discipline: tax compliance and planning. | Does your tax background translate into current task practice, rather than only familiar vocabulary? |
One Discipline leads to the same CPA license as the other choices. The practical question is not which label sounds most prestigious. It is which current Blueprint and task set you can prepare for consistently while protecting the rest of your sequence.
CPA Exam Section Order: Four Evidence Checks for Choosing Your Order
1. Check your jurisdiction and credit runway
Start with your Board of Accountancy and the latest NASBA Candidate Guide. Credit windows differ by jurisdiction, and the starting point, duration, and measurement date may not match a generic study blog. Write the rule, your first passing date if you already have one, and the last date that protects the credit. This fact can override an otherwise attractive sequence.
2. Check readiness instead of pass-rate headlines
For that reason, AICPA reports a 75 passing standard on a scaled score, not a percentage correct, and says the exam is not curved. Published pass rates describe groups and periods; they do not tell you which section your preparation can support next. Use a mixed diagnostic set to identify what you can explain, apply, and finish under time.
3. Check the current Blueprint
Next, open the 2026 Blueprint for the exact section before you lock the next date. Mark the task verbs, item types, skill levels, and weighting that your materials actually cover. If your notes name a topic but your practice does not reproduce the task, you have a preparation gap—not evidence that another order is universally better.
4. Check the calendar and Discipline fit together
Meanwhile, continuous testing gives flexibility, but appointment availability is set by individual centers and your NTS has its own validity details. Put the Discipline choice, study blocks, score-release expectations, work deadlines, and travel on one calendar. A sequence that looks efficient on paper fails if the next section cannot be scheduled or the study block is not real.
CPA Exam Section Order: Three Practical Sequence Patterns
In practice, these are planning patterns, not official recommendations. Select one only if the evidence checks above support it.
Foundation-first: FAR, then AUD, REG, and your Discipline
This pattern may fit a candidate who wants a broad financial-reporting base before moving to the other Core sections. Its risk is committing to the largest personal gap before confirming the study runway. If the Blueprint diagnostic shows that FAR coverage is too thin for the available date, the pattern should be revised rather than defended.
Fit-first: the Core section you can prepare for consistently
This pattern begins with the section that matches your strongest current evidence, whether that is AUD, FAR, or REG, and then uses the result to refine the next choice. It can build momentum, but it should not become an excuse to postpone a section whose credit deadline is closer. Record the deadline before you book the confidence-building option.
Deadline-first: protect the constraint that can expire
This pattern gives priority to an existing credit, a realistic testing appointment, or a study window that will disappear. It is useful for candidates already in progress or balancing work and school. The discipline is to check the target Blueprint and readiness before booking; urgency does not remove the need to practice the actual tasks.
Use the CPA Exam Section Order Scorecard
Then, for each possible next section, write one short note under five signals: runway (credit and eligibility), Blueprint fit (content and tasks), readiness (mixed MCQ and TBS evidence), Discipline fit (why this choice remains your choice), and calendar friction (date, center, work, and study blocks). Give each signal a simple green, watch, or stop label in your private record; the labels are a planning aid, not a Yoast or exam score.
Choose the section with no stop signal and the clearest next action. Then write: “I chose ___ because ___; I will recheck ___ on ___.” This makes the CPA Exam section order explainable. If the only reason is that a blog called it easy or hard, the scorecard is not finished.

When to Change the CPA Exam Section Order
Accordingly, change the plan when a governing fact changes, not merely because one practice set felt uncomfortable. Recheck the order if your Board changes a credit rule, a new Blueprint replaces the current one, your Discipline diagnostic reveals a repeated task gap, your NTS or appointment cannot support the date, or a passed section creates a deadline you had not recorded.
Still, a failed practice set can be a reason to narrow the next action, not automatically to reorder all four sections. Compare the error pattern with the Blueprint, repeat a representative mixed set, and set a review date. Change the sequence only when the new evidence changes the constraint or the section fit.
Common Questions About CPA Exam Section Order
Do I have to take CPA Exam sections in a fixed order?
No. The current NASBA Candidate Guide says the four sections may be taken in any order. Your jurisdiction’s credit rule, eligibility, NTS, and schedule still determine whether a specific plan is workable.
Is FAR always the best first section?
No official source makes FAR-first a universal requirement. FAR may fit a candidate with the right runway and diagnostic evidence; another candidate may need to protect a deadline or start with a better-supported section.
Should I take the Discipline before finishing the Core sections?
The order is flexible, but the Discipline choice should be tied to its current Blueprint, your preparation fit, and your credit calendar. Do not choose it from a generic ranking or assume the label limits your eventual CPA license.
Does my section order change the CPA license I receive?
No. The current Core + Discipline model requires the three Core sections and one selected Discipline; the selected Discipline does not restrict the license’s practice rights.
CPA Exam Section Order: Your 2026 Next Step
Finally, open the current Candidate Guide, your jurisdiction’s credit information, and the Blueprint for the section you are considering. Use the four gates below, then save the reason for your next booking with a date to recheck it.
CPA Exam Section Order Check
Move through these gates in order. If one answer is no, repair that evidence before changing your entire sequence.
- Do I know my jurisdiction's credit rule and the date by which my current credits must be protected?
- Have I opened the current 2026 Blueprint for the section I plan to take next?
- Do mixed MCQ and TBS practice results show a specific, reviewable next step?
- Can I reserve the appointment and study block without creating a deadline conflict?
Check your reasoning
Answer: If any answer is no, fix that evidence first. If all four answers are yes, book the next section and write down why this order fits your constraints.
The best sequence is the one you can support with current rules, current content evidence, a realistic date, and a feedback loop—not a headline recommendation.
If one gate is unanswered, that gate is the next task. Once all four are supported, your chosen order is defensible even if it differs from a commercial recommendation.
Sources and Update Log
Official pages checked September 15, 2026:
- NASBA CPA Exam Candidate Guide — current four-section structure, any-order statement, passing requirement, and jurisdictional credit-rule boundary.
- NASBA CPA Exam FAQ — section names, continuous testing, NTS, and administration guidance.
- AICPA CPA Exam Blueprints guide — Blueprints effective January 1, 2026, task statements, item types, and weighting.
- AICPA scoring and pass rates — 75 passing standard, scaled-score explanation, and the limit of pass-rate interpretation.
- AICPA: The new CPA Exam, two years in — current Core and Discipline descriptions and license context.
Update owner: CPA Exam Prep content team. Refresh this page when NASBA publishes a new Candidate Guide, a Board changes its credit rule, AICPA replaces the 2026 Blueprints, or the section structure, scoring, or scheduling guidance changes.
CPA exam questions
Do I have to take CPA Exam sections in a fixed order?
No. The current NASBA Candidate Guide says the four sections may be taken in any order, subject to the applicable jurisdiction’s credit and administration rules.
Is FAR always the best first section?
No. FAR-first is a planning hypothesis for some candidates, not a universal official requirement.
Should I take the Discipline before finishing the Core sections?
The order is flexible; choose the Discipline from its current Blueprint, your preparation fit, and your credit calendar.