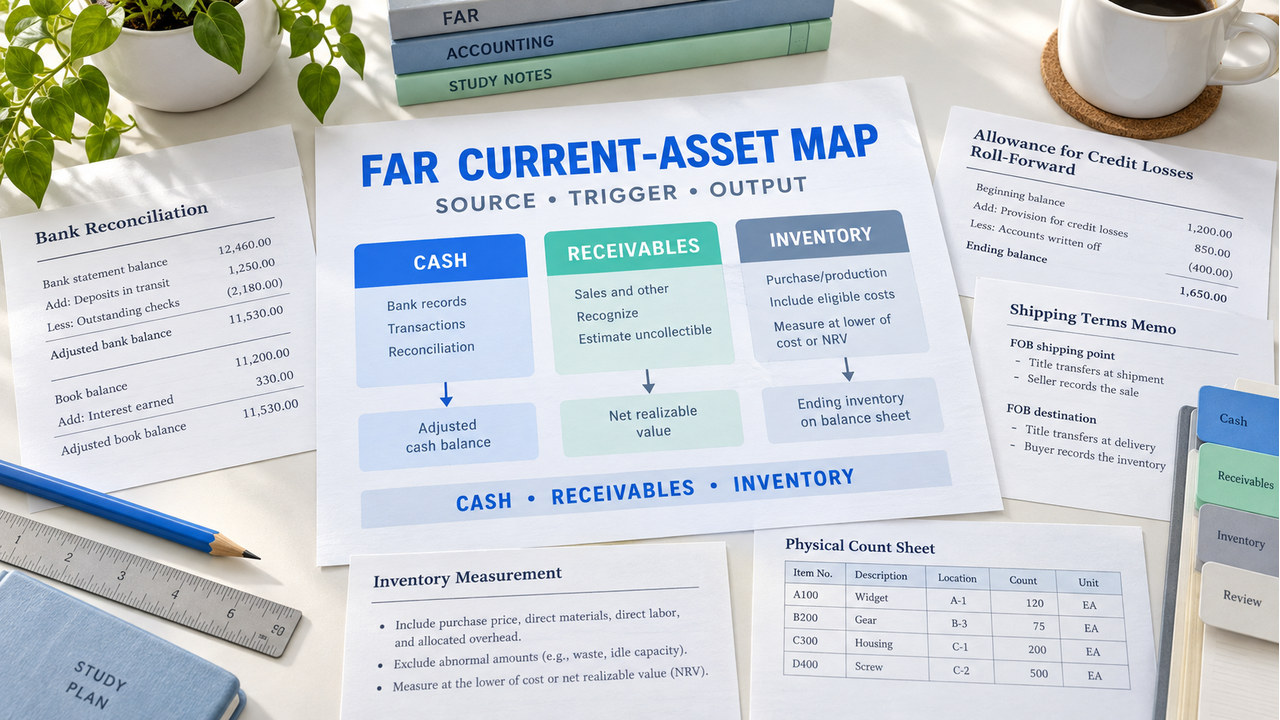

Direct answer: far cash receivables and inventory explained becomes manageable when you keep three questions separate: which record supplies the evidence, which fact controls the treatment, and what output the question requests. In particular, cash cases usually turn on bank timing versus book activity. Meanwhile, receivables cases turn on movement to an ending allowance target. By contrast, inventory cases turn on ownership, measurement, or physical-count evidence. Therefore, name that lane before you calculate.
Editorial review note: This page was checked by the CPA Exam Prep study-content team for terminology, arithmetic, internal consistency, source boundaries, and learner usefulness. The examples, prompts, answers, distractors, and review aids are original editorial practice, not provider-owned exam content.
This far cash receivables and inventory explained lesson uses simplified facts to make the controlling link visible. The current AICPA Blueprint and current accounting guidance define the live boundary. Use the FAR review hub for broader topic routing, and reopen authoritative guidance when a real fact pattern adds an assumption that is not stated here.
How far cash, receivables, and inventory fit together
These topics look like separate chapters, but they test a shared FAR habit: match the source record to the requested output before touching the number. Meanwhile, a bank statement is not the same evidence as the general ledger. Likewise, an allowance target is not the same line as the expense movement. In contrast, a shipping term is not interchangeable with a shipment date. Finally, a physical count difference is not automatically a valuation adjustment.
Start every case with a short lane label. For timing, mark timing when the issue is when a bank or transaction appears. Next, mark target when the issue is movement to an ending balance. For ownership, mark term when the issue is who owns goods at the reporting date. Similarly, mark value when the prompt supplies a measurement comparison. Finally, mark count when the evidence is a record compared with physical observation.
Bank statement, ledger, aging or allowance schedule, shipping memo, valuation note, or count sheet.
Timing item, ending target, ownership term, measurement benchmark, or physical evidence.
Adjusted balance, expense movement, inventory inclusion, write-down, or investigation amount.
Therefore, that source-trigger-output order prevents a common shortcut: seeing a familiar amount and treating it as the answer. It also makes distractors easier to reject. First, for an adjusted bank balance, a deposit in transit belongs to the bank side. Next, for allowance expense, subtract the opening credit from the required ending credit. In an inventory-ownership case, read the term. For a measurement adjustment, compare the stated cost and benchmark. Finally, for an investigation amount, preserve the record-to-count difference first.
Build a far cash receivables and inventory explained decision map
Before solving, write five fields: asked output, source record, controlling fact, calculation or classification, and next check. The order matters. It keeps a timing adjustment from being posted to the wrong record and keeps a physical difference from being labeled as a valuation conclusion without support.
Use the map below as a pre-solve routine. First, read the verb in the question: reconcile, estimate, include, compare, or investigate. Next, underline the fact that controls that verb. Then, place the amount in the correct evidence lane. Finally, write one sentence that explains why the nearest tempting answer is not supported.
For a current exam-style case, the facts may be intentionally short. Do not invent a different allowance model, shipping term, cost-flow method, or reporting date. When the facts are insufficient for a live technical conclusion, mark the missing fact and reopen current authoritative guidance. The practice set here is designed to train the reasoning sequence, not to reproduce provider material.

Original far cash receivables and inventory explained practice set
First, attempt each case before opening the explanation. Next, record the lane, the requested output, and the nearest distractor. The cases below are independently authored and intentionally use different numbers from any provider material.
Case 1 — Separate bank timing from book activity
Question: The bank statement shows $84,720. Deposits in transit are $3,680, and outstanding checks are $2,440. The books show $85,830 before a $145 bank fee and $275 of bank interest. What adjusted balance should both sides support?
Reveal Case 1 answer and reasoning
Answer: $85,960. First, the bank side is $84,720 + $3,680 − $2,440 = $85,960. Meanwhile, the book side is $85,830 − $145 + $275 = $85,960. Deposits in transit and outstanding checks are timing items on the bank reconciliation; the fee and interest change the books. Therefore, the distractor is to post every item to the ledger because every amount appears in one paragraph.
Case 2 — Move the allowance to the required target
Question: Gross receivables are $318,000. The allowance has an opening $8,400 credit balance, and the required ending credit is $14,750. What expense movement and net receivables follow?
Reveal Case 2 answer and reasoning
Answer: $6,350 expense movement and $303,250 net receivables. First, the movement is $14,750 − $8,400 = $6,350. Consequently, net receivables are $318,000 − $14,750 = $303,250. The ending target is a balance-sheet destination, not automatically the current-period expense. Keep the opening balance, movement, ending target, and net receivables on separate lines.
Case 3 — Read the ownership term before the date
Question: Goods costing $9,840 were shipped FOB shipping point on December 31. Goods costing $15,600 were shipped FOB destination on December 31 and arrived on January 3. Which goods belong in the buyer’s December 31 inventory under the stated facts?
Reveal Case 3 answer and reasoning
Answer: include the $9,840 FOB shipping point goods and exclude the $15,600 FOB destination goods. Under the simplified facts, the shipping term identifies the ownership trigger. The shipment date appears in both sentences, but it does not replace the term. Circle FOB shipping point or FOB destination first, then decide whether the buyer owns the goods at the reporting date.
Case 4 — Keep value evidence separate from count evidence
Question: Under the simplified comparison supplied for this exercise, recorded inventory cost is $58,400 and the stated NRV is $56,950. What write-down and ending amount follow?
Reveal Case 4 answer and reasoning
Answer: a $1,450 write-down and $56,950 ending inventory. The difference is $58,400 − $56,950 = $1,450. This is a value lane because the evidence is recorded cost compared with a measurement benchmark. Do not look for a physical shortage merely because the prompt says inventory. The correction sentence should name the cost-versus-NRV comparison.
Case 5 — Investigate a record-to-count difference first
Question: The perpetual record supports $47,260 at cost, while the verified physical count supports $46,910 at cost. No ownership or measurement complication is supplied. What amount should you investigate first?
Reveal Case 5 answer and reasoning
Answer: investigate a $350 shortage. The count is $47,260 − $46,910 = $350 below the record. Check count accuracy, receiving and shipping cutoff, unrecorded movement, and shortage support before selecting a final treatment. The distractor is to treat the difference as a valuation adjustment without a value fact.
Review far cash receivables and inventory explained by lane
After the reveals, score the reasoning rather than only the number. A correct answer with the wrong lane is provisional because a changed fact could break it. Mark each case as source error, trigger error, calculation error, or support error. Each label should change the next ten-minute block.
Reread the bank statement, ledger, term, valuation note, or count sheet and circle the evidence lane.
Write the boundary: timing, target, term, value, or count.
Rebuild the equation and label each amount before changing a sign.
Add the controlling fact that would let another reviewer reproduce the answer.
A 0–2 result means rebuild the lane labels and repeat the two weakest cases. A 3–4 result means change one fact in the weakest lane. A 5 result means transfer the method to a mixed packet without reopening the same answer key. These are local study routes, not official score bands or readiness claims.

Retry after changing one far cash, receivables, or inventory fact
Change only Case 2’s opening allowance. Keep gross receivables at $318,000 and the required ending credit at $14,750, but change the opening credit from $8,400 to $6,200. Net receivables remain $303,250 because the ending target did not change. Expense movement becomes $14,750 − $6,200 = $8,550.
The retry checks whether you understand movement logic or merely memorized $6,350. A second retry can change only the bank fee in Case 1, only the shipping term in Case 3, only NRV in Case 4, or only the physical amount in Case 5. Preserve every other fact and write a new correction sentence. If more than one fact changes, the retry no longer diagnoses the original error.
Research and refresh note
Use the current AICPA CPA Exam Blueprints to orient tested scope. Use the AICPA sample tests for format orientation, not for copied content. For a live accounting conclusion, consult the FASB Accounting Standards Codification. The NASBA CPA Exam FAQ is the appropriate place to refresh administration questions.
These cases hold several facts constant so the skill remains visible. A real entity may require additional work on reporting date, shipping terms, allowance methodology, cost-flow assumptions, measurement rules, or cutoff evidence. Reopen the live sources before reusing a fact-specific example after a scope or guidance change.
Next action: Recopy the source-trigger-output fields, attempt Case 1 without notes, and write the one fact that would change your answer before opening the reveal.
FAR cash, receivables, and inventory explained FAQ
What is the fastest way to start a cash reconciliation case?
First, write the requested output, then separate bank timing items from book adjustments. For example, deposits in transit and outstanding checks usually affect the bank side; fees and interest usually affect the books under the stated facts.
Why is the allowance expense different from the ending allowance?
In practice, expense is the movement from the opening allowance balance to the required ending target. Therefore, net receivables use gross receivables less the ending target.
What controls inventory ownership at a reporting date?
Under a simplified practice case, read the stated ownership term before relying on the shipment date. A live fact pattern may require additional research.
How do inventory value and inventory count differ?
Similarly, a value case compares a recorded cost with a stated measurement benchmark. Meanwhile, a count case compares a record with physical evidence and begins an investigation.
What should I do when my number is right but my explanation is weak?
Keep the point provisional, label the missing controlling fact, and retry one case after changing one fact. The goal is a defensible path, not a lucky number.