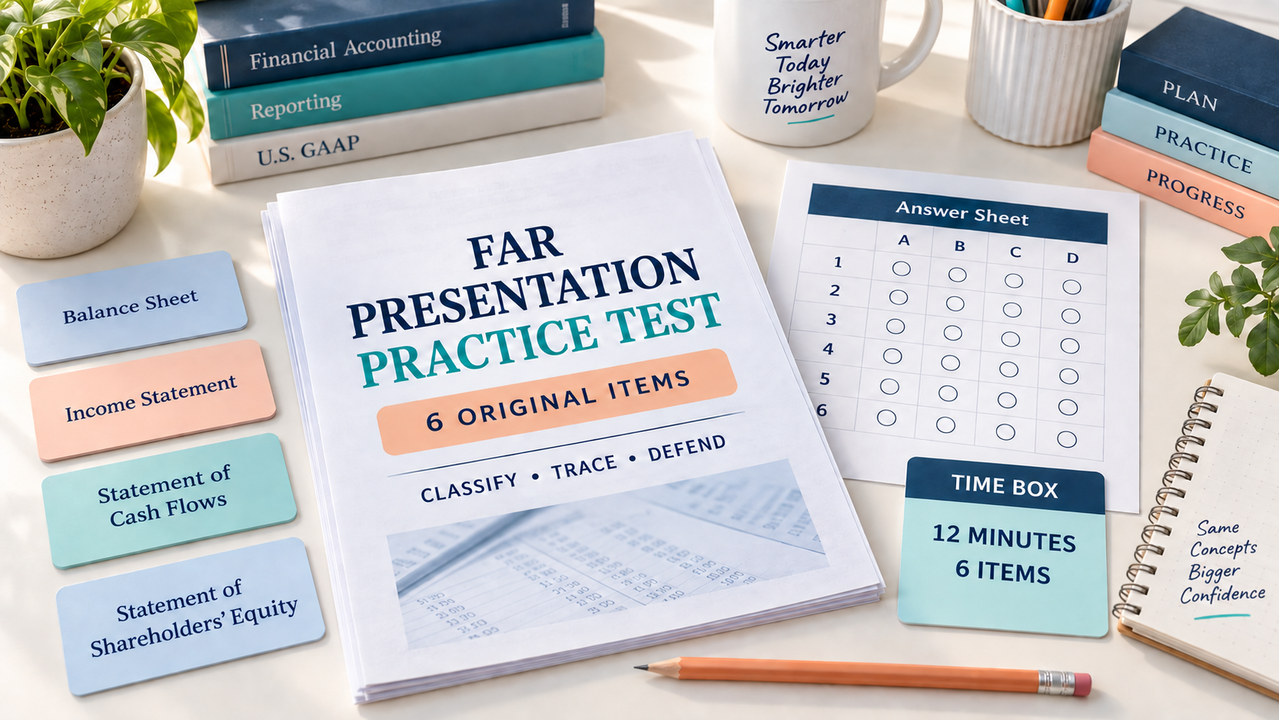

A financial statement presentation practice test is most useful when it forces one clean decision at a time. This twelve-minute set gives you six original FAR questions on classification, cash-flow disclosure, equity presentation, diluted EPS, unusual items, and segment reporting. It is a study diagnostic, not an official exam score, prediction, or readiness claim. Work without notes first, record the first miss, and open each answer only after you commit to a choice.
For a broader preparation path, continue with our CPA Exam Study Guide.
How to use this financial statement presentation practice test
Set a twelve-minute timer for six questions. The difficulty is mixed: Questions 1 and 2 are foundation gates, Questions 3 and 4 require a short classification or calculation, and Questions 5 and 6 test whether you can keep an unusual fact or quantitative threshold in the correct presentation channel. The facts, amounts, choices, and rationales are original editorial practice, not copied or previously circulated provider material.
Use the same routine on every item. First, circle what the prompt asks you to present. Next, trace the fact that controls the answer. Then, name the statement, line, category, or disclosure where the result belongs. Finally, explain why the nearest distractor fails. If the question contains a simplified assumption, accept it for this set; if your real assignment adds a scope, tax, materiality, or effective-date exception, reopen the current literature.
Build the four-gate method before the presentation practice test
Presentation questions often feel broad because the same fact can affect more than one statement. A disciplined gate sequence makes the answer smaller. Keep the destination visible while you work:
- CLASSIFY: identify whether the prompt asks for classification, a cash-flow treatment, an equity movement, an EPS denominator, an income-statement line, or a segment disclosure.
- TRACE THE FACT: find the controlling date, cash movement, share count, ownership relationship, unusual-item condition, or quantitative threshold.
- DISPLAY THE RESULT: name the statement, category, line, comparative period, or note before selecting an answer.
- DEFEND THE CHOICE: state why the closest distractor uses the wrong fact, timing, denominator, or presentation bucket.

Six original questions: financial statement presentation practice test
Attempt every item before opening a reveal. Write one short reason beside each answer. That note matters because the review step compares your reason with the controlling gate, not just with the answer letter.
Question 1: Current or noncurrent debt
Brightline Services has a $900,000 note payable due on September 30, 2027. The company’s reporting date is December 31, 2026. The note has no covenant violation, no callable feature, and no executed right to defer settlement beyond the next twelve months. Which presentation is best under the stated assumptions?
- Present the entire note as noncurrent because the term is longer than one year from issuance.
- Present the note as current because it is due within twelve months of the reporting date.
- Present half as current and half as equity because principal is scheduled.
- Exclude the note from the balance sheet until cash is paid.
Reveal Question 1
Answer: B. The classification gate is the reporting-date settlement window. September 30, 2027 falls within twelve months after December 31, 2026, so the note is current under the simplified facts.
Why the distractor fails: The issuance date does not restart the classification clock, and scheduled principal is still a liability. The answer changes only if an applicable exception, operating-cycle rule, or enforceable right to defer settlement changes the facts.
Retry: Change the fact so the note is due in March 2028 with no demand feature. Reclassify after comparing the due date with the reporting date again.
Question 2: Noncash investing and financing activity
On December 30, Harbor Labs acquires equipment with a fair value of $120,000 by issuing a five-year note directly to the seller. No cash changes hands, and the equipment is placed in service immediately. Which presentation is most accurate for the annual statement of cash flows?
- Show a $120,000 investing outflow and a $120,000 financing inflow in the cash-flow sections.
- Show the full amount as an operating outflow because equipment supports operations.
- Exclude the exchange from the cash-flow totals and disclose the noncash investing and financing activity separately as required.
- Record the note as a cash equivalent until the first payment.
Reveal Question 2
Answer: C. The transaction changes assets and liabilities but does not change cash. It therefore does not belong in the operating, investing, or financing cash-flow totals. The noncash acquisition and related financing are disclosed separately under the applicable guidance.
Why the distractor fails: Calling an item “investing” describes its economic nature, but a cash-flow section reports cash movements. The absence of cash is the controlling gate.
Retry: Change the fact so Harbor pays $20,000 cash and issues a $100,000 note. Separate the cash investing outflow from the noncash portion and its supplemental disclosure.
Question 3: Dividends in the statement of equity
On November 15, Oak Ridge declares a $40,000 cash dividend payable to shareholders of record. The dividend is paid on January 20 of the following year. Assume the declaration creates a valid obligation and there are no tax complications. What is the presentation effect at the declaration date?
- Reduce retained earnings and recognize a dividends payable liability.
- Recognize a $40,000 operating expense in net income.
- Increase other comprehensive income because the payment is outside operations.
- Record the entire amount as treasury stock.
Reveal Question 3
Answer: A. The declaration is an owner distribution. It reduces retained earnings and establishes a payable; the later cash payment settles that liability. The statement of changes in equity is the key display location for the retained-earnings effect.
Why the distractor fails: A dividend is not an expense because it is a distribution to owners. Its timing also matters: the January cash payment does not erase the liability created in November.
Retry: Change the fact so the board only discusses a possible dividend and makes no declaration. Decide whether a payable exists before choosing the equity presentation.
Question 4: Diluted EPS and options
Maple Works has 1,000,000 common shares outstanding for the year and net income of $530,000. It also has 100,000 employee options with an exercise price of $12. The average market price is $20, and the options are in the money. Assume no preferred dividends, taxes, or other dilutive instruments. What incremental share count should the simplified treasury-stock method add to the diluted EPS denominator?
- 20,000 shares
- 40,000 shares
- 60,000 shares
- 100,000 shares
Reveal Question 4
Answer: B. Under the simplified treasury-stock method, incremental shares equal options multiplied by the fraction of proceeds not used to repurchase shares: 100,000 × ($20 − $12) ÷ $20 = 40,000 shares. The diluted denominator is therefore 1,040,000 shares before any other adjustments.
Why the distractor fails: Choice C uses incorrect arithmetic, while Choice D treats every option as incremental even though assumed exercise proceeds would repurchase some shares at the average market price.
Retry: Change the exercise price to $10 while leaving the market price at $20. Recompute incremental shares before changing the denominator.
Question 5: Unusual or infrequent item
In 2026, Pine Coast incurs a material loss from a rare flood. The event is unusual for the entity and is not expected to recur, but it does not meet the separate criteria for discontinued operations. Under current U.S. GAAP presentation, which direction is best?
- Present the loss as an extraordinary item below income from continuing operations.
- Include the loss in income from continuing operations and explain its nature and amount when required.
- Record the loss directly in accumulated other comprehensive income.
- Defer the loss until the next period because it is unusual.
Reveal Question 5
Answer: B. An unusual or infrequent event is not automatically an extraordinary item under current U.S. GAAP. The loss remains in continuing operations, with appropriate description and disclosure when material.
Why the distractor fails: Rarity alone does not create a separate extraordinary section. Neither OCI nor deferral is a general holding area for an expense recognized in the current period.
Retry: Change the fact so the amount is clearly immaterial. Decide which presentation and disclosure conclusion changes because materiality affects communication, not the basic recognition of the loss.
Question 6: Reportable segment threshold
Riverbend Group has three operating segments. The North segment produces 12% of combined segment revenue, 7% of combined segment assets, and a profit larger than 10% of the greater of the comparable aggregate profit or loss measures. Management receives discrete information for the segment and uses it in resource allocation. What is the best presentation direction?
- Do not disclose North separately because its asset percentage is below 10%.
- Report North as a separate reportable segment because it meets at least one applicable quantitative threshold and is reviewed discretely.
- Combine North with the smallest segment solely because its revenue is below 25%.
- Report North only in OCI because segment information is not part of the notes.
Reveal Question 6
Answer: B. The segment meets more than one stated quantitative threshold, and the facts establish that it is an operating segment reviewed through discrete information. The presentation belongs in the segment note, subject to the applicable aggregation and disclosure requirements.
Why the distractor fails: Passing one threshold can be enough; every threshold does not need to be passed. Segment information is disclosed in the notes, not in OCI.
Retry: Change the fact so North is not separately reviewed and no discrete information is available. Reassess the operating-segment gate before applying a quantitative test.
Record your presentation practice test score and first error
Before reading the reveals, record attempted items, correct answers, and the first question you missed. A simple band can guide the next action: 5–6 correct means review the explanation of the first miss and then add a changed-fact retry; 3–4 correct means repeat the four-gate method on the missed items; 0–2 correct means slow down, reread the assumptions, and study one presentation channel at a time. None of these bands is an official score.
Convert the first miss into a review task
Start with the earliest unsupported decision, even when a later question feels more difficult. For Question 1, a miss calls for a reporting-date timeline. Question 2 needs a cash-versus-noncash check. A Question 3 miss calls for an owner-distribution entry. For Question 4, write the treasury-stock formula before retrying. If Question 5 is wrong, review the unusual-item presentation note. With Question 6, check operating-segment evidence before threshold math.
Use the six-item review route after the presentation practice test
Do not repeat all six mechanically. Select the tile matching your first error, change one fact, and state whether the presentation destination changes. If you cannot explain the closest distractor in two sentences, the gate is not stable.
- Current liability: compare the contractual due date with the reporting date.
- Noncash deal: separate economic classification from actual cash movement.
- Equity dividend: distinguish a declared owner distribution from an expense.
- Diluted EPS: write the incremental-share formula before choosing the denominator.
- Unusual item: keep recognition, continuing operations, and material disclosure connected.
- Segment test: establish discrete management review before applying quantitative thresholds.

Presentation practice test: common traps
Account name: “Note payable” does not answer current versus noncurrent until reporting-date timing is clear.
Cash activity: An equipment acquisition can be investing in substance while staying outside cash-flow totals when no cash changes hands.
Owner activity: Dividends change equity and liabilities; they do not reduce net income as an operating cost.
Formula: Diluted EPS options require the assumed-proceeds calculation; a quick estimate can overstate incremental shares.
Extraordinary bucket: Unusual or infrequent does not automatically mean extraordinary under current presentation rules.
Segment threshold: Quantitative testing comes after establishing that management receives discrete operating-segment information.
FAR presentation practice test FAQ
Are these live exam questions?
No. They are original editorial practice items. The official sources listed below define the scope and refresh boundary; they do not supply the wording, amounts, choices, or answer reveals on this page.
How should I interpret my result?
Use it to choose a review action, not to predict an exam score. The first wrong gate is more useful than a percentage without an explanation.
What if my textbook gives a different answer?
Compare the assumptions first. Current literature, entity scope, materiality, tax effects, and effective dates can change a conclusion. Reopen the applicable Codification topic instead of forcing this simplified practice fact pattern to answer a different question.
Next action: complete the six items without reveals, record the first miss, change one fact, and rerun only that item.
Sources and refresh note
Current tested-skill boundary: AICPA CPA Exam Blueprints. Software orientation: AICPA CPA Exam sample tests. Administration boundary: NASBA CPA Exam FAQ. Technical refresh: FASB Accounting Standards Codification. Checked September 18, 2026. Reopen live official sources before using a dated rule conclusion. The questions, choices, rationales, scoring bands, and review route are original study guidance.