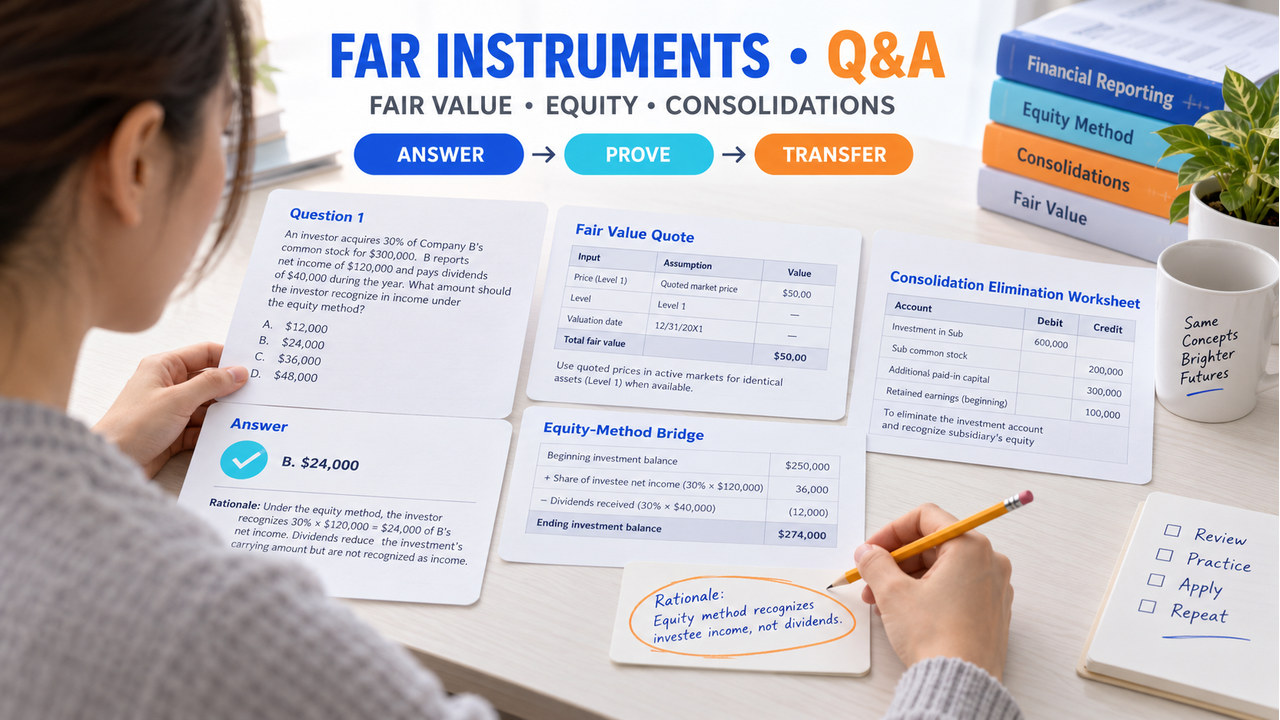

Direct answer: The fastest way to use FAR instruments questions and answers is to read the fact pattern in four passes: name the method, circle the controlling fact, build the smallest calculation, and label the requested output. Then explain both sides of the choice. However, the wrong option often answers a different question. The questions below use fair value, equity method, and consolidation facts without copying official exam material.
Scope note: This is an original study packet checked against the current AICPA Blueprint on October 2, 2026. The amounts, options, records, rationales, visual labels, and study actions are independently authored. A real reporting conclusion requires current research and complete facts.
For scope, reopen the AICPA CPA Exam Blueprint. For technical research, use the current FASB Accounting Standards Codification, including routes for Topic 321, Topic 323, Topic 810, and Topic 820. The NASBA CPA Exam FAQ covers administration. The FAR review hub can support broader sequencing.
Build an answer-rationale route for FAR instruments questions and answers
Start with the relationship or measurement clue, not the answer choices. A quoted price points toward a units-times-price bridge. Significant influence points toward an investor share and carrying-amount bridge under the stated assumptions. Control and an internal transaction point toward combining lines and eliminating effects inside the group.
Next, label the output. The prompt may ask for an ending fair value, an investor income amount, a carrying balance, an internal elimination, or an input description. A familiar number can still be wrong when it answers a different output. Therefore, write the output beside the facts before you compare letters.
Separate method fact and output before reading the answer
Use four fields: method, controlling fact, smallest bridge, and requested output. Then add a fifth field: why the other option fails. In particular, a market quote is not the same as a prior carrying amount. Likewise, a distribution is not the same as the investor’s share of income. Finally, cash collection does not make an intercompany sale external to a consolidated group.

| Question clue | Method | Smallest bridge | Why a tempting answer fails |
|---|---|---|---|
| Identical instrument quoted in an active market | Fair value | Units × quoted price | Using an old balance as today’s measurement |
| Influence, investee income, and distribution | Equity method | Opening balance + share − distribution | Treating the distribution as new investor income |
| Control and an internal balance | Consolidation | Combine, then remove internal effects | Treating group-internal activity as external |
A useful proof sentence is: “The prompt gives ___, so I use ___ and report ___; option ___ fails because it assumes ___.” That makes the next retry specific.
Practice FAR instruments questions and answers
Attempt each item before opening its explanation. Every question is original, simplified, and designed to practice reasoning. It is not a provider-supplied, recalled, leaked, or official item. State the tested skill, assumptions, and difficulty before choosing an option.
1. Match an active-market quote to fair value
Tested skill: connect identical units to a quoted price. Assumptions: the quote is for the measurement date, all units are identical, and transaction costs are outside the question. Difficulty: setup. The holding is 800 units at $19.50 each.
Question: Which answer gives the measurement-date fair value?
- A. $19.50
- B. $780
- C. $15,600
- D. $15,619.50
Reveal the answer and reasoning
Answer: C. Multiply 800 units by $19.50: $15,600. A is the price for one unit. B subtracts the price from the unit count. D adds the single-unit price to the total. Why the other option fails: each distractor changes the requested output or the bridge. Next action: write “units × quote” before you compare the choices.
2. Build the equity-method balance
Tested skill: separate investor income from a distribution. Assumptions: significant influence exists; the opening investment is $280,000; the investor’s share of investee income is $22,000; and the cash distribution is $6,000. Difficulty: intermediate.
Question: Which ending carrying amount fits the simplified bridge?
- A. $252,000
- B. $274,000
- C. $296,000
- D. $308,000
Reveal the answer and reasoning
Answer: C. Use $280,000 + $22,000 − $6,000 = $296,000. B subtracts the income share, while D adds the distribution. A reduces both movements. Why the other option fails: those options confuse the investor’s share of income with the distribution’s effect on the investment balance. Next action: keep income and distribution on separate bridge lines.
3. Remove an internal receivable and payable
Tested skill: recognize a group-internal balance in consolidation. Assumptions: a parent controls a subsidiary, the parent records a $45,000 receivable from the subsidiary, and the subsidiary records the matching payable at year-end. Difficulty: consolidation.
Question: What is the best consolidated statement response?
- A. Report both balances because each entity recorded them
- B. Eliminate the $45,000 receivable and payable
- C. Add the receivable to consolidated revenue
- D. Reclassify the payable as external debt
Reveal the answer and reasoning
Answer: B. The balances are reciprocal and internal to the controlled group, so the simplified consolidation response removes both sides. A preserves an amount the group does not owe to itself. C confuses a balance with revenue. D invents an outside lender. Next action: mark the counterparty before deciding whether a balance survives consolidation.
4. Identify an observable fair-value input
Tested skill: distinguish a quoted identical-instrument input from a model estimate. Assumptions: the question asks only for the input description and supplies a closing quote for the same instrument in an active market. Difficulty: judgment.
Question: Which description best fits the stated evidence?
- A. Observable quoted price for the identical instrument
- B. Entity-specific forecast with no market corroboration
- C. Prior carrying amount used as a current price
- D. Management estimate used because a quote exists
Reveal the answer and reasoning
Answer: A. The supplied fact is an active-market quote for the identical instrument. B and D describe less observable estimates, while C confuses a prior balance with current market evidence. Next action: underline “same instrument” and “active market” before reading the options.
5. Distinguish control from influence
Tested skill: choose the reporting route from the relationship. Assumptions: the investor owns 55% of the voting shares, appoints the majority of the governing body, and no contrary arrangement is supplied. Difficulty: foundational judgment.
Question: Which route should you test first?
- A. Consolidation because the facts describe control
- B. Equity method because any ownership below 100% is influence
- C. Fair value because ownership percentage is irrelevant
- D. No accounting because the investee remains legally separate
Reveal the answer and reasoning
Answer: A. Majority voting power and board appointment are control indicators in the simplified fact pattern, so consolidation is the first route to test. B treats every minority interest as influence. C ignores the relationship. D confuses legal separateness with group reporting. Next action: write “control” before you calculate any line item.
Use the answer-rationale check
Count an answer as stable only when four fields agree: selected option, controlling fact, requested output, and rejected option. A correct letter with a wrong explanation is a repair item. Use this FAR instruments questions and answers set to practice the explanation, not just the selection.
With 0–2, rebuild the method-fact-output map. At 3–4, repeat the first weak lane and explain two distractors aloud. With 5, change one fact in each lane and predict which part of the rationale must change.
Turn a wrong answer into a correction
Do not reread the entire topic after one missed answer. Name the first broken field. When the method was wrong, revisit the relationship. If the fact was missed, underline the quote, percentage, distribution, control signal, or internal counterparty. For an output break, rewrite the exact question in a short label. Finally, reject the nearest wrong option in one sentence.

Also, use this sentence: “I chose ___ because I saw ___, but the prompt asked for ___; the better answer is ___ because ___.” Keep the method and change only one fact on the retry. That preserves the skill while testing transfer.
Retry the FAR instruments answers with one changed fact
Keep the fair-value method but change 800 units to 1,100 units. For the equity-method retry, change the distribution from $6,000 to $12,000. Next, retain the reciprocal consolidation balance but change it from $45,000 to $62,000. For the control retry, replace majority voting power with a stated influence-only arrangement. Finally, replace the active-market quote with an unobservable forecast and explain how the evidence description changes.
End each retry with a proof sentence: “The quote controls the units-times-price bridge.” “The distribution reduces the investment balance in the stated setup.” “A group-internal reciprocal balance does not survive consolidation.” “The relationship controls the method.” “An observable quote is different from an entity-specific estimate.” These sentences show whether the answer can transfer.
Log the first FAR instruments explanation break
Classify the earliest failure rather than the last arithmetic mistake. A method break means you chose fair value, equity method, or consolidation before reading the relationship. A fact break means you ignored the quote, units, distribution, control signal, or counterparty. An output break means you calculated a balance when the question asked for an input or elimination. An explanation break means you chose the right letter but could not reject the nearest wrong answer.
Write the repair as “method ___; fact ___; output ___; wrong option fails because ___.” Then schedule one new question that changes only the broken field. This keeps the review narrow enough to measure.
Refresh FAR instruments research before reuse
Before reusing this FAR instruments questions and answers guide, reopen the AICPA CPA Exam Blueprint for scope and the FASB Codification for the technical boundary. Use Topic 321, 323, 810, or 820 only after checking the complete current facts. These links establish research paths; they do not make simplified questions universal conclusions.
Finally, recheck each option, amount, relationship, assumption, image label, and answer reveal. If a live prompt changes voting rights, classification, reporting date, market evidence, or internal transaction facts, stop the shortcut and research the current source.
FAR instruments questions and answers FAQ
What should I read before the answer choices?
Read the relationship or measurement clue, then label the requested output before comparing options.
Why can a correct number still be wrong?
It may answer ending value when the prompt asks for a change, input, balance, or elimination.
How should I review a missed answer?
Name the first broken field, reject the nearest wrong option, and retry one changed fact.
Are these official exam items?
No. They are original simplified practice questions with local rationales, not items supplied by an exam sponsor.