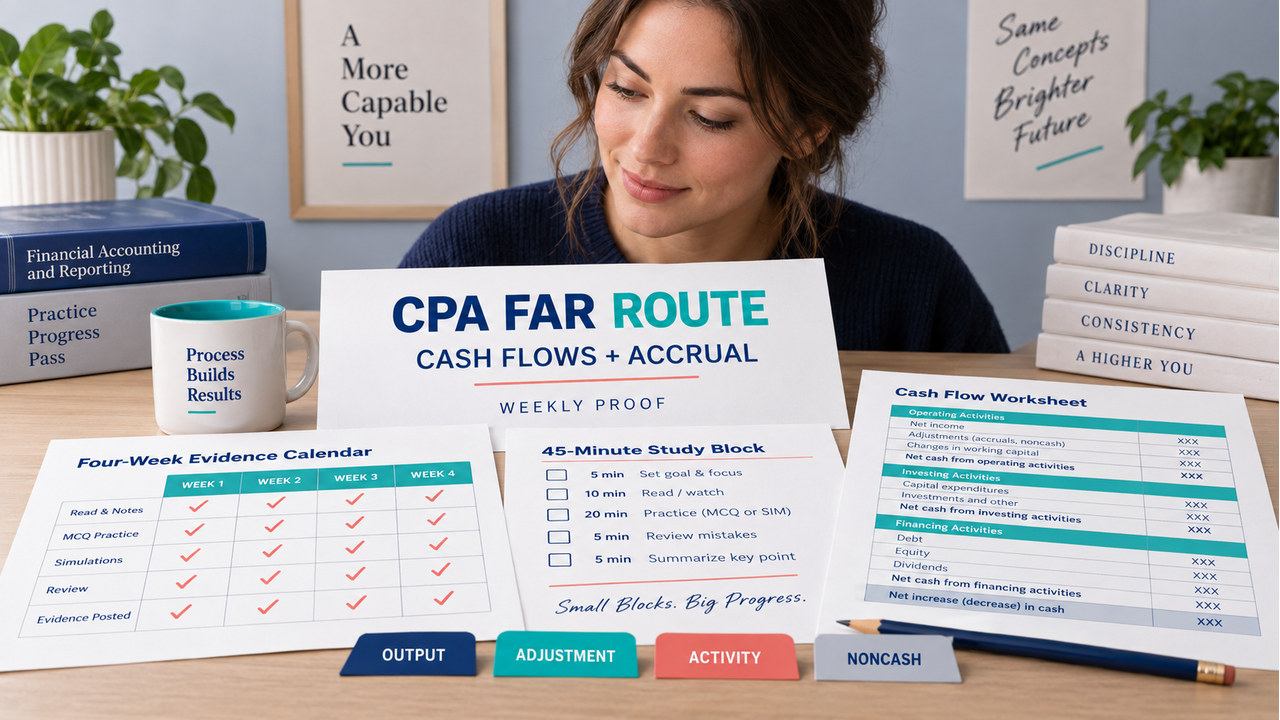

pass cash flows cpa far is not a promise that a particular study routine produces a particular exam result. It is a way to turn a pass goal into observable work: identify the requested output, place the cash movement, explain the accrual adjustment, and prove that one changed fact does not break your route. This page gives you a four-week pass route, a repeatable 45-minute block, and original practice that ends in a specific repair action.
Quick answer: First, use Week 1 to separate output, measurement, and noncash facts; next, use Week 2 to place operating, investing, and financing movements; then, use Week 3 to mix fact patterns and change one fact at a time; finally, use Week 4 to transfer the method under a clock. Keep a weekly proof line for each stage. If a miss occurs, schedule the first broken step instead of rereading the whole chapter. The CPA FAR review hub can provide broader section context, but this article stays focused on the cash-flow and accrual route.
Pass cash flows CPA FAR: start with the output
Tested skill: move from an accrual fact pattern to the exact cash-flow output the prompt requests. That output might be cash from operations, cash paid for equipment, net financing cash, or treatment of a noncash exchange. The first pass-focused habit is to write the output in the margin before touching a number. A correct calculation for the wrong output is still the wrong route.
Assumptions: the original exercises use simplified calendar-year nongovernmental entities, short calculations, and no unusual tax, industry, method, presentation, or effective-date exception. Therefore, when a real question changes those assumptions, reopen current guidance instead of extending a classroom shortcut. The current AICPA CPA Exam Blueprint resource sets the scope boundary; the AICPA sample test supports format rehearsal, not a local readiness score or a pass prediction.
Difficulty: moderate because the same fact can affect an accrual balance, a cash bridge, a statement lane, or a disclosure conclusion. For example, a sign can be right while the statement lane is wrong. A realistic route has three kinds of proof: a clean bridge, a correct lane, and a one-sentence explanation of the distractor. Track those proofs weekly. Do not use them as an official score.
Pass cash flows CPA FAR with a four-week route
Use the four weeks as a sequence of evidence, not as a guarantee or a fixed calendar for every learner. Each week has a goal, drill, proof, and next action. If you have less time, compress the minutes while preserving the order. Skipping the error log usually removes the most useful evidence.
Pass cash flows CPA FAR in Week 1: name the output
First, read the prompt verbs. “Cash provided” asks for a cash bridge. “Cash paid” asks for the payment. “Net financing cash” asks you to separate borrowing and principal repayment. “Treatment” may signal that no cash moved. Write four labels beside the facts: profit or loss, cash, balance, and noncash or adjustment. Your proof is a marked-up prompt plus one sentence explaining why the nearest tempting number does not answer it.
Pass cash flows CPA FAR in Week 2: place the lane
Next, sort each movement into operating, investing, financing, or noncash under the stated exercise. Working-capital changes and the operating bridge belong together. Cash paid for long-lived assets is an investing fact in these simplified exercises. Borrowing, principal repayment, equity cash, and distributions are financing candidates. An asset-for-shares exchange without cash belongs in a noncash review. Your proof is a lane sort completed without calculating a total first.
Pass cash flows CPA FAR in Week 3: change one fact
Meanwhile, keep the route stable while changing one fact. Turn an accounts-receivable increase into a decrease, change a borrowing amount, add a cash payment to an exchange, or replace a payment fact with later depreciation. Say which line changed and why the output moved. Do not change five facts at once: that makes it impossible to tell whether the method transferred.
Pass cash flows CPA FAR in Week 4: transfer under a clock
Finally, use a short mixed set with the time limit secondary to the explanation. Name the output, build the route, check the lane, and then review noncash treatment. After each item, record the first broken step. A timed block that produces a clear repair plan is better evidence than a fast block that leaves the error unexplained.

Weekly checkpoint: the route is producing useful evidence when a new prompt immediately yields “output, controlling fact, lane, next proof.” If you still reread every chapter after a miss, narrow the next block to the first broken field. That is a realistic pass action; it is not a promise of an outcome.
Use one repeatable 45-minute pass block
A fixed block lets you collect comparable evidence without turning study into a vague endurance contest. Spend five minutes reading prompt verbs and predicting the output. Spend twelve minutes labeling facts. Use fifteen minutes for one bridge or lane sort. Reserve eight minutes for a changed-fact retry. Finish with five minutes to write the first error and the next proof. If you only have 20 minutes, use 3, 6, 7, 3, and 1 minute in the same order.
Pass cash flows CPA FAR worked example: Cedar Market
Cedar Market reports net income of $74,000, depreciation of $9,000, an accounts-receivable increase of $6,000, an inventory decrease of $2,500, and an accounts-payable increase of $3,500. Under a simplified indirect-method exercise, cash from operations is $83,000: $74,000 + $9,000 – $6,000 + $2,500 + $3,500. The useful proof is the route, not the total alone. Depreciation is a noncash add-back, the receivable increase uses cash, the inventory decrease releases cash, and the payable increase supplies cash.
Now change only one fact: accounts payable decreases by $3,500 instead of increasing. The total becomes $76,000 because the payable line changes from plus $3,500 to minus $3,500. If the sign is correct but the result is placed in investing, the next block should be a lane sort. Conversely, if the lane is correct but the sign is wrong, run an adjustment drill. That is how a pass goal becomes a next action instead of a motivational slogan.
Editorial boundary: the route and Cedar Market example are original CPA Exam Prep editorial content checked against the current AICPA Blueprint boundary and the FASB Codification entry point on September 22, 2026. The exercise is not an official-source question and is not a readiness measure.
Original practice prompts: test the exact skill
Use one 20-minute attempt. Before opening the answer, write the requested output, controlling fact, lane, and nearest distractor for each prompt. These are original editorial exercises, not provider-owned question material. In practice, accuracy matters, but the first broken reason matters more for choosing your next block.
Prompt 1: operating bridge
Redwood Media reports net income of $51,000. Depreciation is $8,000, accounts receivable decreases by $5,000, and accounts payable decreases by $2,000. Under a simplified indirect-method presentation, what is cash provided by operating activities?
Prompt 2: equipment payment
Lumen Labs pays $27,000 cash for testing equipment. Which amount and lane describe the purchase-date cash effect? Ignore later depreciation.
Prompt 3: debt movement
Orion Foods borrows $42,000 in cash and repays $17,000 of principal during the same period. Ignore interest. What is the net financing cash flow?
Prompt 4: share-for-land exchange
Pine Ridge acquires land with a fair value of $24,000 by issuing shares directly to the seller. No cash is paid at signing. What treatment fits the stated facts?
Reveal the original practice routes
Complete all four prompts before opening the answer. Record the requested output, controlling fact, lane, and one distractor.
Reveal the answer
Answer: Redwood CFO is $62,000; Lumen is a $27,000 investing outflow; Orion is a $25,000 financing inflow; Pine is a noncash share-for-land exchange.
Compare your process with the reasoning shown above.
Let the first error choose the next pass block
After attempting the prompts, review the routes. Redwood is $62,000 of operating cash: $51,000 + $8,000 + $5,000 – $2,000. Lumen is a $27,000 investing outflow because the question asks for cash paid for a long-lived asset. Orion is a $25,000 financing inflow because $42,000 borrowed less $17,000 repaid equals $25,000. Pine is a noncash share-for-land exchange at the acquisition date because no cash moved.
Use four error tags. Tag output when you answered a different question than the prompt asked. Tag adjustment when you reversed a receivable, inventory, payable, prepaid, or noncash sign. Mark activity when an asset or debt movement landed in the wrong statement lane. Finally, tag disclosure when an exchange without cash was reported as if cash moved.

Repair rule: output errors get a five-minute prompt scan; adjustment errors get a 10-minute sign drill; activity errors get a 10-minute lane sort; disclosure errors get a 10-minute cash-versus-noncash rewrite. Finish the repair by changing one fact and explaining what moved. Do not start another mixed set until you can state the controlling fact in one sentence.
Compress the pass route when time is short
For a 20-minute block, protect the output scan, one bridge or lane sort, and a one-line error log. At 45 minutes, use the full block and complete one changed-fact retry. With 90 minutes, run two different patterns, take a short break, and spend the final 15 minutes explaining both first errors. More minutes should add a useful second pattern, not a longer introduction.
When the exam date is close, compress the calendar but preserve the progression: output and bridge first, lane and noncash next, mixed transfer after that, and timed practice last. When the date is farther away, use the four-week version and revisit the same weak area after 48 hours. A concrete next action is “run three receivable/payable sign drills and change one payable fact,” not “study FAR more.”
Use the current FASB Accounting Standards Codification when entity type, reporting date, cash-flow method, disclosure scope, or effective date changes. The FASB Codification overview is a research entry point, not a replacement for the specific current Topic. Keep these original prompts separate from official source material.
Pass cash flows and accrual accounting on CPA FAR FAQ
Can a study plan guarantee that I will pass?
No. A plan can make the work observable and help you repair a defined weakness, but it cannot promise an exam outcome. Use the weekly proof to decide what to do next, not to claim a probability.
Should I memorize formulas before fact patterns?
Learn the direction of common adjustments, but put the prompt output first. A formula without a controlling fact can produce a polished answer to the wrong question.
How often should I change the practice facts?
Change one fact after each miss. Once you can explain the changed result, move to a genuinely different pattern. Changing everything at once makes the repair impossible to audit.
When should I check official sources again?
Check the current Blueprint when scope or skill language changes. Check current FASB guidance when entity, reporting date, method, disclosure scope, or effective-date facts change.