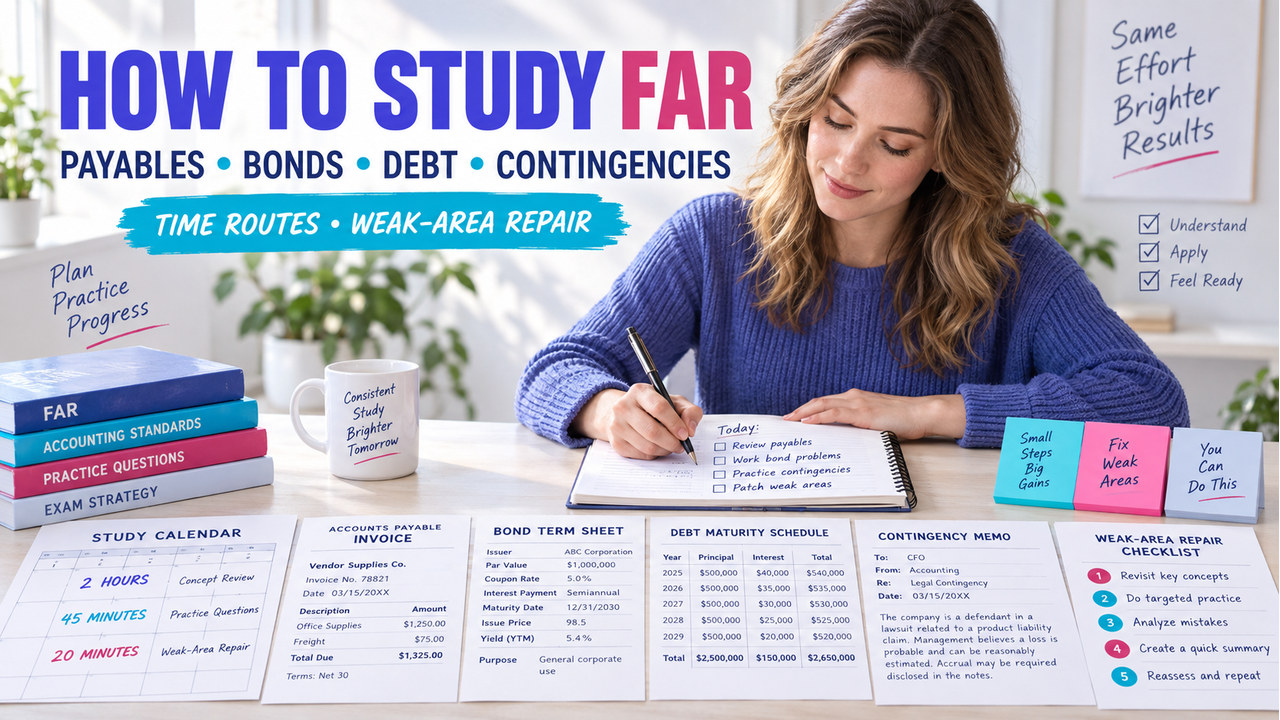

Direct answer: To study payables bonds debt and contingencies for CPA FAR, choose a time route first, then study each lane through the same evidence trail: source, date, measurement, classification or judgment, and requested response. Next, use the 2-hour route for a new map, the 45-minute route for a weak area, and the 20-minute route for a focused retry. Finally, finish with one original checkpoint and one proof you can inspect later.
Editorial review: The CPA Exam Prep editorial team checked the topic boundary against the current AICPA Blueprint and saved the FASB research checkpoint on September 24, 2026. Additionally, the schedule, examples, cases, visuals, and repair actions are original simplified study material. Therefore, the goal is a better next study block, not a score promise.
For scope, reopen the AICPA CPA Exam Blueprint. Next, for technical conclusions, use the current FASB Accounting Standards Codification. Meanwhile, the NASBA CPA Exam FAQ covers administration separately.
What to study in payables, bonds, debt, and contingencies
At the outset, divide the topic into five study lanes. In practice, payables asks which document and date create the obligation. Moreover, bonds ask whether the requested output uses face amount, carrying amount, coupon, yield, and elapsed period. By contrast, debt asks what principal belongs in current or noncurrent presentation at the reporting date. In addition, contingencies ask you to separate probability from estimability. Ultimately, accrual work turns a rate and elapsed period into the requested amount.
- Source: invoice, receiving report, term sheet, maturity schedule, or counsel memo.
- Date: receipt, reporting, payment, maturity, or elapsed days.
- Measurement: face, carrying amount, coupon, effective yield, rate, or period.
- Classification: current versus noncurrent principal at the reporting date.
- Judgment and response: probability, estimate, recognition, disclosure, or the exact requested unit.
As a result, do not begin by rereading four chapters in sequence. Instead, begin by naming the lane and the proof it should leave. In turn, a dated timeline, labeled formula, maturity split, probability note, or time fraction makes the session inspectable. If the proof is missing, the next block is obvious.
Choose a study route for payables bonds debt and contingencies
To begin, choose the route from your available time and recent error pattern. However, do not treat a longer session as automatically better; a narrow repair with a changed fact can be more useful than another broad reread. Accordingly, let the proof you need determine the size of the block.
For a long block, map all five lanes, read bounded notes, solve two cases, and keep one proof per lane.
For a repair block, choose one weak lane, change one fact, solve three variations, and explain one distractor.
For a focused retry, rebuild one broken field, solve one new case, and write the rule in your own words.

Use the 2-hour study payables bonds route for a new topic map
First, spend 15 minutes marking the Blueprint boundary and the four core clusters. Next, spend 25 minutes building a five-lane sheet. Then use 45 minutes for payables and bonds, 25 minutes for debt and contingencies, and 10 minutes to explain your two nearest distractors. Finally, leave five minutes for a dated next block. Moreover, the output is not a chapter count; it is a set of proofs that show what you can reproduce.
Use the 45-minute study payables bonds route for a weak area
To begin, start with the last wrong answer. In contrast, do not choose the topic that feels most comfortable. Then name the first broken field, review only that rule, change one fact, and solve three short variations. For example, if the missed field was bond measurement, keep the same principal but change the carrying amount, yield, or requested unit. Consequently, close by writing why the nearest distractor fails. In other words, the repair should explain a cause, not just record a miss.
Use the 20-minute study payables bonds route for a focused retry
For a focused retry, use this route the day after a miss or before mixed review. First, spend five minutes rebuilding the missing timeline, formula, split, or judgment note. Next, solve one changed-fact case without notes. Then explain the answer aloud or in two sentences. As a result, the short route exposes whether the rule transferred instead of allowing another long reread to hide the gap. In practice, this is the fastest check of transfer.
Worked example: study payables bonds through one evidence trail
Use one worked example to practice the trail rather than memorize a number. For example, a bond has a $900,000 carrying amount, an 8% annual effective yield, and a requested three-month interest expense. In this case, the controlling lane is measurement, and the requested unit is expense for three months. Therefore, calculate $900,000 × 8% × 3/12 = $18,000.
Proof to keep: write carrying amount, effective yield, and three months beside the formula. The cash coupon could be a nearby distractor, but it is not the requested output. Consequently, change one fact: ask for six-month cash interest on a $900,000 face amount at a 6% coupon. That separate question uses $27,000. In addition, the point is to label the unit before the arithmetic.
Original study payables bonds debt and contingencies checkpoints
These six checkpoints are original simplified practice, not official questions. First, read the skill, assumptions, and difficulty. Beforehand, write the requested unit. Then attempt each case before opening its answer. Afterward, record the first broken field and schedule the narrowest route above.
1. Source and cutoff
Tested skill: identify when an accepted payable enters the period. Assumptions: goods were accepted before year-end and no return is stated. Difficulty: foundational. A company received and accepted $64,000 of inventory on December 30. The invoice arrived January 5 and cash was paid January 21.
Question: What simplified payable belongs at December 31?
- A. $0 because the invoice arrived in January
- B. $64,000 because accepted goods were received before year-end
- C. $21,000 because that is the payment date
- D. $85,000 because invoice and cash are combined
Reveal Checkpoint 1
Answer: B. Thus, the receiving evidence controls the year-end obligation in this simplified case. Option A follows invoice entry, C follows cash, and D invents an addition. Next action: draw receipt, invoice, and payment on one timeline.
2. Bond measurement
Tested skill: apply effective interest to carrying amount. Assumptions: the rate is annual and the period is six months. Difficulty: measurement. A bond has a $810,000 carrying amount and a 6% annual effective yield.
Question: What simplified six-month expense should be calculated?
- A. $20,250
- B. $24,300
- C. $48,600
- D. The face amount multiplied by a coupon that is not supplied
Reveal Checkpoint 2
Answer: B. Therefore, use $810,000 × 6% × 6/12 = $24,300. Option A uses a shorter period, C uses a full year, and D substitutes an unavailable cash-interest fact. Next action: write the requested output and period before choosing an input.
3. Current portion
Tested skill: classify principal at the reporting date. Assumptions: only principal is requested and no refinancing exception is stated. Difficulty: classification. A note has $210,000 due in the next twelve months and $590,000 due later.
Question: What current portion belongs in the simplified presentation?
- A. $0
- B. $210,000
- C. $590,000
- D. $800,000
Reveal Checkpoint 3
Answer: B. As a result, current principal is the amount due within the next twelve months. Option C selects the later amount, while D fails to split the note. Next action: anchor the split to the reporting date before calculating interest.
4. Probability without a reliable estimate
Tested skill: separate probability from estimability. Assumptions: the loss is probable, but counsel cannot yet make a reasonable estimate. Difficulty: judgment. No reimbursement is stated.
Question: Which simplified response fits the facts?
- A. Recognize any amount requested by the claimant
- B. Disclose the contingency without inventing a recognized amount
- C. Ignore it because cash has not been paid
- D. Recognize a zero liability and stop reviewing
Reveal Checkpoint 4
Answer: B. However, probability alone does not supply a reliable measured amount in this simplified case. Option A replaces an estimate with a demand, C confuses cash with reporting, and D treats zero as a conclusion. Next action: write probability and estimate on separate lines.
5. Elapsed interest
Tested skill: accrue interest for a stated period. Assumptions: use a 360-day year and simple daily accrual. Difficulty: time-apportioned calculation. A $500,000 note carries a 6% annual rate, and 90 days have elapsed.
Question: What simplified accrued interest should be recorded?
- A. $2,500
- B. $7,500
- C. $30,000
- D. $45,000
Reveal Checkpoint 5
Answer: B. Thus, $500,000 × 6% × 90/360 = $7,500. Option A uses one month, C uses a full year, and D uses too many days. Next action: write annual amount, elapsed days, and denominator before entering the rate.
6. Cash interest
Tested skill: return cash interest instead of effective expense. Assumptions: interest is paid semiannually. Difficulty: requested-unit control. A $900,000 bond has a 6% annual coupon.
Question: What six-month cash interest is paid?
- A. $13,500
- B. $27,000
- C. $54,000
- D. Carrying amount multiplied by effective yield
Reveal Checkpoint 6
Answer: B. In this case, cash interest uses face amount and coupon: $900,000 × 6% × 6/12 = $27,000. Option A uses one quarter, C uses a full year, and D answers expense. Next action: write “cash” or “expense” above the formula.
Repair the first error instead of rereading all four topics
Next, classify the first broken field. A source error means the invoice, receiving report, term sheet, maturity schedule, or memo was not used. In addition, a date error loses the reporting or elapsed period. Similarly, a measurement error mixes face, carrying amount, coupon, or yield. In contrast, a classification error leaves current and noncurrent principal unsplit. Finally, a judgment error combines probability and estimation.
For example, after Checkpoint 1, rebuild the three-date timeline. After 2 or 6, label the requested unit and inputs. Then, redo a maturity split after Checkpoint 3. For Checkpoint 4, change only the estimate field. Finally, change the elapsed days after Checkpoint 5. In contrast, rereading every topic hides the field that actually failed.

Make study payables bonds debt and contingencies repeatable
Close every session with three small proofs: one corrected workpaper, one distractor explanation, and one changed-fact problem solved without notes. Therefore, use the 2-hour route to build breadth, the 45-minute route to repair a lane, and the 20-minute route to test transfer. If the proof fails, keep the lane and change one fact rather than restart the entire topic. In addition, write the next block before you leave the desk.
| First broken field | Proof to keep | Next block |
|---|---|---|
| Source or date | Dated document timeline | Three cutoff variations |
| Measurement | Labeled formula and requested unit | Two bond calculations |
| Classification | Dated current/noncurrent split | Two maturity schedules |
| Judgment or accrual | Probability note or time fraction | One changed-fact retry |
Refresh the study route
For live scope, reopen the current AICPA CPA Exam Blueprints. For technical accounting, research the current FASB Codification before turning a simplified checkpoint into a reporting conclusion. Meanwhile, the AICPA sample test can help with format, but it does not determine readiness.
Finally, before reuse, check the Blueprint effective date, update any changed assumptions, and keep the first-error log. In addition, leave Semrush US volume and KD open until the row-level refresh is complete. As a result, a useful study plan stays bounded, current, and specific about the next action.
Study payables bonds debt and contingencies FAQ
How should I start if I have two hours?
For a two-hour block, map the five lanes, solve one case in each, and keep a dated proof for every lane before mixed review.
What if I only have 20 minutes?
With only 20 minutes, choose the first broken field, rebuild it, solve one changed-fact problem, and explain the nearest distractor.
Should I memorize bond numbers?
Instead, label the requested unit, carrying or face amount, rate, and period before calculating.
Does this method predict a CPA score?
Finally, remember that it produces a study action and a proof of transfer; it is not a readiness or score forecast.