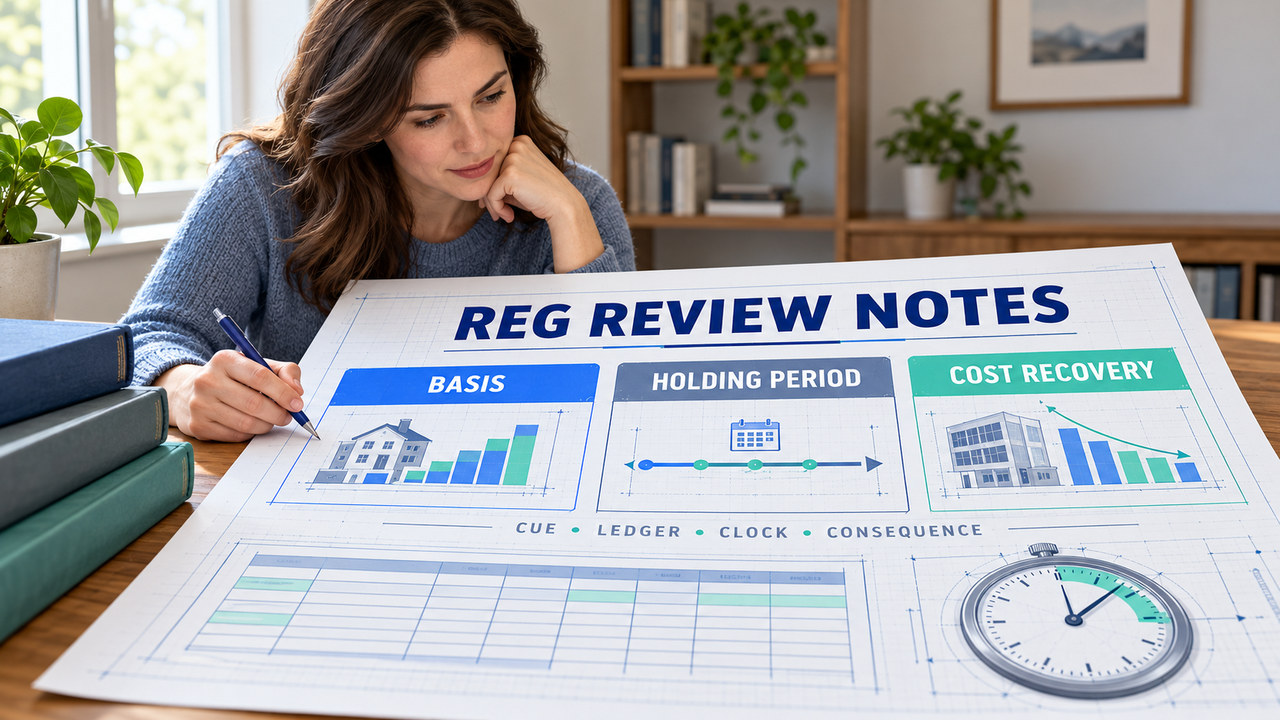

Direct answer: First, treat reg review notes as a compact audit trail. Capture the requested output, the owner, the item, the money line, the relevant dates, and the boundary that controls the result. After the answer, log the first unsupported step and run one changed-fact retry.
Scope and freshness note: However, the cases on this page are original editorial practice, never official, recalled, leaked, or exam-memory questions. Reopen the AICPA CPA Exam Blueprints for the current testing window and subject boundaries. Consult the NASBA FAQ for jurisdiction, eligibility, scheduling, or score matters.
In addition, use the REG review hub to orient the section. The CPA study guide supplies broader context, the Blueprint format guide clarifies task boundaries, and the topic MCQ page plus TBS practice guide offer alternate retrieval modes.
For a broader preparation path, continue with our related CPA study resources.
REG review notes: pin the requested output
Next, start by copying the last clause of the prompt into your note. An adjusted-basis request calls for a basis ledger. When the task asks for a holding period, preserve the event dates. For an entity consequence, identify the owner and the limitation, deduction, credit, or reporting boundary before doing math.
Next, use four labeled cells: cue, ledger, clock, and consequence. Cue states who owns what and what the question wants. Ledger lists cost, additions, recovery, income, or distributions. Clock lists acquisition, placement, transfer, contribution, and sale dates. Consequence states the requested tax effect and the condition that could change it.
REG review notes: cell one — cue
Before any formula, write a plain-language task label. “Remaining basis” and “sale result” are different prompts even when they share purchase price. “Owner basis before a limitation” is also different from an entity-level income question. Naming the output prevents a familiar rule from answering the wrong question.
REG review notes: cell two — ledger
Likewise, keep signs and units visible. A qualifying improvement belongs on an addition line. Cost recovery belongs on a subtraction line under the stated study facts. A contribution, distribution, or separately stated item needs its own row when the owner-level sequence matters.
REG review notes: cell three — clock
Meanwhile, record dates as events, not as a vague “holding period” phrase. Acquisition, placement in service, transfer, and sale can have different roles. When one date moves, mark the clock cell for a fresh check rather than rewriting every other cell.
REG review notes: cell four — consequence
Finally, end with one sentence that ties the controlling fact to the requested result. Add a boundary note when the prompt is simplified. Current authority, jurisdiction, and entity elections belong in the reopen list rather than in an invented answer.
Set the study-guide review assumptions
For example, for each review block, choose one narrow Blueprint row. A short session might isolate basis arithmetic plus the event clock. Another session can isolate an owner-level limitation or an entity reporting result. This scope is small by design; it makes a missed line visible.
Then, write the assumption above the numbers. For example, say that the case supplies all relevant amounts, uses simplified recovery facts, and asks only for the requested study output. Leave a blank “reopen” line for a current rate, election, jurisdiction rule, or entity classification that the case does not state.

REG review notes: draw a margin map
In practice, a margin map lets you scan the reasoning in the same order each time. Put the prompt cue at the top, the money line under it, the event clock beside it, and the consequence at the bottom. Beside each line, add a short proof tag: supplied fact, calculation, boundary, or changed detail.
For example, suppose the prompt supplies $68,400 of equipment cost, a $7,600 upgrade, and $21,200 of stated recovery. The ledger reads $68,400 + $7,600 − $21,200 = $54,800. That arithmetic answers a remaining-basis request under the supplied assumptions; it does not answer a sale-period question without the dates.
REG review notes: reject the wrong path
Also, reserve one line for the strongest distractor. It may omit the upgrade, add recovery instead of subtracting it, merge acquisition and sale dates, or skip the owner-level sequence. A one-sentence rejection shows which proof step deserves the next drill.
REG review notes: use a source cue
As a result, when a rule boundary can change, write the authority to reopen and the date you checked it. The note is a study aid, not a live tax opinion. This small caveat protects the review from turning a simplified classroom assumption into a universal conclusion.
REG review notes: test three original entries
Before reading an explanation, attempt each case. Write the four cells, select a response, and mark the line that carried the decision. The amounts and fact patterns are original study material.
Reveal the reasoning
Before opening the explanation, write the owner, item, amount, controlling date, requested result, and evidence source you would reopen.
Reveal the answer
Answer: Compare your note with the rationale, mark the first missing proof point, and retry one case after changing one fact.
Compare your process with the reasoning shown above.
Entry 1: upgrade, recovery, and a later sale
Fact pattern: Meanwhile, an individual buys a machine for $68,400, adds a qualifying upgrade for $7,600, and records $21,200 of stated recovery before selling it. The prompt asks for the basis used in the next computation and the evidence needed for a holding-period check.
Which entry is defensible?
- A. $68,400, because the upgrade is separate.
- B. $54,800, because $68,400 + $7,600 − $21,200 is the supplied ledger; keep the acquisition, upgrade, and sale events on the clock.
- C. $97,200, because recovery increases basis.
- D. The sale date is the basis amount.
Answer and rationale: Choice 2 preserves both parts of the note. The ledger produces $54,800 under the stated facts, while the clock remains open for the holding-period question. Each other choice drops, reverses, or substitutes an input.
Entry 2: owner basis and a separately stated item
Fact pattern: Similarly, a shareholder starts with $33,500 of stock basis, contributes $4,800, receives a $6,200 distribution, and is allocated a separately stated $3,700 item. The prompt asks what should appear before any limitation or character analysis.
Which record comes first?
- A. A final limitation number with no owner ledger.
- B. A single net amount that hides the contribution and distribution.
- C. Beginning basis, each owner-level transaction, the separately stated item, and the boundary named by the question.
- D. The distribution automatically given the same character as the separate item.
Answer and rationale: Choice 3 preserves the owner sequence before a later boundary is applied. The other options either erase evidence or assume a tax character that the prompt has not established.
Entry 3: entity change and recovery
Fact pattern: Finally, an entity buys equipment for $112,000 and records $19,000 of stated recovery. The original prompt requests remaining basis. A revised prompt changes the owner and asks what must be revisited.
Which response transfers?
- A. Remaining basis is $93,000 under the supplied facts; the changed owner triggers a fresh deduction, credit, limitation, or reporting check.
- B. Remaining basis is $131,000 because recovery is outside the ledger.
- C. The owner change cannot affect the result after cost is known.
- D. Holding period alone resolves the new owner question.
Answer and rationale: Choice 1 computes $112,000 − $19,000 = $93,000, then reopens the consequence cell for the new owner. The alternatives reverse the arithmetic or carry an old boundary into a new fact pattern.
Choose the next study-guide review repair
Therefore, when an entry fails, name the first unsupported cell. Misread cues answer the wrong question. Ledger errors drop or reverse a number. Timing errors blend events. Boundary errors apply a rule outside the supplied facts. Transfer errors appear when one detail changes.

REG review notes: carry one changed detail
Consider a second case with $74,500 of cost, an $11,500 improvement, and $16,000 of stated recovery. Step 1 produces $70,000: $74,500 + $11,500 − $16,000. Step 2 records acquisition, improvement, placement, and sale as separate events. If the prompt asks only for remaining basis, stop at the ledger and label the assumption.
Now change the improvement to $15,500. The ledger becomes $74,000 while the clock stays intact. Move the sale date instead, and the timing cell needs review while the money line stays unchanged. Change the owner, and the consequence cell needs a new limitation or reporting check. One changed detail should point to one affected cell.
REG review notes: save the repair
After the repair, keep the failed entry, changed fact, affected cell, and next practice action together. This record is more useful than a general confidence score because it tells you what to inspect on the next item. Return to one fresh case after the repair, then decide whether a larger set will add evidence.
REG review notes: stress-test the entry
As a result, transfer is proven when a small fact change produces a predictable update. When an improvement grows, the ledger changes. A moved sale event changes the clock. Changing the owner changes the consequence boundary. Meanwhile, unaffected cells remain visible, which keeps the retry controlled.
If the next action cannot be stated, pause the mixed set. Rebuild the cue when the question was misread. Recalculate one line when the sign is wrong. Write two events when timing is blurred. Reopen the boundary when the owner or requested output changed. A bounded retry gives the next question a purpose.
REG review notes checklist
- Copy the requested output into the note.
- Fill cue, ledger, clock, and consequence in that order.
- Show additions, subtractions, units, and owner-level transactions.
- Keep acquisition, placement, transfer, contribution, and sale events separate.
- Write the strongest rejected path and why it fails.
- List the authority or boundary that needs a fresh check.
- Tag the first unsupported cell and choose one bounded repair.
- Retry after changing one detail before adding volume.
REG review notes FAQ
Are these official exam questions?
No. The cases and rationales are original editorial practice. Use current AICPA sources for authoritative scope.
What belongs in a review note?
Record the requested output, owner, item, money line, event clock, boundary, rejected distractor, and next retry.
Should I add more timed questions after a miss?
Repair the first unsupported cell before increasing volume; otherwise the same error can repeat invisibly.
Does this method promise a score?
No. It creates study evidence and a targeted next action; current rules and performance determine the actual result.
Sources
- AICPA CPA Exam Blueprints
- AICPA CPA Exam resources
- NASBA CPA Exam FAQ
- REG review hub