Author: CPA EXAM PRACTICE
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Four-Signal Review
Direct answer: A useful far nonprofit taxes subsequent review session starts by naming the reporting signal that controls the item. Label the entity and fund, trace any restriction, separate tax basis from book presentation, place the event on a date line, and write the evidence that would change your conclusion. Then attempt an original case… Read more
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Evidence Notebook
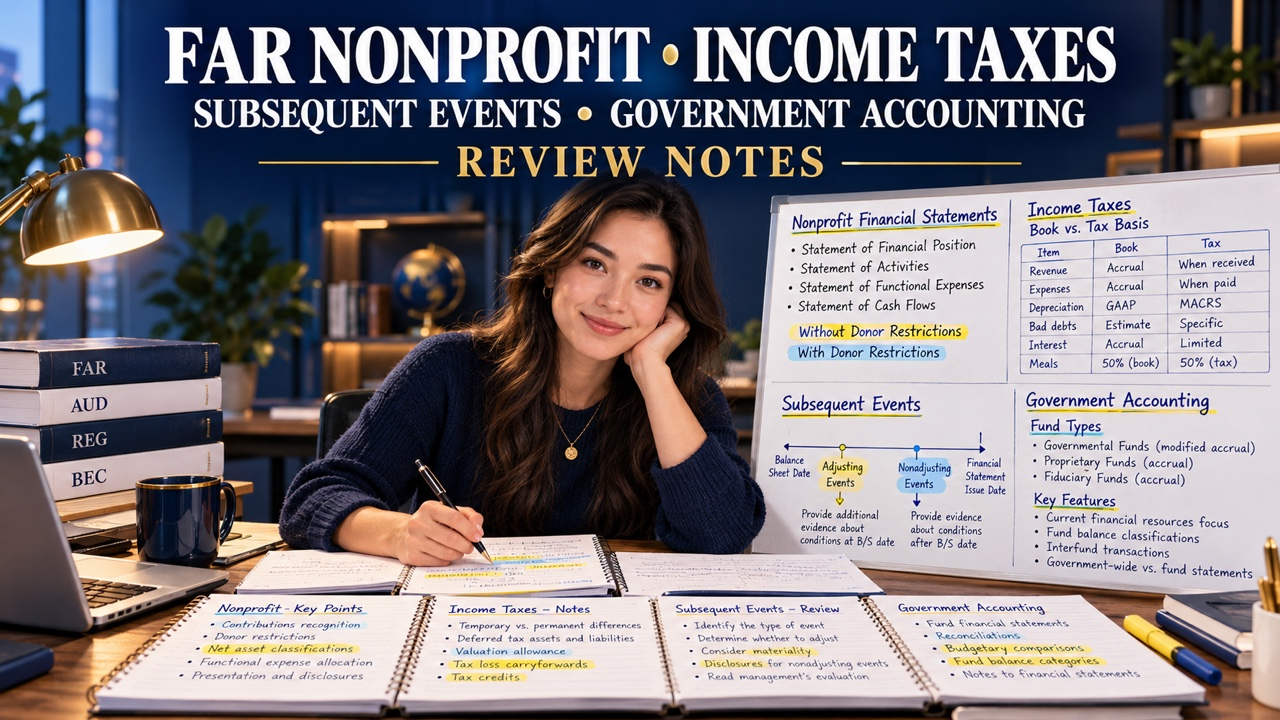
Direct answer: Use nonprofit taxes subsequent review as an evidence notebook, not as a list of loose reminders. For every item, write the requested verb, the reporting lane, the date that controls the analysis, the fact that could redirect it, and the record that would settle the point. Then change one fact and explain whether… Read more
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Evidence Map
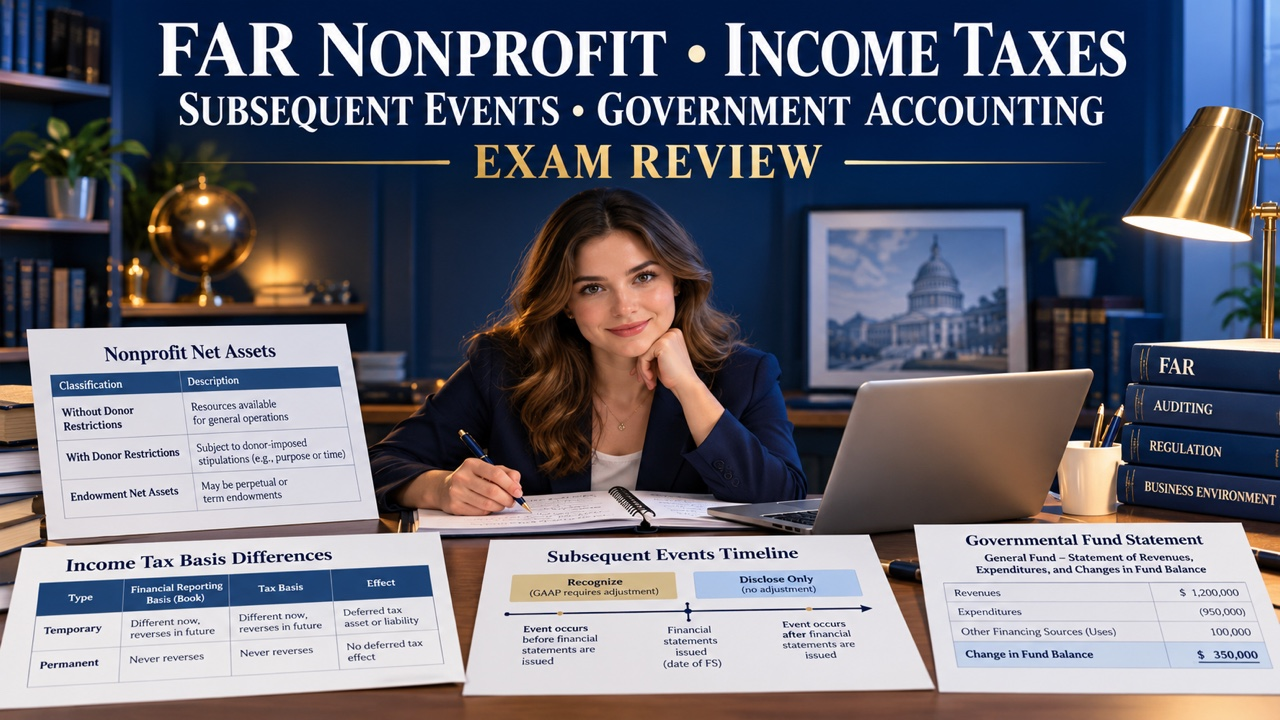
Direct answer: Build a study map for nonprofit taxes subsequent study before solving a question. Put the reporting date, the task verb, the lane, the decisive fact, and the evidence ledger on one page. Then change one input and write what remains true. The examples here are original editorial practice for FAR learners. In this… Read more
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Timed Review
Direct answer: Use nonprofit taxes subsequent practice as a timed review with a visible trail. Start the clock only after you write the task verb, the reporting lane, the fact that can change the route, and the document you would inspect. After each original item, alter one input and record what stays fixed. This is… Read more
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Quiz Lab
Direct answer: Use nonprofit taxes subsequent quiz as a decision lab. Read the verb, select the reporting lane, identify the fact that can move the answer, and write the document that would settle the issue. Then alter one fact and rerun the route. The quiz below is original editorial practice for FAR learners; it is… Read more
-
FAR Nonprofit, Income Taxes, Subsequent Events, and Government Accounting: Decision Drills
Direct answer: Treat nonprofit taxes subsequent events as a sequence of decisions, not a list of answer letters. First identify the entity or tax fact, then name the recognition or disclosure question, set the timing boundary, and record the exhibit that supports the choice. After each original item, change one fact and explain whether the… Read more
-
FAR Financial Instruments, Fair Value, Equity Method, and Consolidations: Original Practice
Direct answer: Use free far financial instruments practice questions as a proof packet, not a pile of answer letters. Before choosing, write the requested action, the decisive detail, the limit on that detail, and the record you would inspect. After the answer, change one input and explain what survives. The questions on this page are… Read more
-
FAR Financial Instruments, Fair Value, Equity Method, and Consolidations: Study Guide
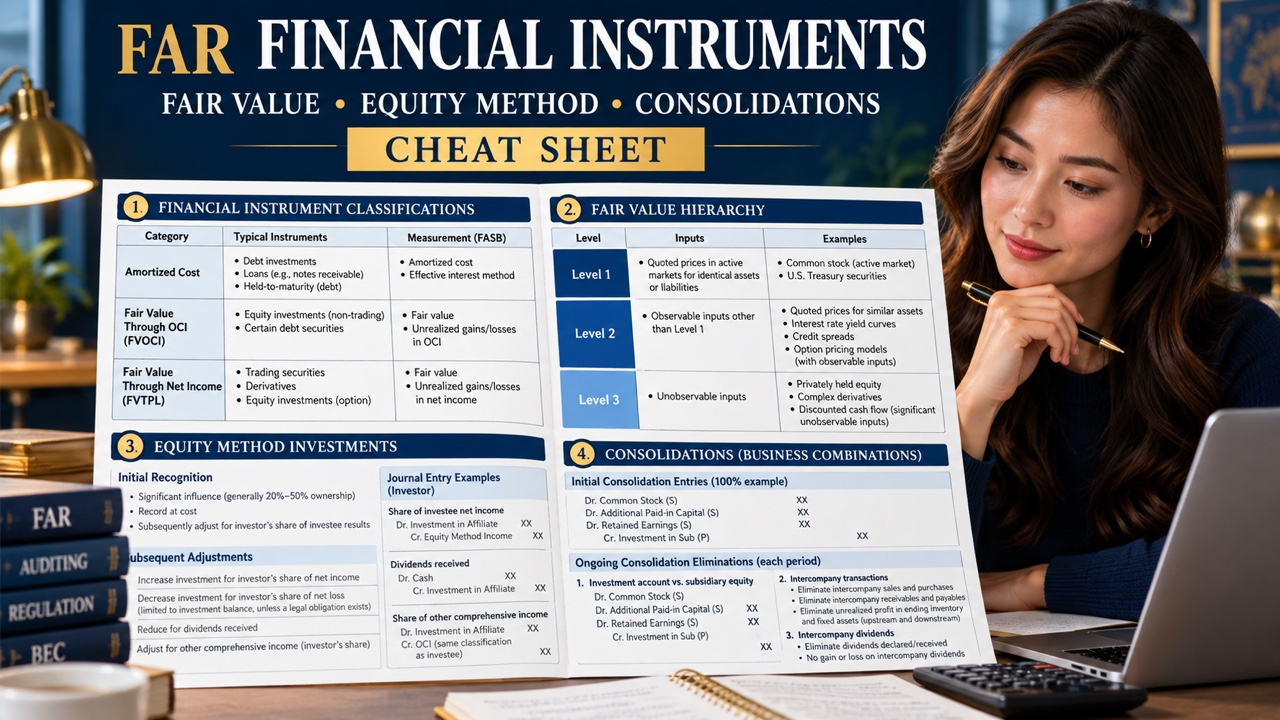
Direct answer: Treat far financial instruments fair drill as an evidence-routing exercise. Read the requested verb, choose the fact that can redirect the route, set a scope lock, and write the record that would let another reviewer retrace the choice. Only then perturb one input and see whether the route survives. The examples on this… Read more
-
FAR Financial Instruments, Fair Value, Equity Method, and Consolidations: Flashcard-to-Case Drills
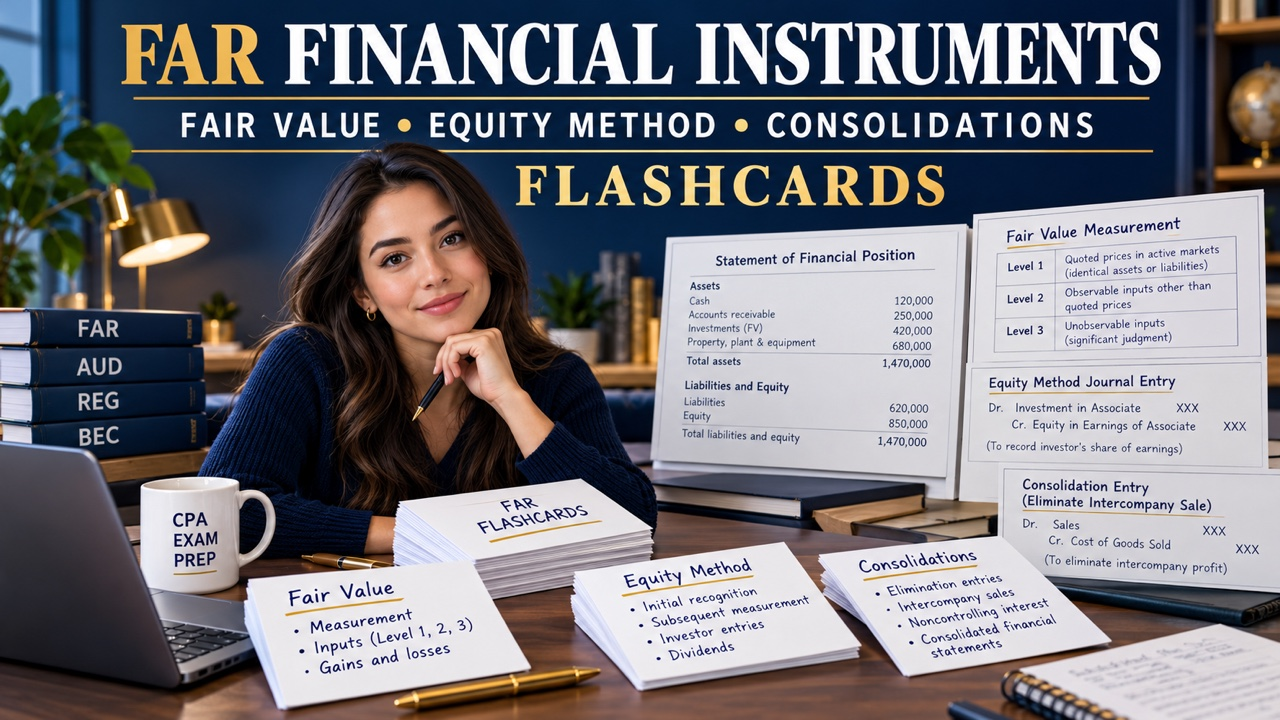
Direct answer: Turn fair value equity method flashcards into decisions, not recognition drills. On every card, write the requested output, the fact that controls it, the boundary that limits it, and one record that would prove it. Then change one fact and try again. The cases here are original study material, not official or recalled… Read more
-
FAR Financial Instruments, Fair Value, Equity Method, and Consolidations: Decision Notes
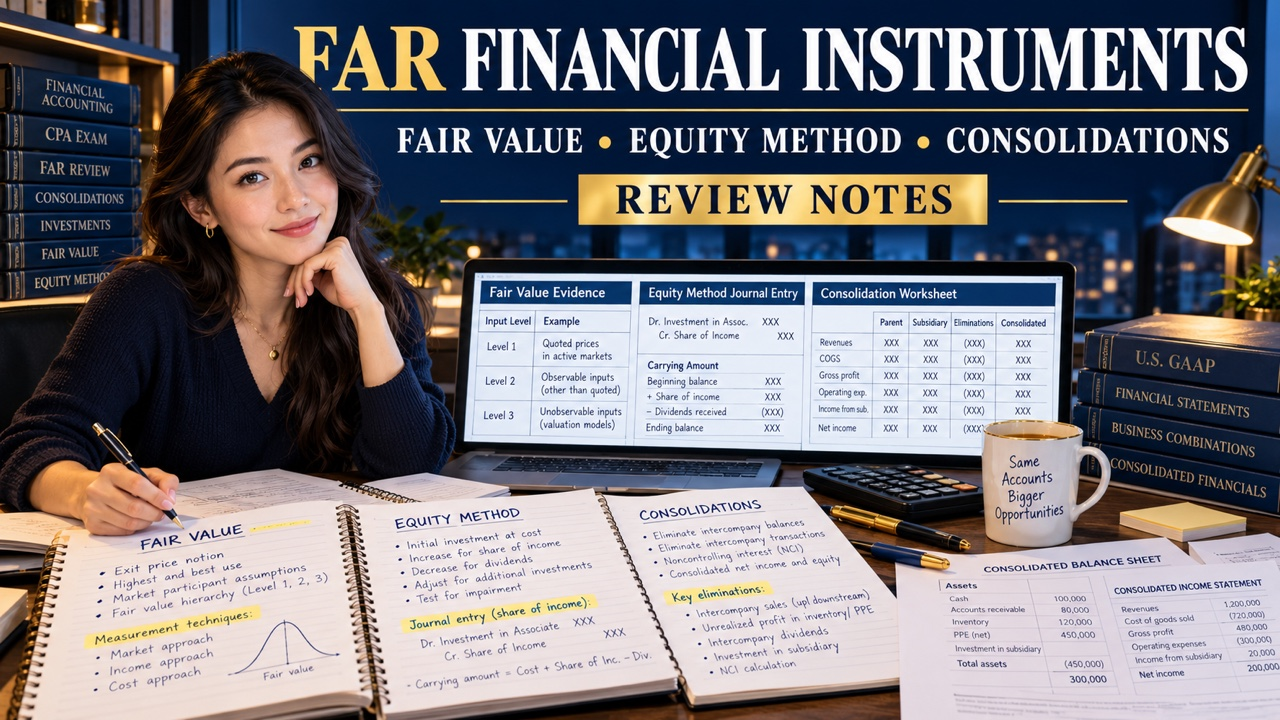
Direct answer: Use far financial instruments fair decision notes as a short audit trail. Next, write the requested output, isolate the fact that can change it, name the boundary, and record the document you would reopen. Then attempt the original cases below before reading the rationales. This is independent study material, not an official question… Read more