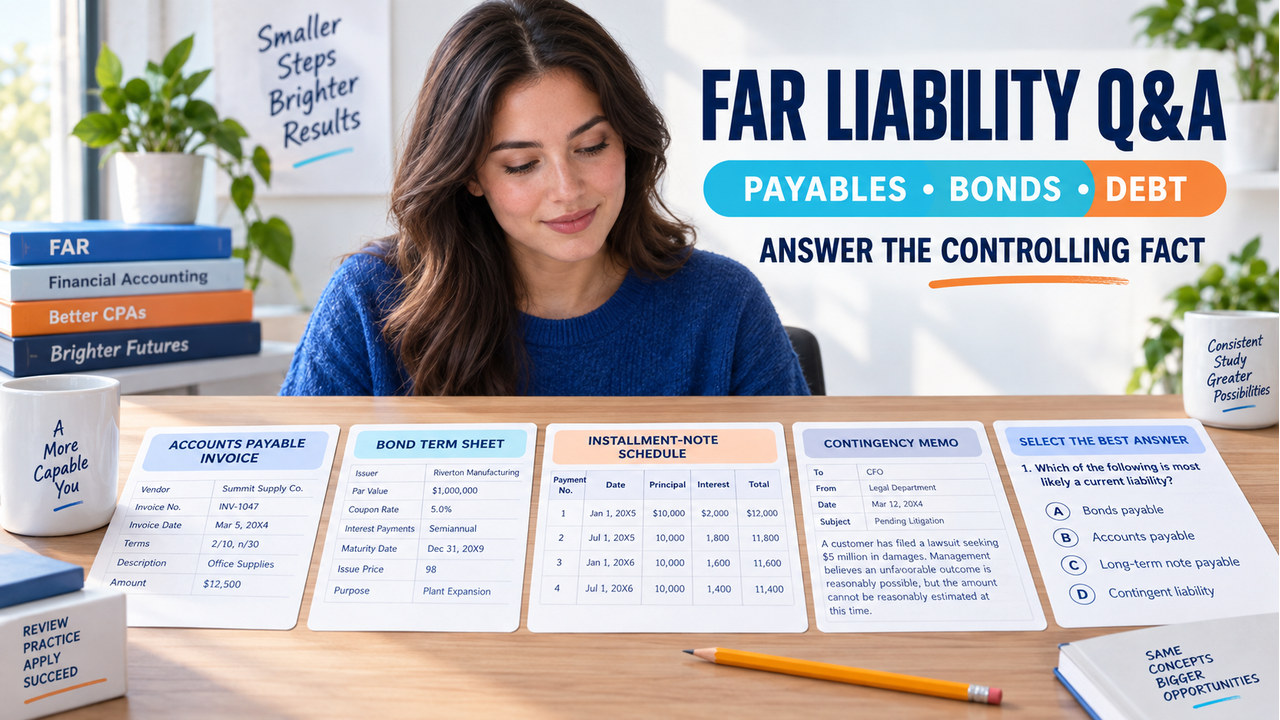

Direct answer: The most reliable way to use payables bonds questions and answers is to write the controlling fact and the requested answer unit before checking the explanation. Ask whether the item wants a liability amount, interest expense, current portion, disclosure, or presentation. Then separate the nearest distractor from the correct response. The six original cases below are simplified study material created for this page; they do not represent live exam content. Read each question first, choose an option, and only then open the answer. In particular, do not let a familiar number choose the answer before the fact pattern does.
Editorial review: Meanwhile, the CPA Exam Prep editorial team checked the topic scope against the current AICPA Blueprint and linked FASB research boundary on September 24, 2026. The cases, options, amounts, rationales, visuals, and review actions are original simplified material, not provider-owned item-bank content, a licensed accounting opinion, or a score prediction.
For scope, reopen the AICPA CPA Exam Blueprint. For technical conclusions, use the current FASB Accounting Standards Codification. The NASBA CPA Exam FAQ remains a separate administration checkpoint.
How payables bonds questions and answers find the controlling fact
First, before choosing a letter, name the question’s verb. “How much?” usually asks for an amount. Next, “What is current?” asks for classification or presentation. However, “What should be reported?” may ask for recognition or disclosure. Finally, “Why?” asks for the fact that makes one response fit. This small distinction prevents a common mistake: answering a real accounting question that the prompt did not ask.
- Fact: mark the receipt, return, maturity date, yield, probability, estimate, or elapsed time.
- Unit: label liability, expense, current portion, disclosure, or carrying amount.
- Rule: apply the simplified test stated in the question and note any assumption.
- Why: explain why the nearest distractor uses the wrong field, date, rate, or unit.
As a result, a question and answer becomes more useful when the answer shows the transfer rule. For example, a learner who can say “net receipt, not invoice total” has a stronger repair than a learner who only remembers a letter. Similarly, “market yield, not coupon” is a reusable reason, while a memorized dollar amount is fragile.
Use payables bonds questions and answers as a controlling-fact routine
Next, write fact → unit → rule → why in the margin. Next, put one concrete fact beside each word. However, if the requested unit is unclear, reread the final sentence of the question. Similarly, if the rule is clear but the amount is not, write the formula with labels before calculating. Consequently, this routine keeps answer explanations connected to the work a new question will require. For example, label “expense” before multiplying a carrying amount by a market yield.
Date, amount, rate, estimate, or probability.
Liability, expense, portion, disclosure, or presentation.
Cutoff, yield, maturity, estimate, cost, or time.
Name the nearest distractor and repair.

Original payables bonds questions and answers
Overall, use a calendar year-end, no tax effects, no unusual elections, and only the facts stated in each question. Each case has one best answer under its simplified assumptions. The questions intentionally change the requested unit: net payable, effective interest, current portion, disclosure, debt-cost presentation, and accrued interest. Before reading the answer, say which field controls the result. Likewise, every explanation names the nearest distractor instead of stopping at the answer letter.
1. Payables after an approved return
Tested skill: determine the payable after a recognized return. Assumptions: goods were received and accepted before year-end, and the vendor approved the return before the statements were finalized. Difficulty: foundational application. A $120,000 shipment arrived on December 28. An $8,000 portion was returned and the vendor issued a credit memo on December 31. Nevertheless, the invoice still shows $120,000.
Question: What amount best represents the year-end payable under these simplified facts?
- A. $0, because the invoice needs to be reissued
- B. $112,000, because the approved return reduces the obligation
- C. $120,000, because the invoice total always controls
- D. $8,000, because the credit memo is the only amount to record
Reveal Question 1 answer and reasoning
Answer: B. Start with the accepted goods, then subtract the approved return: $120,000 − $8,000 = $112,000. However, option A confuses document processing with the obligation. Option C ignores the credit memo, and option D records the reduction rather than the net liability. Next action: draw gross invoice, approved reduction, and net payable as three separate lines.
2. Semiannual bond interest expense
Tested skill: use the market yield on the carrying amount. Assumptions: interest is paid semiannually, the issue is at a discount, and the supplied yield remains constant. Difficulty: calculation and classification. Meanwhile, an $800,000 bond has a 5% annual coupon, a $760,000 carrying amount at the start of the six-month period, and a 7% annual effective yield.
Question: What is the simplified six-month effective interest expense?
- A. $20,000
- B. $26,600
- C. $28,000
- D. $40,000
Reveal Question 2 answer and reasoning
Answer: B. Apply the annual yield for one-half year to the carrying amount: $760,000 × 7% × 6/12 = $26,600. For comparison, option A is the six-month cash coupon, $800,000 × 5% × 6/12. Option C applies the yield to face value, and option D uses a full year. Next action: label face, carrying amount, coupon, yield, and period before multiplying.
3. Current portion of an installment note
Tested skill: split a note between current and noncurrent portions. Assumptions: the question asks for principal due within the next twelve months at December 31. Difficulty: reporting presentation. Next, a $900,000 installment note requires $100,000 of principal in the next year and the remaining $800,000 later. Importantly, interest is not part of the requested principal split.
Question: What current portion should be presented?
- A. $0, because the note is described as long-term
- B. $100,000, because that principal is due within the next year
- C. $800,000, because most of the balance is long-term
- D. $900,000, because the whole note is payable
Reveal Question 3 answer and reasoning
Answer: B. The current portion is the principal scheduled within the next twelve months: $100,000. In contrast, option A relies on the instrument label, option C selects the later portion, and option D fails to split the balance. Next action: circle the reporting date and list only the principal maturities that fall to its right within twelve months.
4. Probable claim with no reliable estimate
Tested skill: keep probability and estimation as separate fields. Assumptions: use the simplified recognition-versus-disclosure exercise. Difficulty: judgment. In this case, counsel says a claim loss is probable, but the amount cannot yet be reasonably estimated. Therefore, the question asks for the simplified year-end response.
Question: Which response follows from the stated fields?
- A. Recognize any amount management prefers
- B. Ignore the claim because no cash has been paid
- C. Disclose the nature of the claim and the estimation limitation, without recording a made-up amount
- D. Record the claimant’s requested amount automatically
Reveal Question 4 answer and reasoning
Answer: C. The exercise gives probability but not a reliable estimate, so it does not support inventing a liability amount. Meanwhile, option A substitutes preference for measurement, option B uses cash timing, and option D treats an allegation as a measured loss. If the estimate later becomes a reliable $75,000 while probability remains probable, the response changes to recognition under this simplified exercise. Next action: write “probability” and “estimate” on separate lines before choosing recognize or disclose.
5. Debt issuance costs
Tested skill: identify the requested presentation unit for debt costs. Assumptions: the question uses a simplified presentation rule in which costs related to issuing a note are presented as a direct reduction of the note’s carrying amount. Difficulty: application. Finally, a company issues a $1,000,000 note and pays $30,000 of qualifying issuance costs.
Question: What carrying amount follows immediately after issuance under the stated simplification?
- A. $30,000
- B. $970,000
- C. $1,000,000 with no related presentation
- D. $1,030,000
Reveal Question 5 answer and reasoning
Answer: B. Under the stated rule, subtract the issuance costs from the note amount: $1,000,000 − $30,000 = $970,000. By contrast, option A records only the cost, option C ignores the requested presentation, and option D adds a cost that reduces carrying amount. Next action: write “note balance” and “issuance cost” on opposite sides of the presentation equation.
6. Accrued interest for 45 days
Tested skill: accrue interest for elapsed time. Assumptions: use a 360-day year and simple daily accrual. Difficulty: time-apportioned calculation. A $400,000 note carries a 9% annual rate. Consequently, forty-five days have elapsed since the last payment date, and no accrued interest has been recorded.
Question: What accrued interest should be recorded under the stated convention?
- A. $900
- B. $3,000
- C. $4,500
- D. $36,000
Reveal Question 6 answer and reasoning
Answer: C. Annual interest is $400,000 × 9% = $36,000. Apply 45/360 of the year: $36,000 × 45/360 = $4,500. Finally, option A uses a smaller rate, option B uses one month, and option D records a full year. Next action: write annual interest, elapsed days, and day-count denominator before calculating.
Review payables bonds questions and answers by first broken field
After each answer, first identify the first field that broke. A fact miss means you ignored the return, maturity, probability, or elapsed days. A unit miss means you answered with total debt instead of current portion, cash interest instead of expense, or cost instead of carrying amount. A rule miss means you chose the wrong rate, period, or recognition test. Finally, a distractor miss means you saw the correct number but did not explain why the nearest option failed.
For this reason, keep one repair beside each wrong answer. For Question 1, recalculate net receipt. Similarly, on Question 2, separate coupon from yield. Next, on Question 3, split current principal from later principal. For Question 4, change only the estimate. Then, on Question 5, restate the carrying amount. Finally, on Question 6, rebuild the day-count fraction. In short, the first broken field determines the next practice block.

Turn payables bonds questions and answers into a targeted review plan
Choose one ten-minute drill instead of rereading the whole topic. First, write three gross-to-net payable cases with a return or credit memo. Next, calculate cash interest and effective interest from two bond term sheets. Then, split an installment note at the reporting date. After that, change a contingency’s estimate while holding probability fixed. Finally, rebuild one debt-cost and one elapsed-time calculation. Consequently, keep the rationale, not only the letter, because the rationale shows whether the method transfers.
| First broken field | Ten-minute drill | Proof to keep |
|---|---|---|
| Fact | Mark receipt, return, maturity, estimate, and elapsed days. | The controlling fact is named. |
| Unit | Label liability, expense, current portion, disclosure, or carrying amount. | The requested output appears before the equation. |
| Rule | Separate coupon, yield, maturity, probability, estimate, cost, and time. | Each input has a named role. |
| Why | Write why the best answer wins and the nearest distractor fails. | The rationale answers the prompt’s verb. |
Research and refresh payables bonds questions and answers
For live conclusions, use the current AICPA CPA Exam Blueprints for scope and the current FASB Accounting Standards Codification for applicable debt, interest, payable, and contingency guidance. In addition, the AICPA sample test can help you learn exam software and format, but it is not a readiness determination. This page uses simplified facts and does not replace current research for a complete reporting conclusion.
Before reuse, refresh time-sensitive scope pages and recheck every arithmetic row. In addition, treat the self-check as a study signal, not a pass probability, licensing conclusion, or readiness score.
Payables bonds questions and answers FAQ
What should I write before checking an answer?
Write the controlling fact, requested unit, rule, and nearest distractor. This makes the explanation reusable on a new fact pattern.
Why can the invoice total be wrong?
An approved return or credit memo can reduce the obligation, so the net receipt may be the controlling payable amount.
How do I repair a contingency answer?
Separate probability from estimation. Change one field at a time and then reconsider recognize versus disclose.
Are these questions a readiness score?
No. They are original study questions. Use the first broken field to choose a narrow retry rather than treating the result as a prediction.